The Russian multi-unit housing market: a consensus forecast up to 2030

Written by Andrey Vakulenko – MACON, EECFA Russia

As the residential real estate market in Russia continues to struggle with high key rates and expensive mortgages, the main question in the coming years is not so much the expected rate of reduction, but the speed of this reduction and how quickly market mortgages can replace shrinking preferential programmes. Based on data from ten major think tanks, MACON has compiled a consensus forecast for the multi-unit housing market over the next five years.

Fundamental framework for the housing market in the coming years remains quite conservative

Key forecasters—the Bank of Russia and the Ministry of Economic Development—both predict that inflation will gradually decline, but at high stakes, causing a general economic cooling and minimal growth in the coming years. Expected GDP growth in 2026 is to be 0%-1% annualised, accelerating to 1.5%-2.5% in 2027-2028.

The key rate is forecasted to average 14.6% in 2026, with a further decline to 10.5%-12.5% ​​in 2027 and to around 9% in 2028. In early 2026 a more pronounced rate cut was expected, but by July the trajectory of monetary policy easing had become noticeably more restrained. Inflation is falling at a slower pace than planned, so the Central Bank is also lowering the rate more slowly.

Market mortgage rates will also likely decline, but gradually rather than sharply, which is crucial for the housing market: the cost of financing remains one of the main factors determining home purchases.

Baseline consensus forecast for the multi-unit housing market

Multi-unit housing market forecasts made at the beginning of 2026 by 10 different sources have been complied: rating agencies (ACRA, Expert RA), banks (Alfa-Bank, Sovcombank), institutional companies (DOM.RF, ЕРЗ – erzrf.ru), consulting companies (Yakov and Partners, Strategy Partners, MACON) and the Centre for Macroeconomic Analysis and Short-Term Forecasting (CMASF). The consensus forecast has been broken down to five key indicators: housing completions, new project starts, new mortgages, primary market sales and prices in the primary market. If we combine the forecasts for all five indicators, we get a fairly consistent picture of a gradual recovery cycle:

  • 2026: stabilization – demand is to stop declining, mortgages are to begin to recover, although development activity is to remain under pressure.
  • 2027: start of recovery – mortgage market may grow, demand may increase and developers may begin to start new projects more actively.
  • 2028: turning point in supply and development activity – recovery in demand and new project starts should begin to be reflected in housing completion.
  • 2029–2030: a period of stable growth – the rate of increase for most indicators will likely moderate and the market is likely to gradually enter a stable trajectory.

The logic here is that the recovery of the mortgage market should support demand, growth in demand would halt the shrinkage in development activity and first, new project starts would grow, and after a few years this effect would start to show in housing completion.

Prices in the primary market remain the most stable element of the forecast. There are not enough preconditions for a sharp increase, but there are no grounds for a large decrease either. High construction costs and financing costs will form the lower price limit, while limited purchasing power, amid a gradual decline in rates, will form the upper price limit.

Thus, the coming years are more likely to bring a gradual recovery than a new boom in prices and development. As the market will not return to the previous model based primarily on mass, preferential mortgages and demand will be more and more generated by market lending, the decline in key and market mortgage rates is the main factor in forecast uncertainty. So, the market remains quite sensitive to decisions in ​​monetary and mortgage policies.

Alternative scenarios of the consensus forecast

Since the range of expert opinions on a number of indicators for 2026 turned out to be quite large, we can identify not only a basic consensus forecast, but two alternative scenarios as well. Differences between the two scenarios mainly concern 2026 as in subsequent years forecasts for most indicators converge much more closely:

  • In the pessimistic scenario, demand recovery in 2026 is significantly weaker. Mortgage lending would grow by only 7%, primary market sales would drop by 13% and new project starts would fall by almost 15%, limiting growth for housing construction in 2028.
  • In the optimistic scenario, more rapid monetary easing and the maintenance of the Family Mortgage Programme terms would allow the mortgage market to grow by 17%, and demand by 2%. Developers could increase new project starts by 15% as early as 2026, leading to higher growth in housing completions (about 12% in 2028).

Key indicators in the consensus forecast

Housing completion volumes are to go down by 5% in 2026 and by another 8.5% in 2027, followed by a gradual transition to growth: +3.8% in 2028 and +7.6% in 2029. Thus, 2026-2027 is a correction phase and 2028-2030 is a period of recovery in developer activity. Experts generally agree on the direction of future trends but differ on the estimates of their scale. There are two scenarios for 2028: in the positive one, completion could grow by about 12%, while in the negative one, only by 1.5%.

The highest uncertainty is in new project starts. The difference in expert estimates is based on different assumptions about developers’ reactions to the current market situation: the decision to start a new project is sensitive to demand, the cost of project financing, construction costs, and expectations of future sales. So, the divergence between the scenarios is the most noticeable here. In the optimistic one, new project starts in 2026 could grow by 15.3%, while in the pessimistic scenario, they could drop by 14.5% (the consensus is -4.6%). So, the market is at a point where developers are beginning to look beyond the current decline in demand but are not yet confident in the speed of its recovery. Starting in 2027, experts are much more unanimous in their expectations with a stable growth of 5%-10% per year.

The most positive dynamics are expected in new mortgages where the consensus forecast is +12% in 2026 and +24% in 2027, followed by +12%-13% annually in 2028-2030. However, the forecast for the current year remains less certain than expectations for 2027-2030. The optimistic scenario projects a growth of 17% in issued mortgage loans for 2026, while the pessimistic scenario projects only 7%. The difference is mainly due to the differing expectations regarding the pace of monetary easing and the availability of market mortgages. Going forward, as rates decline, market mortgages should gradually become the primary source of demand.

The consensus estimate is that primary market sales in 2026 can grow by just 1%, suggesting that rate cuts are not yet enough to fully restore demand, but experts don’t expect a further decrease. However, there is also a negative scenario: the possible tightening of the Family Mortgage Programme could lead to a drop in the number of transactions by about 13% as early as 2026. For 2027-2029, the number of transactions is to grow by 7%-9% per year, while it is to slow down to 4% in 2030.

Prices in the primary market appear to be the most stable element of the forecast. Consensus forecasts are for the price per square meter to add 6%-8% per year in 2026-2028, followed by 5%-6% per year in 2029-2030. One could ask why prices continue to rise even with limited demand. On the one hand, growth potential is limited: purchasing power remains a restraining factor, and the level of sales in projects under construction is relatively low. On the other, developers face high construction costs and high project financing. Thus, there is limited room for price reduction, and the most likely scenario is a moderate nominal price growth without a sharp acceleration.

How does the forecast compare with the reality so far?

Based on the results of H1 2026, actual demand almost perfectly matched the consensus forecast. This applies to both primary transaction volume and the mortgage market.

Price dynamics are also relatively close to the forecast range, although the direction is still different: experts anticipated moderate price growth by the end of the year, while the first half of the year showed a nominal negative correction.

Development activity is better than expected. Both housing completions and new project starts showed growth between January and June 2026 despite the consensus forecast for a moderate decline for the year. The discrepancy in multi-unit housing completions is particularly noticeable: the actual dynamics of H1 exceeded even the most optimistic expectations.

Yet, as the first-half-year results are not representative of the year and some indicators exhibit significant seasonality, it doesn’t mean that the forecast needs to be fully revised. It indicates though that market supply is demonstrating greater resilience than hoped for.

Methodological approach to the consensus forecast

The methodology is based on the median of all available forecast estimates for each indicator. The median was chosen deliberately: unlike the mean, it is resistant to outliers and better suited to the real estate market where expert estimates often greatly differ.

To assess the extent to which experts agree with each other, the interquartile range (IQR) is used—the difference between the third and first quartiles of the sample. It shows how widely opinions differ regarding the central range of forecasts. The smaller the IQR, the greater the agreement among opinions and the greater our confidence in the consensus estimate. The assumptions used to interpret the results were: IQR < 3%: very high predictive certainty; 3–6%: high predictive certainty; 6–10%: moderate;10–15%: low; over 15%: very low.

Where consensus estimates are low, the consensus forecast is supplemented with optimistic and pessimistic scenarios constructed based on the upper (third) and lower (first) quartiles, respectively (the optimistic scenario focuses on the upper part of the expert estimate range, while the pessimistic scenario focuses on the lower one). This way, uncertainty can be conveyed through a single figure, and a realistic range of possible market development can be shown.

Q2 2026 Permit-Completion in EECFA area

The viz was updated on 16 September 2026.
→ Ukraine published its Q2 permit figs and they look good.

In Serbia there is lasting optimism, but in Croatia there has been some shrinkage lately. These countries experienced massive permit expansions between 2014 and 2022 and they have remained at around their peak for quite a while. Serbia has had around 7 million permitted m2 (residential and non-residential combined) for over four years and Croatia had been above 4 million for three years since 2023. It is no longer true due to the worsening non-residential permit figures. Slovenia remained below its 2022 peak despite some positive correction in H1 2026. Expansion continued in Bulgaria, the 9 million m2 (record of the last 15 years) has been surpassed. Recovery in Romania and in Hungary paused in Q2 because of the drop of non-residential permits.

You may use the dropdown in the viz for selecting either the residential or the non-residential submarket, or both.

See the full viz: EECFA Permit-Completion Quarterly – 16 September 2026

In the full visualization, not only permit but completion data can be followed (where available). Just click on the Country-by-country sheet.

Despite the slight correction in residential segment, figures in Türkiye are still extreme. More than 1.2 million dwellings obtained construction permit in the last 4 quarters. (From Q2 2025 on, permits issued by authorities other than the municipalities are also published by TUIK. So the scope is bigger, the results show the full picture. Click through the below viz for understanding the size and the impact of this revision.) Q2 2026 has been the best quarter in Ukraine since the beginning of the war. This was the second quarter, however, when residential was not able to grow. The expansion is driven by the increasing permit figs of non-residential buildings. Russia is relatively stable when it comes to building completion. There is slight uptrend in non-residential and a downtrend in residential.


This visual about the significance of the permit revision in Türkiye was compiled back in September 2025.

Will publicly developed housing keep Turkish residential construction resilient?

Written by Prof. Dr. Ali Türel and Prof. Dr. Leyla Alkan Gökler, EECFA Türkiye

In H1 2026 Türkiye saw construction costs go up, which is biting into private housebuilders’ profit margins, while house price growth decelerated in real terms. Permit numbers grew in the first half of the year thanks to the public housing schemes of the government. However, Q2 2026 was already weaker in building permits and construction production, so it remains to be seen whether these public programs will keep residential construction strong.

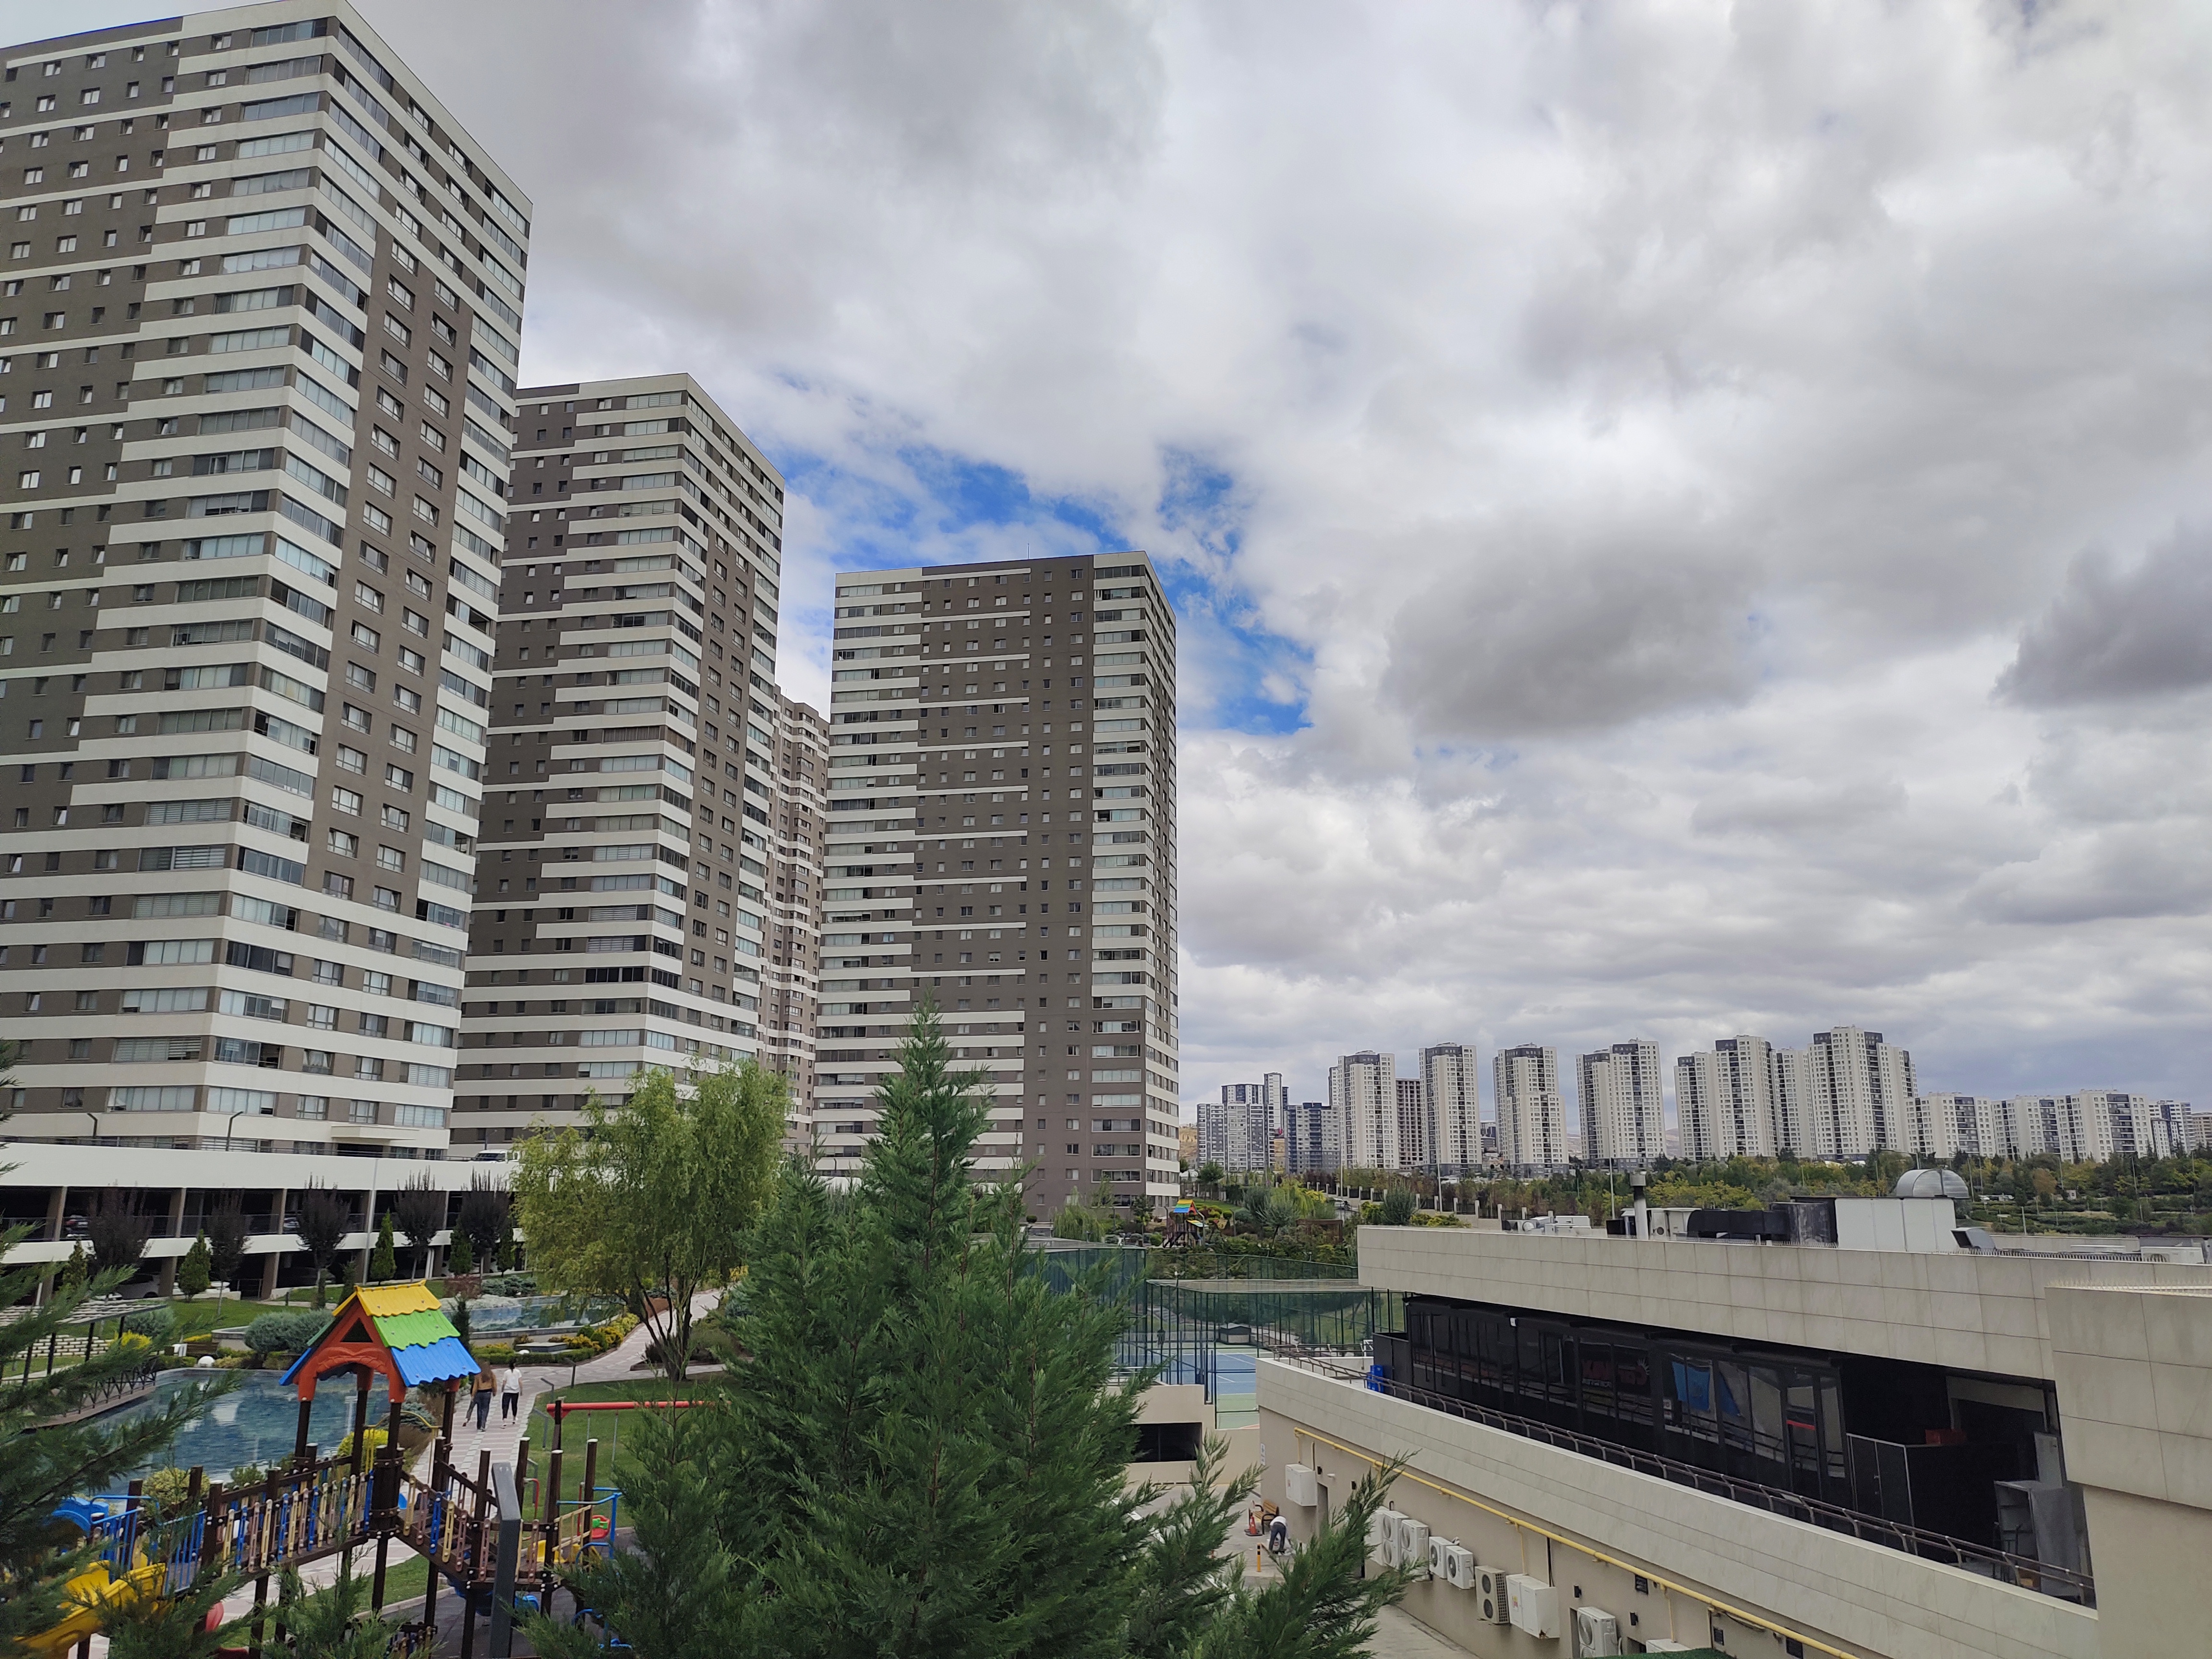
Residential buildings and non-residential development in Ankara – Photo by Prof. Dr. Leyla Alkan Gökler

H1 2026 statistics: construction costs, house prices, building permits

According to the statistics gathered and published by the Turkish Statistical Institute (TurkStat), a comparison of the monthly rates of change in the Consumer Price Index (CPI) and the Construction Cost Index (CCI) for residential buildings shows that construction costs increased at a slower pace than inflation in 2025. In January 2026, however, CCI recorded a considerable increase, while during the remainder of the first half of the year it generally continued to rise at a higher pace than inflation.

A comparison of the monthly rates of change in the Consumer Price Index (CPI) with the House Price Index (HPI) for 2026, published by the Central Bank of Türkiye, indicates that house prices also increased at a slower rate than inflation through June. Looking at the cumulative changes in these three indicators during H1 2026, CPI added 17.76% in June compared to December 2025, while HPI rose by 13.20% and CCI by 20.07%. These figures indicate that house prices grew at a slower pace than inflation during H1 2026, implying a decline in house prices in real terms. In particular, following the sharp increase in the building construction cost index in January 2026 over the rate of increase in house prices, this would inevitably cause a significant decline in profit margins for housing producers.

The number of dwelling units granted building permits reached 513,731 in H1 2026, indicating that construction permits were issued for 35,071 more dwelling units than in H1 2025. In terms of completed dwellings, occupancy permits were issued for 306,687 residential units during H1 2026, representing an increase of 28,990 units compared with the same period of 2025.

New housing developments at the Fringe of Ankara – Photo by Prof. Dr. Ali Türel

Public housing programs

Over the past three years the number of dwelling units granted building permits posted a massive growth, exceeding one million units in 2025, one of the main reasons being the rapid housing reconstruction program undertaken or financed by the government following the major earthquakes of 2023. By the end of 2025, the construction of as many as 455,000 urban and rural housing units, the majority of the post-earthquake housing units to be built, had been completed and delivered to legal beneficiaries.

The Housing Development Administration (HDA, the central government institution) has also been preparing a new social housing program with the intention of providing quake-resistant, low-cost housing with affordable prices, comprising 500,000 housing units since October 2025. Therefore, despite rising construction costs, housing construction continues at a relatively strong pace, with publicly developed housing accounting for a substantial share of building permits. Rise in the building construction cost index at a higher rate can also be related to the effects of the new social housing program of the HDA, and the remaining works of the reconstruction program of earthquake-damaged housing.  

High-rise housing developments in Ankara – Photo by Prof. Dr. Leyla Alkan Gökler

Construction output

Despite the increase in building permits during H1 2026, this momentum has struggled to translate into actual construction output. Calendar-adjusted Construction Production Index declined by 3.1% year-on-year in May and by 6% in June. These falls may be linked to the nearing completion of earthquake reconstructions, as well as the 9.5% fall in housing permits in Q2 2026, although completions have continued to grow since Q2 2025, most likely under the effects of the completed reconstruction of the remaining earthquake-damaged housing. 

With house price increases remaining below the rise in construction costs, the slowdown in construction output suggests that increasing cost pressures and narrowing profit margins are constraining the pace of the private sector’s housebuilding activity. Housing demand is also negatively affected by high interest rates as mortgage credits could be used in only 22% of housing transactions in 2026.

Residential market forecast for Türkiye up to 2028 is available in the EECFA Forecast Report Türkiye. For sample report or orders, contact us.

Traditional residential settlements in Ankara – Photo by Prof. Dr. Leyla Alkan Gökler

EECFA 2026 Summer Construction Forecast

EECFA’s 2026 Summer construction forecast up to 2028 was released on 22 June. Sample report can be viewed at eecfa.com. To obtain the new reports, please contact us

Southeast European construction markets up to 2028

Bulgaria stepped into this year as the 21st member state of the eurozone in the middle of an evolving political turbulence that inevitably impacted the construction sector, most notably, projects that rely on public funding. Nevertheless, according to Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian member institute, Bulgaria’s total construction output is anticipated to increase by approximately 2% on average in the forecast period of 2026-2028. He also notes that “Last year Bulgaria’s construction sector excelled with a strong performance, largely thanks to the residential and non-residential submarkets which fared better than previously predicted. In 2026-2028, however, the country’s total construction output could see a heterogeneous performance.”

Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s members for Croatia, point to funding from the EU’s Military Mobility Package (MMP) as a promising source of finance for a wide variety of Croatian construction projects. Transportation ones, both straightforwardly military and dual use, are obvious contenders, so the availability of MMP money should lift output in those civil engineering segments. MMP will likely boost some non-residential segments, too, since it can finance, e.g., factories and logistics centers (perhaps even flight schools?) that have a military or dual-use purpose. This will help sustain total construction output despite rapidly declining levels of finance under the EU’s post-2022-earthquake rebuilding programs and RRF. In non-residential generally, while some developments will affect all segments, specific factors will ensure that output growth varies greatly from segment to segment. The picture for energy construction is also confused, with solid, well-known technologies competing with much-hyped, as-yet-unproven, “hi-tech” alternatives. Residential is buffeted by the conflicting influences of rising prices, declining GDP growth and interventions by the central bank and the government.

Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild, notes that Romania’s construction market is still in a tight spot. “Growth potential is limited with global and national factors conspiring against it. Recent economic forecasts are more pessimistic; 2026 might see a stagnant GDP, declining real wages and the highest inflation in the EU. This is coupled with the looming specter of national deficit causing high taxation and austerity measures: lower public spending, and wage and hiring freezes for public employees. Not to mention that construction costs, which started evening out in 2025 after the 2022 shock, are now again on the rise due to climbing energy prices and labor costs. The saving grace of construction is the EU programs funding infrastructure projects. Yet, with the NRRP running out in mid-2026, and other programs having an inconsistent performance, the boost they can provide is limited. Adding to all this is a political crisis that could lead to a government change at a critical moment (the end of NRRP absorption, projects phased into other funding sources). But the silver lining: most of these issues should be transitory. By 2028 Romania’s construction might return to growth on the back of improved economic indicators, inflation levels within the target range, a more efficient energy sector, and hopefully, a more stable political situation.”

“Serbia’s overall construction output is still consolidating in 2026 led by the correction in civil engineering, while buildings continue to grow in this forecast” – according to Dejan Krajinović, EECFA’s Serbian researcher at Beobuild. He adds that the performance in the residential submarket remains stable and is predicted to continue to grow with moderate growth rates. Non-residential, on the other hand, is booming, driven by massive investments related to the EXPO 2027, with another year of double-digit growth expected in 2026. Main segments benefiting from ongoing developments are office, commercial and hotel, but health-related construction is also breaking records in 2026. The consolidation in civil engineering is anticipated to end in 2027, with new growth on the horizon in 2028 and onwards. The large-scale infrastructure projects in the pipeline should launch a next big growth cycle in overall outputs. However, the war in the Middle East is already pushing construction costs up and the economic uncertainty and fragmentation are still risks that continue to linger in the coming period.”

“Slovenia’s construction sector’s output was holding steady at just under €6bn in 2024 and 2025 but is set to edge higher in the forecast period, supported mainly by public spending” – says Dr. Aleš Pustovrh at Bogatin, EECFA Slovenia. “Growth is increasingly uneven: residential construction remains constrained by limited supply and rising costs despite strong demand, while private non-residential segments such as offices, retail and industry face cautious investors and only modest expansion. By contrast, publicly financed segments, notably education, health and civil engineering renovation, are providing stability, with infrastructure upgrades, railway investment and energy-transition projects sustaining activity. Transport and utility constructions are shifting from large expansions to maintenance and modernisation, and investment in electricity networks and pipelines is set to rise further due to the energy transition. Overall, the sector is moving into a more stable but slower phase where public policy and infrastructure spending play a decisive role in keeping output on track – as long as public financing remains available.”

Eastern European construction markets up to 2028

According to Andrey Vakulenko at Macon, EECFA’s Russian research institute, the downward trend in Russia’s construction market, which began in 2025, is likely to continue and intensify in 2026–2027. The main reason behind is the combination of a decelerating economy and a prolonged period of high interest rates, which negatively impacts demand, limits the availability of financing and restrains investment activity. Residential construction is experiencing the strongest pressure as the market struggles to find a new balance amid reduced mortgage availability, declining demand and decrease in new construction. Most non-residential segments may also show negative dynamics in the coming years impacted by the slowdown in consumption volumes and business activity, weak household income growth and changes in the direction and scope of government funding in certain segments. Civil engineering will likely stay the most resilient subsector due to the implementation of major transport and energy projects. The planned acceleration of infrastructure construction, the expected growth in the residential submarket and the easing of monetary policy are the conditions for the construction market to return to a growth trajectory in 2028.

“In Türkiye, state involvement in housing development has grown in recent years” – say Prof. Ali Türel and Prof. Leyla Alkan Gökler, EECFA’s Turkish researchers. “Policies to curb inflation have depressed households’ disposable income, creating a serious housing affordability issue for both ownership and renting as home prices and rents have spiked. As moderate-to lower-income households have found it increasingly difficult to accumulate sufficient equity for home purchases, the government has intervened. It launched a large number of residential projects for dwellings that can be bought on affordable terms by households not owning a house in Türkiye. Dwellings will be built by the Housing Development Administration (HDA), the key state actor in housing production in Türkiye. Since HDA has also been involved in rebuilding the about 550,000 dwellings damaged in the February 2023 quake, the share of housing built by the public sector has greatly risen in recent years, while the share of the private sector has been declining from its former share of about 90%. Our latest forecast indicates that total construction output in Türkiye may reach nearly 8 trillion TL (nearly EUR 180 billion) in 2028, at 2025 prices.”

“Ukraine’s construction market exhibited high resilience in 2025 despite the ongoing war and challenging security conditions. While it is recovering and it nominally returned to pre-war levels last year, it was still 40% below the 2021 output at comparable prices.” – notes Professor Sergii Zapototskyi at Uvecon, EECFA Ukraine. “Key growth drivers were commercial, industrial, warehouse, and logistics developments, an uptick in residential construction in relatively safe regions, and large-scale projects aimed to restore public and transport infrastructure. In the coming years, the construction market is expected to continue to grow, supported by post-war reconstruction needs, government housing support programs, and an increase in international funding for Ukraine’s recovery. The greatest growth potential will remain in residential, commercial, as well as industrial and warehousing construction. At the same time, the future performance of the market will largely depend on the security situation, the availability of investment resources, the ability to address labour shortages, and the effectiveness of government reconstruction policies.”

Rusty

With the latest governmental decision, the number of projects in designated rust belt action areas reached 91 in Hungary. 50 thousand dwellings1 are estimated to be built on these brownfield sites. The sole purpose of this post is to follow these projects and to see how they will or will not help the recovery of the new residential construction sub-market in Hungary.

Status on 1 May 2026.
Before the election project starts slowed down. The newly elected government promises to double the number of built homes.
—
Completed: 4 018 dwellings
Under construction: 12 622 dwellings
Before construction: 27 180 dwellings

Brief background

Rust belt action areas (let me shorten them to rusty) are practically brownfield areas with special benefits. The owner of the site or the developer should initiate the process (with specific development plans) and there is a Committee to examine if the proposed site is entitled for the rusty status. Based on the opinion of the Committee, the final decision is made by the government. The decisions (about the exact sites) are announced in a decree and the special benefits coming with it are:

  • priority investment status, meaning e.g. faster permitting procedures2,
  • newly built homes can be sold at 5% VAT without limitation in time3,
  • this 5% can be reclaimed by the buyers4.

By the current regulations, it means a min. 5% and a max. 27% price advantage over competitors developing on non-rusty area until 2030 (depending on when the permit was obtained) and a 27% price advantage from 2031 on.

Our focus

What we do is to turn the mentioned decree into information we need for forecasting. With the help of Eltinga Building Permit Monitor database and the iBuild project information database, actual projects are identified from the lot numbers specified in the decree. Among all the general project specifics, the number of dwellings (where it is known), are attached to these projects.

The map shows the stages of the housing projects that were given rusty status. Bluish dots are those before construction, neon yellow dots are those under construction and the dot disappears once the project is completed.

OK, it is very convenient to see projects on a map, but our focus is more on the chart under the map where the yellow is the number of homes under construction.

What we are curious about is if and when the right end of the yellow curve shows a strong upturn.

In other words, we are curious whether the regulation ignites a recovery or not. In the first years of the regulation, it was more common that the yellow line has increased because projects having started in the past were given the rusty status. (So they were just re-qualified, it did not mean new project starts.) In parallel, it was less common that projects start after they were given the status. Just two extreme examples for these: Unipark Buda had been under construction between 2019 and 2024 and it got the rusty status at the end of 2023, while Láng District was given the rusty status in 2021 and actual works commenced 5 years later. This has changed by now. So currently the yellow line increases if new projects starts. More precisely if the number of dwellings in newly started projects outnumbers the number of dwellings in completed projects.

The charts are updated quarterly.

Another way we like to look at it is a list. Here we do not separate the projects to phases (like on the map) and it gives a quick understanding on how each rusty project moves ahead from 1 February 2024 on.

Data sources

The data mostly come from Eltinga Building Permit Monitor (in Hungarian: Építési Engedély Figyelő). This is a very detailed database on before construction multi-unit housing projects in Budapest. It is aiming primarily at developers who would like to understand the competition. For further information on this, please turn to Mr Zoltán Sápi, Eltinga, sapiz@eltinga.hu. Besides, we use the iBuild project information database.


  1. This is an estimation based on the median size of those rusty projects where the number of homes were announced ↩︎
  2. 619/2021. (XI. 8.) Korm. rendelet
    a rozsdaövezeti akcióterületek kijelöléséről és egyes akcióterületeken megvalósuló beruházásokra irányadó sajátos követelményekről
    ↩︎
  3. 2021/8. Adózási kérdés – A rozsdaövezeti lakások értékesítésének adómértéke ↩︎
  4. Rozsdaövezeti adó-visszatérítési támogatás ↩︎

Top trends to track in 2026 in Romanian residential market

Written by Dr. Sebastian Sipos-Gug – Ebuild srl, EECFA Romania

Dr. Sebastian Sipos-Gug, EECFA’s Romanian analyst has looked at the trends that are worth monitoring in the residential market in Romania this year. Among them are the construction costs boomerang, the drop in wages and consumption, considerable interest in multi-family buildings, smaller homes and a greater dependence on mortgage loans.

What we saw in 2025

The construction market faced many challenges in the previous year, alongside the entire national economy. While there was a focus on civil engineering, especially when it comes to EU co-funded projects, the rest of the segments lagged behind.

In early 2025, the removal of fiscal facilities for construction employees led to the decline of their net incomes, and an increase in wage-related expenses for companies. Overall, the effect of this measure was an increase in construction costs.

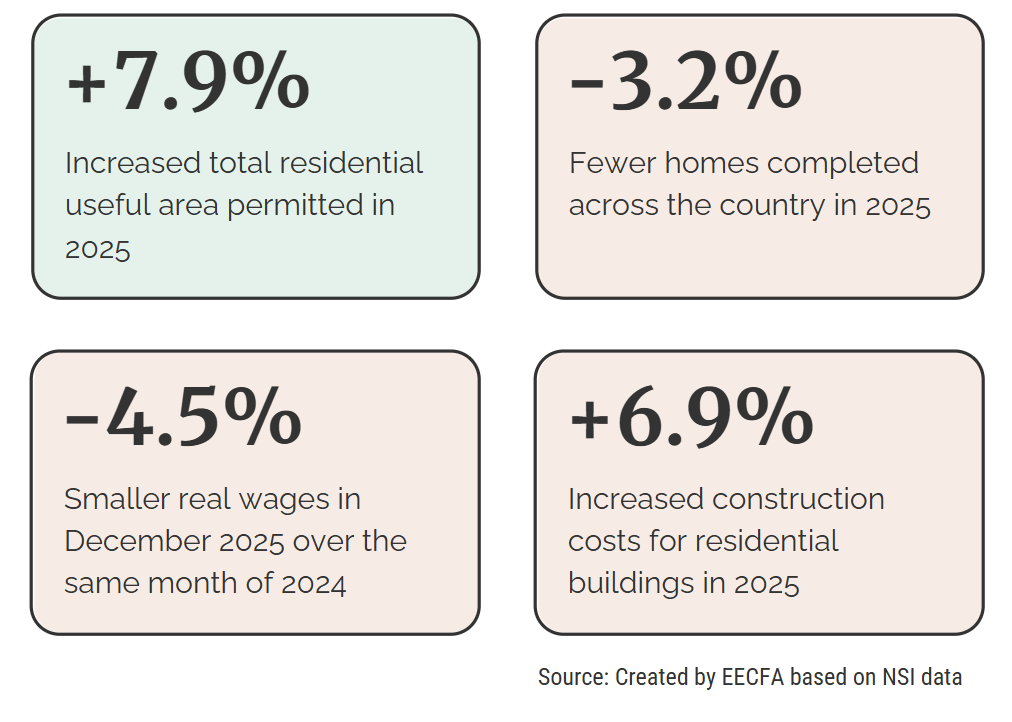
Then came the multiple shocks of the liberalization of energy markets in July, and a VAT increase in August, which pushed inflation upwards significantly, with the CPI reaching 9.88% in September. In a snowball effect, this led to lower real wages and disposable income, which translated into a reduction in private consumption, and, ultimately, means lower demand for residential construction on the short and medium terms.  

The optimism shown in the increased number of permits, and the useful building area in them, compared to 2024, is countered by the decline in the number of completed homes. Thus, while developers might be looking to the future, their actions in the present are lacking, also evidenced by a significant (-21%) annual decline in the value of started construction works in 2025 (source: EBI Construction Activity Report).

What to watch in 2026

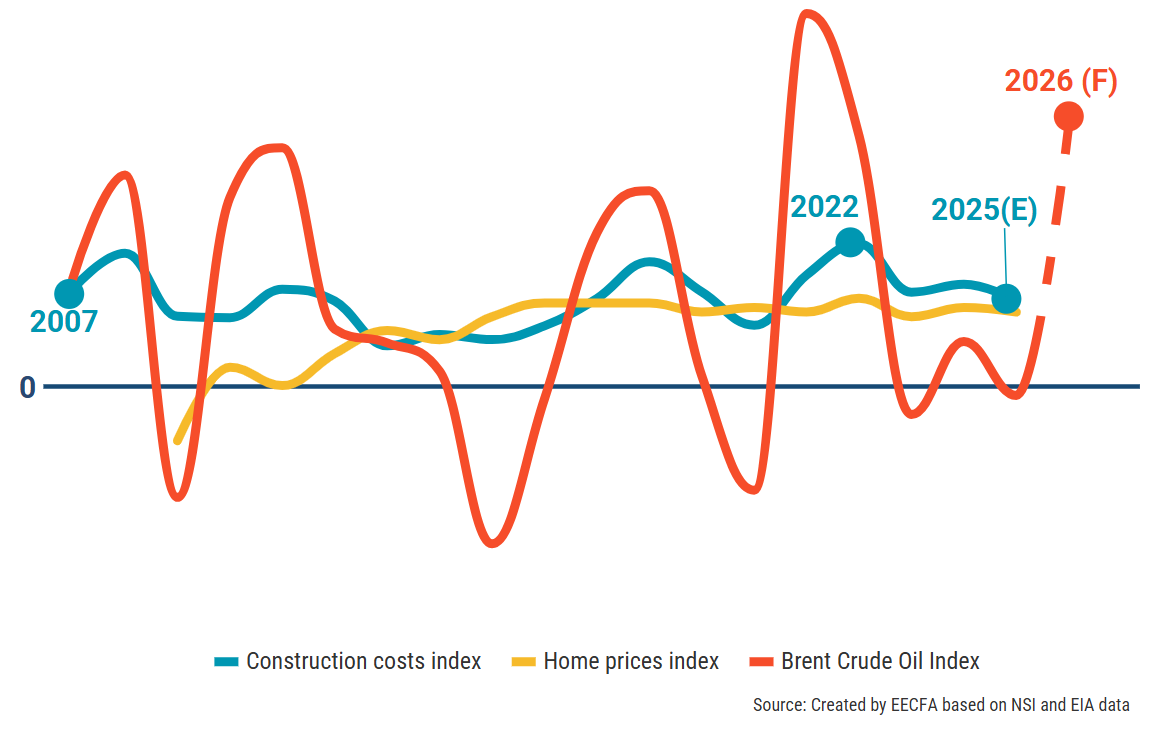
Construction costs boomerang. While previously the expectation was that construction costs would gradually decline in 2026, they proved quite resilient to changes in wages, and fuel and construction materials prices remained relatively stable in the past year.  Thus, late 2025 forecasts placed construction costs on a small, descending trend.

The conflict in Iran and its repercussions on oil and gas prices might throw astray these predictions. As of March 2026, oil prices were approaching 2022 levels, and, if they are not reversed rapidly, might have a similar impact on world-wide inflation, energy prices and, eventually, construction costs. A reversal, however, seems rather unlikely at the moment as the damage to energy infrastructure could take years to undo.

To make matters worse, in the past few years home prices grew slower than construction costs, reducing potential profit margins for developers. Added to the decline in real wages, it remains quite unlikely that there will be room for prices to increase alongside construction costs, again similar to 2022, further eating into builders’ financial return potential.

Decline in wages and consumption. Wage growth for 2026 was already forecasted to remain low, underperforming inflation (source NFC – National Forecasting Commission Autumn 2025 Report). Add to that the further shocks now expected from increased energy costs (due to oil and gas prices rising considering the conflict in Iran) and food costs further rising due to increased fertilizer prices, the downwards pressure on real wages is likely to be worse than forecasted, with a slower recovery.

Real wage decline will make it harder to purchase and build new homes, with a negative impact on demand for residential construction. But it could provide a boost to renovation activity, especially when it comes to energy efficiency, as switching homes becomes harder.

High interest in multi-unit residential buildings. Looking at building permits trends for the past decade, single-home buildings have remained relatively stable, while the majority of growth was due to multi-unit buildings. Under price pressure, on the backdrop of restricted wage growth and a contractionary macro-economic outlook, it remains most likely that for the near future we’ll continue to see more interest in the latter. Another connected issue is that of internal mobility, with migration from rural to urban areas in search for education and economic opportunities, increasing demand for denser residential construction.

Smaller homes. While the mean area in permits remained relatively stable between 2017 and 2025, there is a historical precedent in economic downturns leading to smaller homes being built so as to increase accessibility. Since the economic outlook for the year seems to have worsened, this could be the case again in 2026.


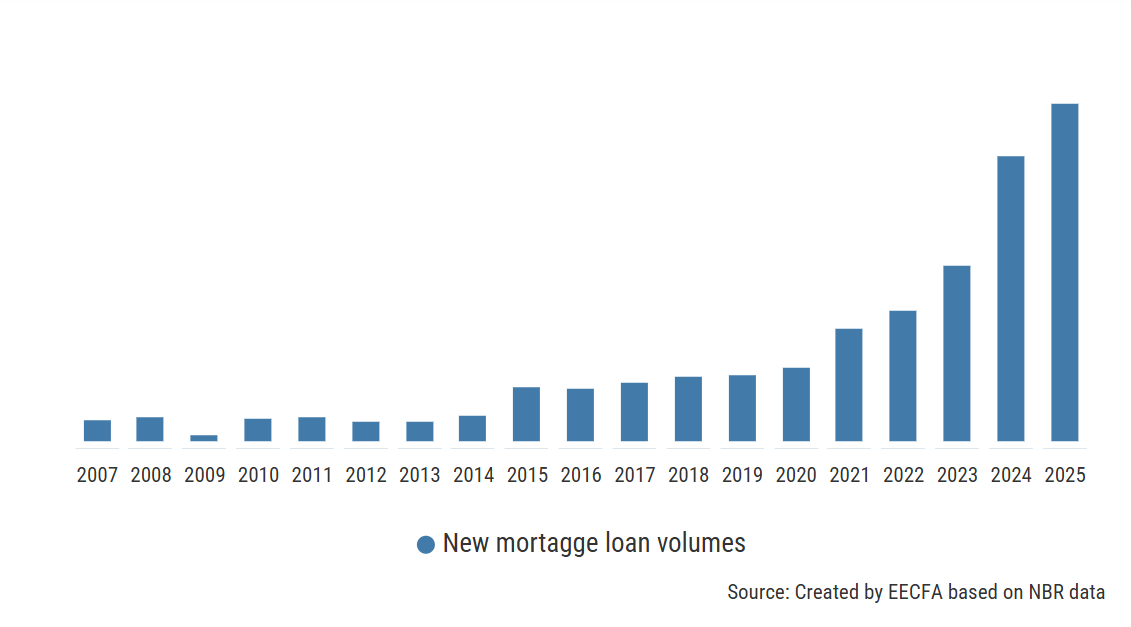
Increased reliance on mortgage loans. Despite the highest interest rates seen in a decade, the volume of new mortgage loans increased dramatically in 2024 and 2025. While some of this could be blamed on higher home prices, there remains a major portion that cannot be explained by price or transaction dynamics. Thus, it is quite likely that it reflects a reduced ability to buy homes without applying for a loan. This is also evidenced by the fact that the share of the population currently housed in a dwelling that was purchased with a mortgage loan grew steadily from a low of 0.5% in 2007, to 1.5% in 2024 (source: Eurostat). This could have been further boosted by the expected drop in interest rates as inflation seemed to be heading in the right direction. However, as of March 2026, this seems less likely, as the conflict in Iran would lead to another energy-led inflation event. Nonetheless, with real wages on the decline, mortgage loans will continue to be relied on for boosting home affordability.

Slovenia’s housing squeeze no one can measure

Written by Dr Aleš Pustovrh – Bogatin, EECFA Slovenia

Slovenia’s housing market is in a curious state. Prices for both new and existing homes keep rising, yet the country still lacks a reliable measure of how far supply trails demand. Official data show steady appreciation across all major cities—Ljubljana most of all—while construction remains hampered by slow permitting, high input costs and a fragmented building industry. Politicians promise a surge in public and affordable housing but estimates of the true shortfall—whether based on household formation, demographics or unmet rental demand—are patchy and inconsistent. The average price per square metre has jumped by roughly 50% since 2021, but the structural imbalance behind this surge is harder to pin down, leaving policymakers to grapple with a problem they can only describe vaguely.

Ljubljana, Slovenia. Photo by Alexander Nadrilyanski on pexels.com

With a general election looming in March 2026, the absence of clear data creates fertile ground for confusion and political spin. The ruling coalition boasts of raising annual public‑housing investment to €100mn, pledging €1bn over the next decade. The public housing fund plans around 2,000 new units in the coming years, with perhaps 1,000 more from other public bodies. Private developers, especially in Ljubljana, are building briskly, too. Given that Slovenia completes about 5,000 homes a year, these additions ought to shift the market—at least in theory.

But the scale of need remains uncertain. In 2021 Slovenia counted 864,300 dwellings for 859,782 households—roughly one per household. Prices, though rising fast, remain below those in some neighbouring countries. The median price of used homes was €3,070 per square metre (nearly €5,000 in Ljubljana), while the average gross monthly wage was €2,500—yielding a price‑to‑income ratio lower than in many EU states. Mortgage credit is widely available and relatively cheap, with interest rates well below 4%. Outstanding housing loans rose from €8.5bn to more than €9bn in 2025, suggesting that many households are managing their residential construction investments without state support.

One of the outgoing government’s flagship measures—a clampdown on short‑term rentals—was meant to push more homes into the long‑term market. It may instead swell the ranks of empty properties: around 19% of dwellings already stand vacant. A straightforward remedy, a property tax to nudge owners to rent out unused homes, was avoided for fear of angering voters in a country where 75% of households own their homes.

The lack of solid data allows politicians to champion measures unlikely to achieve their stated aims, while sidestepping those that might work but would prove unpopular. Election season is rarely conducive to sober policymaking, but the next government will need better data—and the courage to act on it—if it hopes to make any meaningful dent in Slovenia’s housing woes.

More on Slovenia’s housing market and housing forecast up to 2027 can be found in the EECFA Slovenia Construction Forecast Report. Sample report and orders: https://eecfa.com/

EECFA 2025 Winter Construction Forecast

EECFA released its 2025 Winter construction forecast on 12 December. Check out a sample report and place your order on eecfa.com. For discount, please contact us.

Southeast European construction markets

“Bulgaria’s total construction output is forecasted to increase by 3% on average for 2026-2027” – says Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian research institute. He adds that this is to follow estimates for a similar performance of almost 3% in 2025. The sectoral background, however, shows, a nuanced picture – cooling of residential construction, positive news from non-residential and a robust performance of civil engineering. The latter will benefit from investments which will be backed by the absorption of EU funds through the Recovery and Resilience Plan (RRP) and classical operational programmes, both with implementation deadlines in 2026 and 2027. At the same time, Bulgaria’s economy is to expand by 2.4% on average in 2026-2027 – a period continuously shaped also by the Euro adoption on 1 January 2026.

Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s Croatian members, think that declining dwelling sales in Croatia have, paradoxically, failed to stop the growth in the value of Croatian residential output, because increases in the price per square meter of those dwellings that do get sold have more than compensated for the lower number of square meters bought. “But how long this can continue is unclear” – they add. “The policies that the Croatian government is implementing in order to ease the country’s housing crisis are confusing the residential picture still more, since a number of those policies have contradictory effects on output. As to non-residential building construction, output growth during the period covered by the current forecast will depend greatly on the sector, with some likely to continue to benefit from catch-up growth and EU support for a bit longer and others moving toward a steady state or even a decline. In civil engineering, EU funds continue to play the dominant role in financing construction of all sorts. Sports facility construction is experiencing a boom, but given the speed with which such projects are completed, the effect on output will be relatively brief. Renewable energy construction should be growing rapidly, but regulators’ hostility toward the sector are holding it back.”

“Romania’s economy is entering a challenging period as the recently implemented measures to reduce the national account deficit begin to take effect” – reports Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild. “While most forecasters do not anticipate a recession, economic growth is expected to remain subdued over the next two years. Inflation is the highest in the EU, boosted in 2025 by increases in sales taxes. As a result, consumer prices are rising at a pace that is forecasted to outstrip wage growth, leading to a decline in real incomes in both 2025 and 2026. Government spending is also facing cuts, thus both private and public consumption are predicted to decline, with a chilling effect on most construction activity types. There is also the challenge of the massive level of public investment required by civil engineering projects that have started since 2023, which will be difficult to sustain under the austerity and the mounting pressure of losing even more EU funding. On the brighter side, both the economy at large and the labour market are expected to be quite resilient. By 2027, assuming the deficit reaches manageable levels, the effects of contractionary policies should fade out, inflation could ease, and interest rates could come down. This means that demand for construction would rebound and with it, construction activity.”

Dejan Krajinović, EECFA’s Serbian researcher (Beobuild) says that “Serbia’s overall construction output sank into a negative territory in 2025, primarily owing to the weaker performance in civil engineering. This year recorded growth in building construction, but the substantial consolidation in civil engineering dragged totals in red. The completion of major road, railway and energy projects contributed mostly, but delayed construction starts played a role as well. Residential construction is stable and is on historical levels, while non-residential construction is booming led by the hosting of the EXPO 2027 in Belgrade. Investments into commercial, hotel and office buildings are all spurred by the event, with the purposely built EXPO 2027 complex consisting of numerous venues being the single largest investment in non-residential. Improving financial conditions and sustained demand still support relatively high construction activity, but a lot of global political and economic uncertainties are dimming future prospects.”

Dr. Aleš Pustovrh at Bogatin, EECFA Slovenia, says that Slovenia’s construction sector is holding steady at EUR 6bn, though growth has cooled. Residential buildings remain the anchor, with output expected to show only a slight dip in 2025, helped by strong employment, rising wages and cheaper mortgages. Property transactions rebounded in early 2025, reversing last year’s slump, while prices continue to climb amid land shortages and slow permitting. Public housing programmes are ambitious, but private developers are concentrating on Ljubljana and coastal towns. Non-residential construction is mixed: offices are recovering slowly, retail stays subdued, but industrial and warehousing thrive on export demand and automation while health and education remain at very high levels. Civil engineering and public works lean on EU-backed projects and are anticipated to reach historically high levels by 2026. 

Eastern European construction markets

Andrey Vakulenko at Macon, EECFA’s Russian research institute notes that “the high key rate and the overall economic slowdown are constraining the Russian construction industry with negative trends expected for the current year and over the next two years. An easing of monetary policy, which has already begun, could help normalize the situation, but a positive effect is not expected until 2027. The main drag on construction output will likely be the residential subsector where high rates and revised government demand support principles are reducing activity among both buyers and developers. Negative trends will also likely persist in most non-residential segments due to declining growth rates of budget financing, a general decrease in business activity and a slowdown in consumption. The overall descending dynamics in the construction market may somewhat be mitigated by stable growth in civil engineering driven by export projects in energy and transport, but this growth is not predicted to be enough to keep the construction market in a positive zone”.

Prof. Ali Türel, EECFA’s Turkish researcher, reports that “the major effect of inflation-curb policies in Türkiye is the decline in disposable income and in the purchasing power of wage earners and pensioners. The moderate to lower-income population is unlikely to save enough equity for buying a home when rents have also become unaffordable for many. Ironically, housing sales have been increasing at a much higher rate than the growth of households. This can be attributed to the typical trend in Türkiye, where, during inflation, people expect a higher real return on their financial assets from real estate investments compared to alternative investment options. The reconstruction of earthquake-damaged buildings and infrastructure also contributed to the high rate of growth in building starts and completions from Q2 2025 onward, leading to the highest rates of change in the construction sector’s contribution to GDP compared to other sectors. Our latest forecast indicates that total construction output in Türkiye may reach 6.4 trillion TL in 2027 (EUR 180 billion), all at 2024 prices.”

According to Prof. Sergii Zapototskyi of Uvecon, EECFA Ukraine, despite the war and high risks, Ukraine’s construction industry remains one of the key drivers of economic recovery in 2025. The RDNA4 (the latest Rapid Damage and Needs Assessment Report) estimates Ukraine’s reconstruction needs for the next decade to be USD 486-524 billion, creating long-term demand for residential, non-residential and civil engineering construction works. Major challenges persist, including the uncertainty regarding the duration of the war, especially in frontline regions, labour shortages, bureaucratic barriers in the urban planning legislation, and logistical constraints due to the relocation of production facilities, and often, shortages in building materials. At the same time, the industry is demonstrating resilience: developers are diversifying supply chains, stabilizing procurement schedules, and increasing activity in the Central and Western regions. Demand for housing, intensive infrastructure restoration, and international investment from the EBRD, EIB, and other partners continue to support positive dynamics. The sector’s development prospects for 2026-2027 will largely depend on the security situation and the effectiveness of state recovery programs.

Housing needs of internally displaced persons in Ukraine

Written by Sergii Zapototskyi – UVECON, EECFA Ukraine

The full-scale invasion of Russia caused a deep humanitarian crisis and exacerbated socio-economic disparities in Ukraine. One of the key challenges is to provide homes for internally displaced persons (IDPs). The mass movement of the population created a shortage of affordable and temporary housing as the infrastructure was not ready for such a load. The government is already working on a new housing policy, which might also help resolve the issue of housing for IDPs.

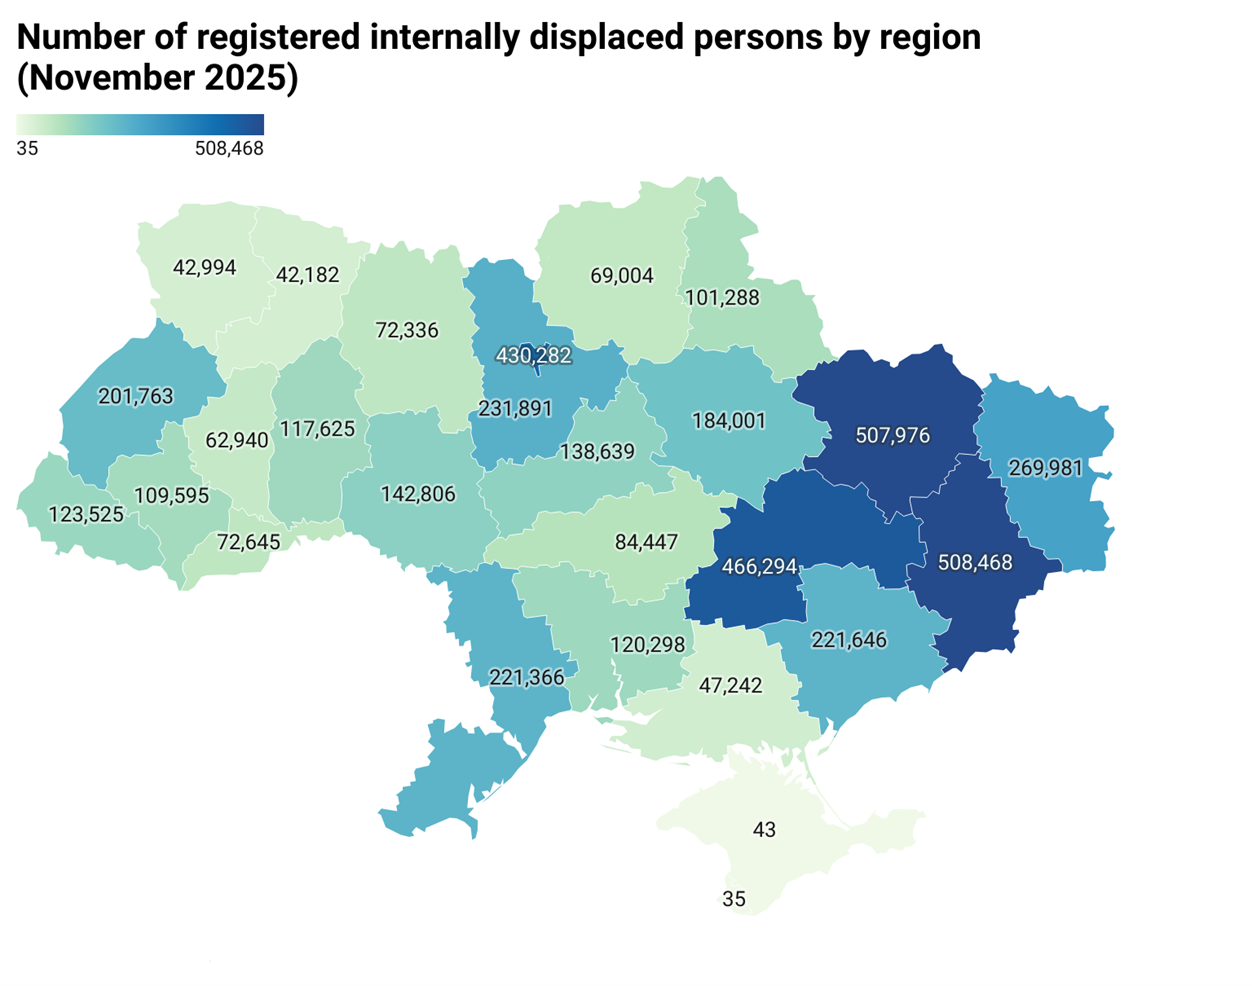
Source: https://www.ioc.gov.ua/analytics/dashboard-vpo

Statistics on internally displaced persons

As of 1 November, this year, 4,588,045 internally displaced persons were officially registered in Ukraine, including 838,436 children under the age of 18 [1]. Most IDPS are in Kharkiv region (508 thousand or 11%), followed by Dnipropetrovsk region (467 thousand or 10%), the city of Kyiv (430 thousand or 9.4%) and Kyiv region (232 thousand or 5%). [3]. IDPs in these regions total about 1.6 million people [1]. As per the result of the 16th round of the survey conducted by The International Organization for Migration (IOM, UN Migration), as of April 2024, about 2.7 million internally displaced people were from frontline areas.

Housing damages, needs and solutions

In total, more than 1.3 million Ukrainian households lost their homes because of the war, including not only IDPs, but also residents of settlements that suffered extensive destruction. The World Bank estimates total housing needs in Ukraine between 2025 and 2035 to be USD 86 billion, mostly to finance repair and reconstruction works of the housing stock (estimated at USD 75.5 billion including the cost of clearing rubble at USD 5.7 billion). USD 404.6 million should go to acute housing needs and funding has also been identified for organizational measures (USD 37.5 million) and regulatory and technical processes, including the development of strategies (USD 12.5 million) to coordinate and implement reconstruction programs [4].

Citizens have already submitted over 850,000 reports of housing damage through the Diia app (the national public-services portal) totalling over 60 million sqm of losses. For comparison, in the pre-war period, an average of 9-10 million sqm of homes were completed in Ukraine each year, demonstrating the scale of challenge and need for multi-level solutions in housing policy. Preferential lending programs are unable to solve this situation and cover the housing needs. The ‘jeOselia’ program provided loans worth over UAH 28 billion, but 52% of this went to military personnel, while IDPs received only 566 pieces of loans. In 2024, within the framework of this 3% mortgage program, only 500 families were provided with housing. The situation is even more critical in the rental market as the state program for subsidizing rental housing has shown low efficiency. The majority of IDPs (90-95%) rent homes unofficially, making them vulnerable to unreliable living conditions and unjustified rental charge increases or evictions.

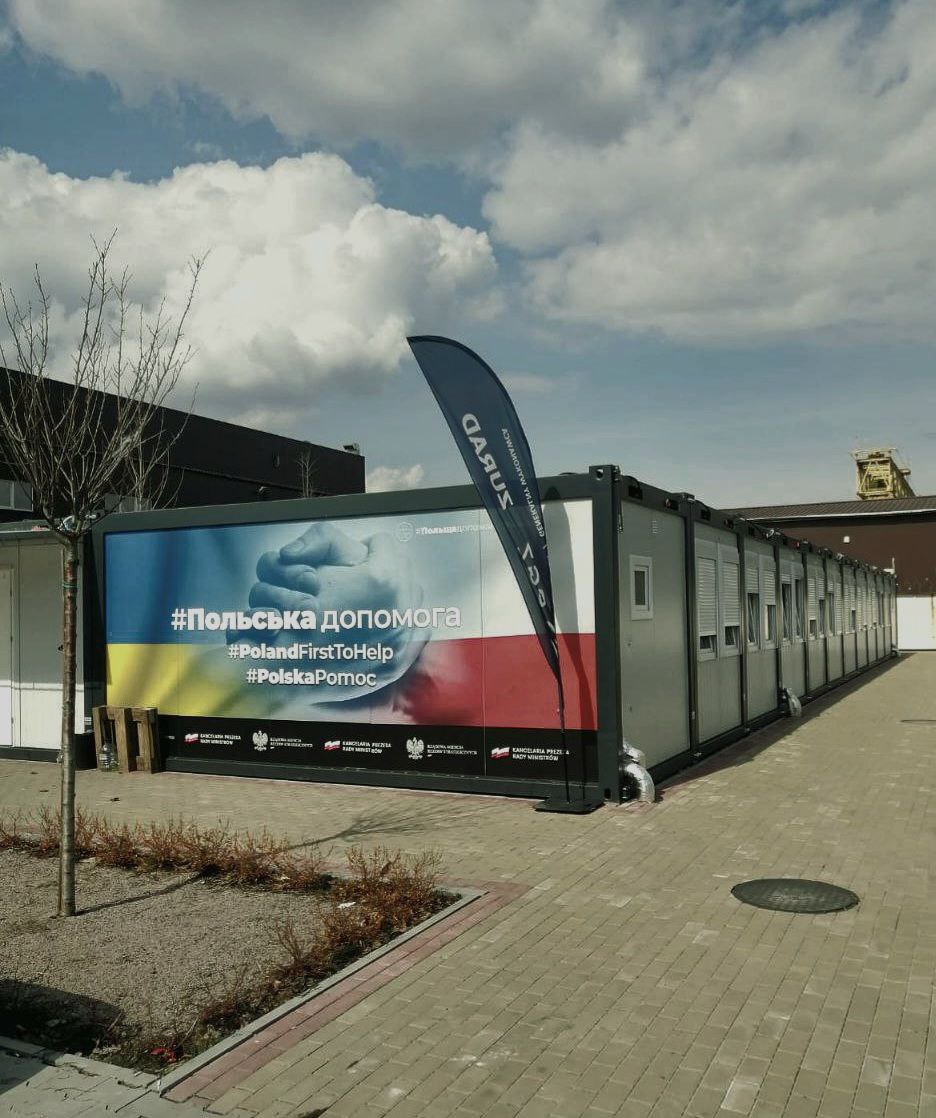
Modular settlement, Borodianka. Photo: Sergii Zapototskyi

Modular settlements are a key temporary housing for IDPs, although living conditions here cannot be considered fully comfortable. Initially, they were meant to be short-term but gradually became long-term housing for many families due to their limited finances. Today, besides the psychological difficulties and discomfort of residents, operating such facilities is also a major challenge. The maintenance of modular settlements, including payment for utilities, repairs and security, falls entirely on local budgets, an additional financial burden for communities which often do not have enough resources to sustainably finance these.

Modular settlement, Bucha. Photo: Sergii Zapototskyi

Housing policy changes

As the problem of providing housing for IDPs is systemic in nature and cannot be solved solely through financial instruments, a comprehensive review of state housing policy has become necessary, particularly the development of an affordable rental housing segment, social programs, and long-term support mechanisms for both IDPs and vulnerable categories of the population in general.

The Ukrainian Parliament is already working on several key legislative initiatives. The central one is draft law No. 12377 ‘On the Basic Principles of Housing Policy’ to replace the current Housing Code from 1983 which does not contain basic concepts for modern housing policy such as social rental housing or housing stock of communal ownership. Draft law No. 4080 is also important on the inventory of the housing stock. In parallel with drafting these laws, necessary by-laws are being prepared to regulate the practical mechanisms for implementing housing policy (creation and maintenance of housing queues, criteria for selecting recipients of state support, and the procedure of providing various forms of housing assistance). In addition, the government’s plans until 2027 include allocating EUR 650 million to the eRecovery Program, EUR 450 million to support IDPs, military personnel and the families of the deceased, creating a social housing fund and introducing a unified state online system for the long-term strategy of social integration and support for vulnerable categories of the population. All this might help resolve housing for IDPs.

Sources:

  1. Internally Displaced Persons. State Enterprise “Information and Computing Center of the Ministry of Social Policy, Family and Unity of Ukraine”: https://www.ioc.gov.ua/analytics/dashboard-vpo
  2. Housing crisis in Ukraine: how to provide IDPs with housing in 2025? International Renaissance Foundation: https://www.irf.ua/zhytlova-kryza-v-ukrayini-yak-zabezpechyty-vpo-zhytlom-u-2025-roczi/
  3. Internal Displacement Report, IOM Ukraine: https://dtm.iom.int/sites/g/files/tmzbdl1461/files/reports/IOM_UKR_GPS_Internal%20Displacement%20Report_Round%2016_UA_June%202024.pdf
  4. Rapid Assessment of Damage and Recovery Needs RDNA4, World Bank Group: https://documents1.worldbank.org/curated/en/099052925103531065/pdf/P180174-93c8e8c1-83a2-487d-aaec-a8435f9db418.pdf  
  5. Cedos, Housing and Residential Conditions in Ukraine: Survey Results, 2024: https://cedos.org.ua/wp-content/uploads/zhytlo-ta-zhytlovi-umovy-ukrayin_ok_rezultaty-opytuvannya.pdf

EECFA 2025 Summer Construction Forecast

EECFA released its 2025 Summer construction forecast on 23 June. See a sample report and place your order on eecfa.com. To get discounts, you may contact us.

Southeast European construction markets up to 2027

According to Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian research institute, total construction output in Bulgaria is anticipated to grow by 3% on average for 2025-2027 with a stronger growth in the middle of the period when the absorption of operational programmes and the implementation of the Recovery and Resilience Plan are to gain momentum. According to the sectoral breakdown, residential construction is expected to be the subsector with the weakest performance, while non-residential construction and particularly civil engineering are predicted to see stronger growth figures. Against this backdrop, the country’s economy is set to register a slower-than-expected growth in 2025 and 2026. In parallel, it is awaited to benefit from the effects from the full Schengen area membership effective from the beginning of 2025 and from the euro adoption expected on 1 January 2026.

Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s Croatian members think that Croatia’s construction as a whole continues vibrant due to the combination of continuing transitioning-economy catch-up growth and large inflows of EU money. Both are beginning to diminish, however, and that will affect all construction segments, some more strongly and more quickly than others. In building construction several sectors have seen the end or are close to seeing the end of catch-up growth. Others, particularly those that benefit most from EU finance, are still going strong. Civil engineering continues to profit greatly from EU funding, and because of the poor initial condition of Croatia’s infrastructure after independence, much catch-up construction remains to be done. Certain government policies will have a great influence on specific building and civil engineering sectors. Those policies include the housing policies embodied in Croatia’s new National Housing Policy Plan until 2030, the new tax on real estate and the country’s renewable energy permitting and electrical grid hook-up fee rules.

‘Romania’s macroeconomic outlook remains positive, but more reserved as the political instability and fiscal uncertainty have done little to improve growth opportunities’ – says Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild. At the same time, he adds, the country has the largest government deficit in the EU, which will dampen public investment capabilities. All these will make it harder to finance public works and could negatively impact civil engineering. This is doubly worrying as this subsector countered the decline in other construction segments in 2024, and thus the outlook for total construction remains negative in 2025 and 2026 in real terms. Not all is gloom and doom, however. As inflation and interest rates come down, and employment indicators remain strong, private consumption could boost demand for residential and non-residential construction.

‘In 2025 Serbia’s construction is making new gains in building construction, while civil engineering has entered a period of consolidation after the strong expansion during 2023 and 2024′ – believes Dejan Krajinović, EECFA’s Serbian researcher at Beobuild. Building construction is supported by both public and private investments, boosted by the hosting of the EXPO 2027 in Belgrade. Non-residential construction is the main beneficiary of this event, particularly commercial, office and hotel segments, while residential construction is also keeping historically high volumes. Some delays are seen in civil engineering, but the overall performance is still strong with a long list of planned projects in all major subsegments. Domestic demand is still relatively strong, but economic growth and the level of investments are being muffled this year by uncertainties in the global markets, particularly the weak EU economy, international trade issues and the ongoing wars in Ukraine and the Middle East.

‘Total construction output in Slovenia is expected to decrease from the historic high of EUR 5,5 billion reached in 2023. In both 2024 and 2025, it could contract but remain above EUR 5 billion annually’ – as per the opinion of Dr. Aleš Pustovrh at Bogatin, EECFA’s Slovenian member institute. He predicts the sector to return to growth in 2026 and 2027, mostly on the back of a healthy growth in residential construction buoyed by decreasing mortgage rates. On the other hand, civil engineering is prognosticated to shrink significantly in 2024 and 2025 due to some large projects nearing completion, like the new railroad connecting Port Koper. Both non-residential and civil engineering depend to a large degree on public financing that was widely available in the post-Covid period but will become much less available in 2025-2027. Especially if the overall economic activity continues to slow down. This deceleration and more foreign labourers have also caused lower construction cost growth, but other challenges persist such as the additional bureaucratic burdens (changed permitting process, increase in tax, ongoing discussion on changes to short-term rental legislation, among others) and many external risks in the global economic and political environment. 

Eastern European construction markets up to 2027

‘In the forecast horizon, the construction sector of Russia will be under pressure from a range of macroeconomic factors, the main one being the high key rate, which will negatively affect the pace and volume of construction projects’ – according to Andrey Vakulenko at MACON, EECFA’s Russian research institute. The tight monetary policy and the reduced availability of mortgages will likely slow down housing construction, on the one hand. On the other, the high cost of project financing, the general cooling of the economy as well as reduced consumption and business activity will likely shrink the volume of investment in non-residential construction. However, these trends can partly be offset by high volumes of government financing of priority infrastructure and energy projects, which can support civil engineering and ensure near-zero growth in total construction market in 2025-2027.

Prof. Ali Türel, EECFA’s Turkish researcher says that Türkiye has been trying to control high inflation by raising the base rate and managing exchange rate increases through market instruments by the Central Bank and maintaining wage growth at zero or negative rates. This created financing difficulties for industries and businesses, reduced demand for basic consumer goods, and led to affordability problems for mortgage credits. Big declines in building starts and completions in Q1 2025 may also be related to these measures. Yet, the Central Bank’s inflation target for 2025 remains high at 24%. Positive real changes in housing prices relative to building construction costs encourage house building, while their negative real change compared to inflation may be the leading factor in the increase of home sales through equity financing when mortgage credits are not affordable for most households. Rebuilding the quake-damaged 870 thousand units requires about EUR 100 billion and these expenditures have been the primary factor of the large national deficits in recent years.

‘This year, in spite of the continuing war and the economic instability in the country, Ukraine’s construction industry shows signs of recovery and growth on the back of successful programs financing both the construction of new facilities and the reconstruction and restoration of infrastructure in eastern and southern regions’ – according to Prof. Sergii Zapototskyi at Uvecon, EECFA Ukraine. The World Bank estimates that reconstruction would require USD 486 billion. On the negative side for the sector are bureaucratic barriers in the urban planning legislation, shortage of workers caused by mobilization, shortage and high cost of building materials, and logistical difficulties. On the positive side for the sector is demand for housing and the need to restore damaged infrastructure. The near-term future of the industry depends on the level of security, the effectiveness of restoration programs and the volume of international investments.