Written by Prof. Sergii Zapototskyi – UVECON, EECFA Ukraine
“Between 2021 and 2026, the weighted average price of housing in Kyiv city’s secondary market rose by 11.7% compared to 43.7% in Kyiv oblast. At the same time, new housing completions in the capital city remain well below pre-war levels, while safety, autonomy, and affordability are becoming decisive drivers of demand. Does this signal a gradual shift in housing development towards the suburbs and is the metropolitan region ready for the new challenges of post-war recovery?” These are the questions that Prof. Sergii Zapototskyi, EECFA’s Ukrainian researcher at Uvecon is trying to answer.
The residential property market of Kyiv metropolitan region in 2021-2026 became an indicator of how the war reshapes the economic and spatial organisation of a large urban agglomeration. This is not merely about fluctuations in the price per square metre. Migration, security risks and disrupted infrastructure connections are changing perceptions of what makes housing attractive, along with the balance of supply and demand between the capital city and its surrounding area.
GISPro Uvecon secondary market data for September 2021 and September 2026
As per GISPro, Uvecon’s geoportal, in Kyiv city the weighted average price of secondary housing grew from USD 1,871.02/m² in September 2021 to USD 2,090.77/m² in September 2026 (+11.7%); the median rose from USD 1,554.05 to USD 1,773.47/m² (+14.1%). The number of listings in the sample rose from 28,745 to 34,967 (+21.6%), broadly reflecting the volume of recorded supply rather than the number of transactions. With cumulative consumer price inflation of around 78.4%, the nominal rise in US dollars does not imply a corresponding rise in purchasing power or real value. A figure of -37.5% can only be obtained by hypothetically deflating the dollar-denominated price using Ukraine’s consumer price index. A rigorous comparison of real US dollar prices requires a different deflator, while a comparison in Hryvnias must account for the exchange rates on the relevant dates [Sources 1, 2].

Kyiv oblast (region) had a different trajectory. The weighted average price rose from USD 901.64 to USD 1,295.64/m² (+43.7%), a markedly faster rate than in Kyiv city, indicating a gradual convergence of price levels. However, attributing it solely to buyers “fleeing” Kyiv would be an oversimplification. The oblast-wide indicator combines the inner suburban belt and more remote districts, different building types and properties with varying liquidity. The question is the extent to which the price advantage of suburbs offsets the time cost of daily commuting, dependence on jobs in the capital city and the uneven access to social services. In this respect, Bucha, Irpin, Vyshneve, Brovary, and Boryspil are not simply alternatives to the capital city, but parts of a shared housing market in which locations compete through a combination of price, accessibility, and environmental quality [Sources 1, 3].
In September 2026, indicative secondary-market prices ranged from USD 3,217/m² in Pecherskyi District to USD 1,117/m² in Desnianskyi District, a gap of almost 2.9 times. Higher values were registered in Shevchenkivskyi (USD 2,330/m²) and Holosiivskyi (USD 2,090/m²) districts as well. This differentiation reflects centrality, building quality, transport accessibility and the concentration of services. Yet, district averages conceal considerable heterogeneity in housing stock; assessing the role of shelters, autonomous systems and security would require analysis at the level of individual buildings or micro-locations [Source 1].
Territorial shifts are evident in new housing construction statistics
In Kyiv city, housing completions fell from roughly 1.96 million m² in 2021 to 0.91 million m² in 2022. The subsequent recovery to 1.41 million m² in 2024 proved fragile: 1.19 million m² was completed in 2025, 39% below the pre-war level. Kyiv oblast, by contrast, nearly returned to its 2021 figure: 1.99 million m² over 2.04 million m². Together, the city and the oblast accounted for around 3.18 million m², or one-third of all housing completed in Ukraine in 2025.
Thus, construction activity has not disappeared from the metropolitan region, but its geography has become relatively more oriented towards the oblast. This does not automatically mean that suburban construction can fully replace supply in the capital city: new housing requires transport links, schools, healthcare facilities and utility infrastructure. Also, accurate comparisons across years must take into account changes in the statistical coverage of certain building types [Sources 4–6].
War-related damage constrains effective housing supply and increases reconstruction costs
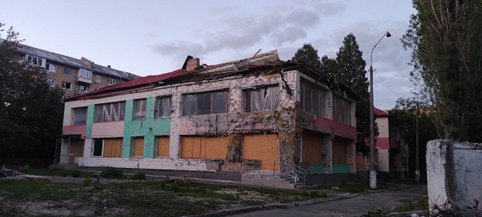
Direct damage to Ukraine’s housing was USD 61.1 billion at end 2025 (source: RDNA5), while recovery needs reached USD 89.8 billion [Source 7]. As per data published in October this year, 4,480 apartment buildings in Kyiv have been damaged since the start of the invasion. The Kyiv Oblast Military Administration reported that by early 2025, 1,909 apartment buildings and 25,944 private houses in the oblast had been damaged or destroyed [Sources 8,9]. Yet these figures refer to different dates and geographical scales and thus should not be added together as a single current total.

The war has also changed the criteria buyers use to assess housing
Whereas location, layout, and transport were previously the main considerations, buyers now also evaluate the ability of the building to maintain essential functions during crises. In a nationwide OLX survey conducted in 2026, 68% of prospective buyers considered backup electricity supply important, 68% cited autonomous heating, and 60% valued an on-site shelter [Source 10].
Affordability adds an important social dimension to price
For a hypothetical 50 m² apartment, the estimated price based on Uvecon’s weighted averages was about USD 93,600 in 2021 and USD 104,500 in 2026. The ratio of this price to the average annual salary was estimated at 10.1 and 7.3 years, respectively [Sources 1, 5]. At first glance, this suggests an improvement in formal affordability. But the average salary does not represent the incomes of all households, and the calculation excludes living costs, the need to save for a down payment and actual mortgage terms. It is therefore important to distinguish statistical affordability from an individual household’s ability to purchase a home.
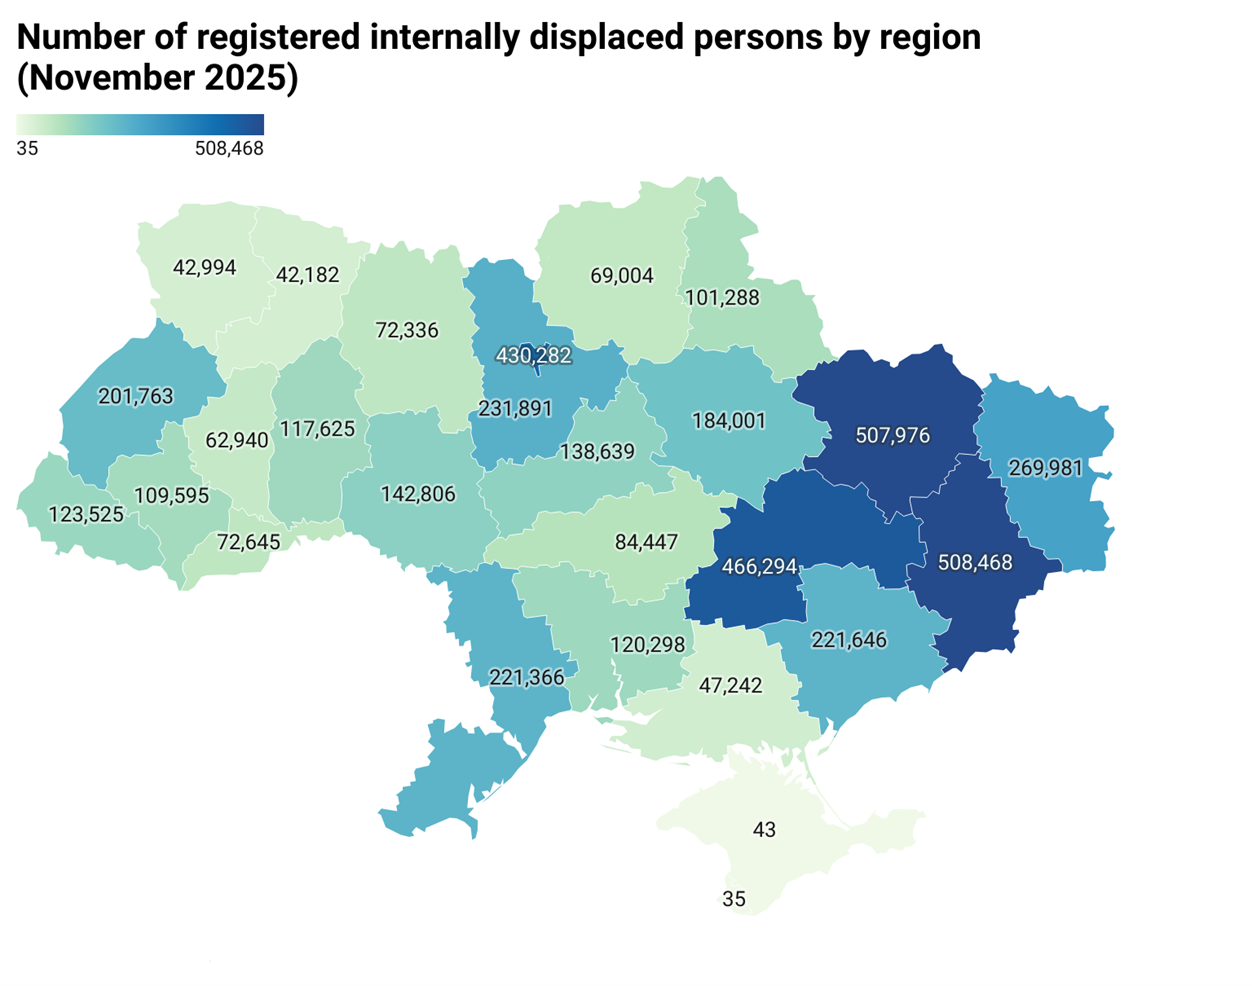
After the active phase of war ends, the return of Internally Displaced Persons may increase demand, while the repair of damaged buildings and constructing new housing will take time. Under this scenario, the most likely challenge is not a general shortage of residential floor space, but a structural shortage of affordable, safe and good-quality homes. Suburban areas may partly ease this imbalance, but only if transport, social services and infrastructure networks are developed in a coordinated manner.
Conclusions
Between 2021 and 2026, the Kyiv region’s housing market was characterised by moderate nominal price growth in the capital city and much faster growth in Kyiv oblast, alongside substantial disparities within the city. Housing completions in Kyiv remained below pre-war levels, while the oblast strengthened its role in regional supply.
War-related damage and growing demand for safety and autonomy are changing the qualitative structure of housing demand. A major challenge for post-war recovery may be a shortage specifically of affordable and resilient housing, requiring coordinated housing and infrastructure policies across the entire metropolitan area.
Forecast for the residential market of Ukraine will be available on 8 December 2026 in the winter EECFA report. To get a sample report or discount on the new report, please contact us.
Sources
1. UVECON Geoportal / GISPro. Secondary-market apartment price indicators, September 2021 and 2026. https://gisuvecon.com/main/geoportal/
2. State Statistics Service of Ukraine. Consumer price indices. https://stat.gov.ua/uk
3. LUN. Statistics on Kyiv’s primary housing market. https://lun.ua/stat/primary/kyiv
4. Main Department of Statistics in Kyiv. https://www.kyiv.ukrstat.gov.ua/
5. State Statistics Service of Ukraine. Housing construction and wage statistics. https://stat.gov.ua/uk
6. Main Department of Statistics in Kyiv Oblast. http://www.kyivobl.ukrstat.gov.ua/
7. World Bank et al. Ukraine Fifth Rapid Damage and Needs Assessment (RDNA5). 2026. https://ukraine.un.org/sites/default/files/2026-02/P514499-22f93f3a-4278-42bc-b907-db9553d12069.pdf
8. Suspilne Kyiv. Klitschko discusses the restoration of war-damaged buildings. 16 October 2026. https://suspilne.media/kyiv/1429635-klicko-rozpoviv-skilki-poskodzenih-vijnou-budinkiv-uze-vidnovili-v-kievi/
9. Kyiv Oblast Military Administration. 2024 results: reconstruction. 1 January 2025. https://koda.gov.ua/pidsumky-2024-roku-vidbudova-na-kyyivshhyni-vzhe-vidnovleno-203-tys-obyektiv/
10. OLX. What matters to Ukrainians when choosing housing. 5 October 2026. https://blog.olx.ua/37332/shho-vazhlivo-ukraincjam-pri-vibori-zhitla-golovni-kriterii-kupivli-ta-orendi-u-2026-roci/