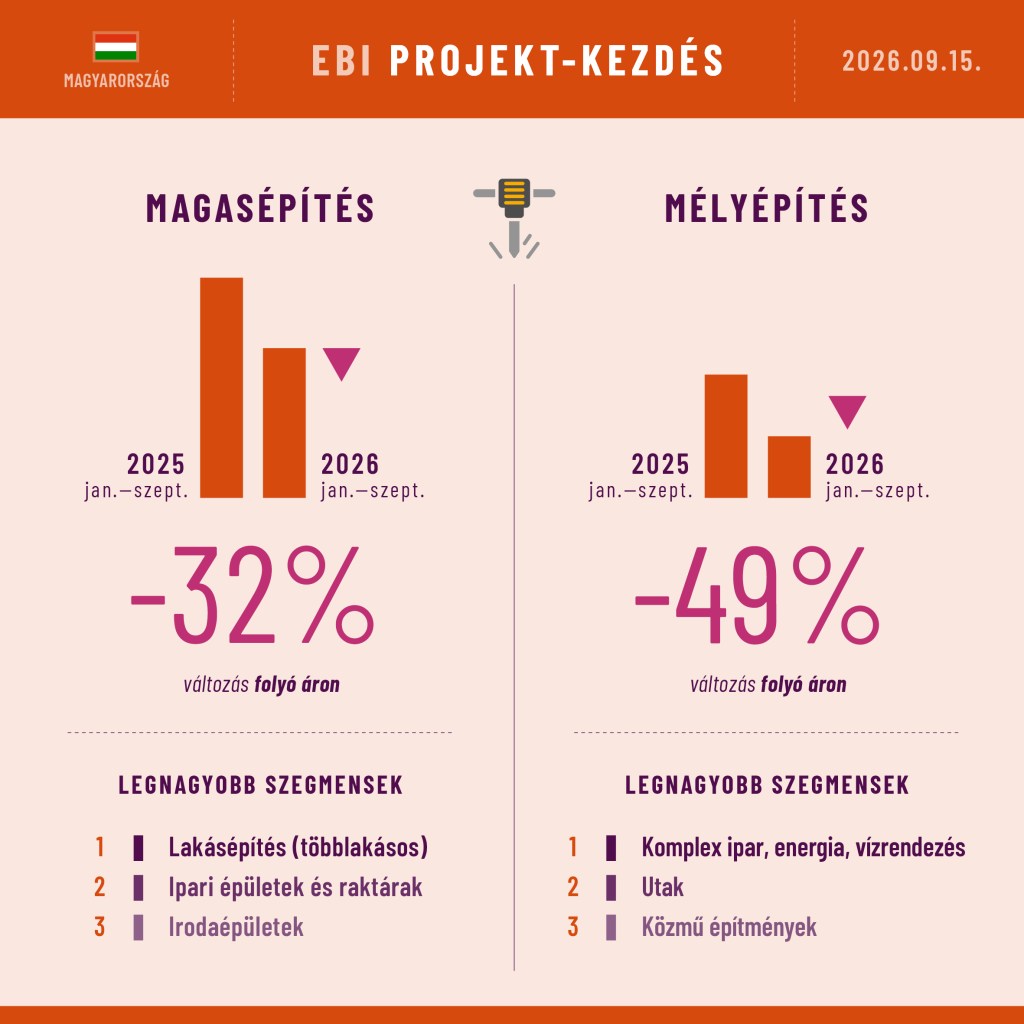
Valószínűleg a harmadik negyedév sem fogja elhozni a pozitív fordulatot a magasépítés Projekt-Kezdésében. A társasházi lakás részpiacon egyelőre lényegesen kisebb értékben indultak kivitelezések az idei harmadik negyedévben, mint tavaly.
A nagy visszaesés ellenére azonban ez a negyedév sem katasztrofálisan gyenge, és olyan nagy projektek indultak Budapesten mint a Greenway Apartments (Living) a Marina City A4 (Cordia) vagy az Amphora Garden (Biggeorge). A nem-lakás magasépítés Projekt-Kezdése viszont továbbra is extra-alacsony.
Az idei harmadik negyedévben elkezdődött a Tiszaújvárosi Gázerőmű két blokkjának kivitelezése. Ennek ellenére a mélyépítés részpiacon is jelentős a visszaesés. Ez a magas bázis miatt van, mivel tavaly szeptemberben kezdődött el az M1 autópálya-bővítés.
Átneveztük a mutatószámainkat a könnyebb érthetőség kedvéért; mostantól Projekt-Kezdés/Befejezés néven utalunk a megkezdett/befejezett kivitelezési munkák összértékére. A vizualizációban is a korábbi Aktivitás-Kezdés/Befejezés helyett a Projekt-Kezdés/Befejezés kifejezésekre térünk át.
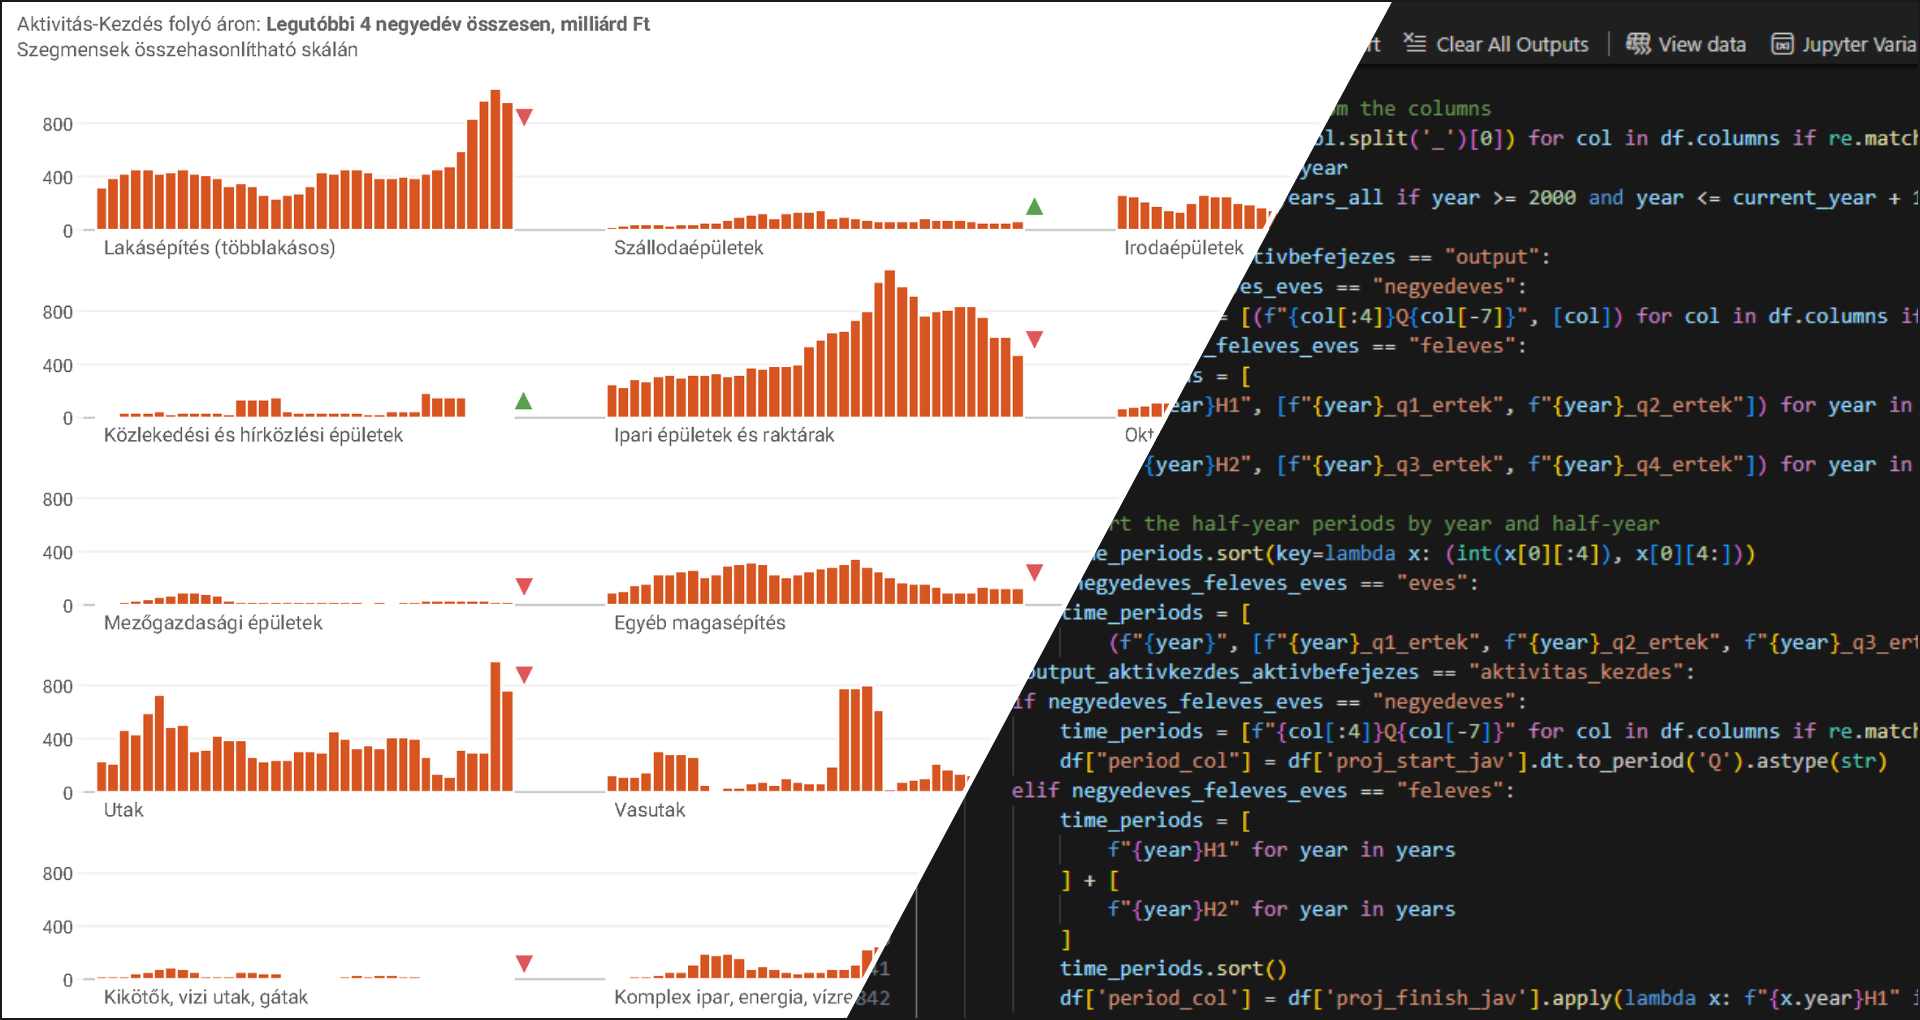
A poszter a két nagy építési részpiac Projekt-Kezdés indikátorának időszak/időszak változását mutatja, valamint a szegmenseket amelyekben a legnagyobb értékben indultak kivitelezések. Ezt a posztert minden hónapban kitesszük ide a blogunkra. A teljes építési piacot részletesen bemutató EBI Építésaktivitási Adatvizualizációt (összesen 18 szegmens adataival) is havonta frissítjük, és negyedévente az EBI Építésaktivitási Jelentésben is elmondjuk, hogy mit látunk a piacon. Ha érdeklik a részletek akkor a contact oldalon írjon nekünk.
It is unlikely that the third quarter will bring a positive turnaround in Project-Start on the building construction submarket. The value of multi-unit residential projects launched in the third quarter of this year was significantly lower than in the same period last year.
Despite this sharp decline, however, the quarter was not disastrously weak; and some major projects were launched in Budapest such as Greenway Apartments (Living), Marina City A4 (Cordia), and Amphora Garden (Biggeorge). Conversely, Project-Start in the non-residential submarket has remained extremely low.
Construction on two units of the gas power plant in Tiszaújváros began in the third quarter of this year. Nevertheless, there is a significant drop in the civil engineering submarket as well. This is due to the high base as the expansion of the M1 motorway began last September.
We have renamed our indicators for the sake of easier understanding; from now on we refer to the total value of started/completed construction works as Project-Start/Completion. In the visualization, we are also switching to the terms of Project-Start/Completion instead of the previous Activity-Start/Completion.
The poster (above) shows the period/period changes of the Project-Start indicator in the 2 main submarkets and the segments with the largest value of started works. This poster is published every month here in the blog. The EBI Construction Activity Data visualization with the details on the whole construction market (with altogether 18 segments) is also updated monthly and the EBI Construction Activity Report, summarizing what’s happening in the market, is published in each quarter. If your interest in construction markets is deeper, please contact us for the details.
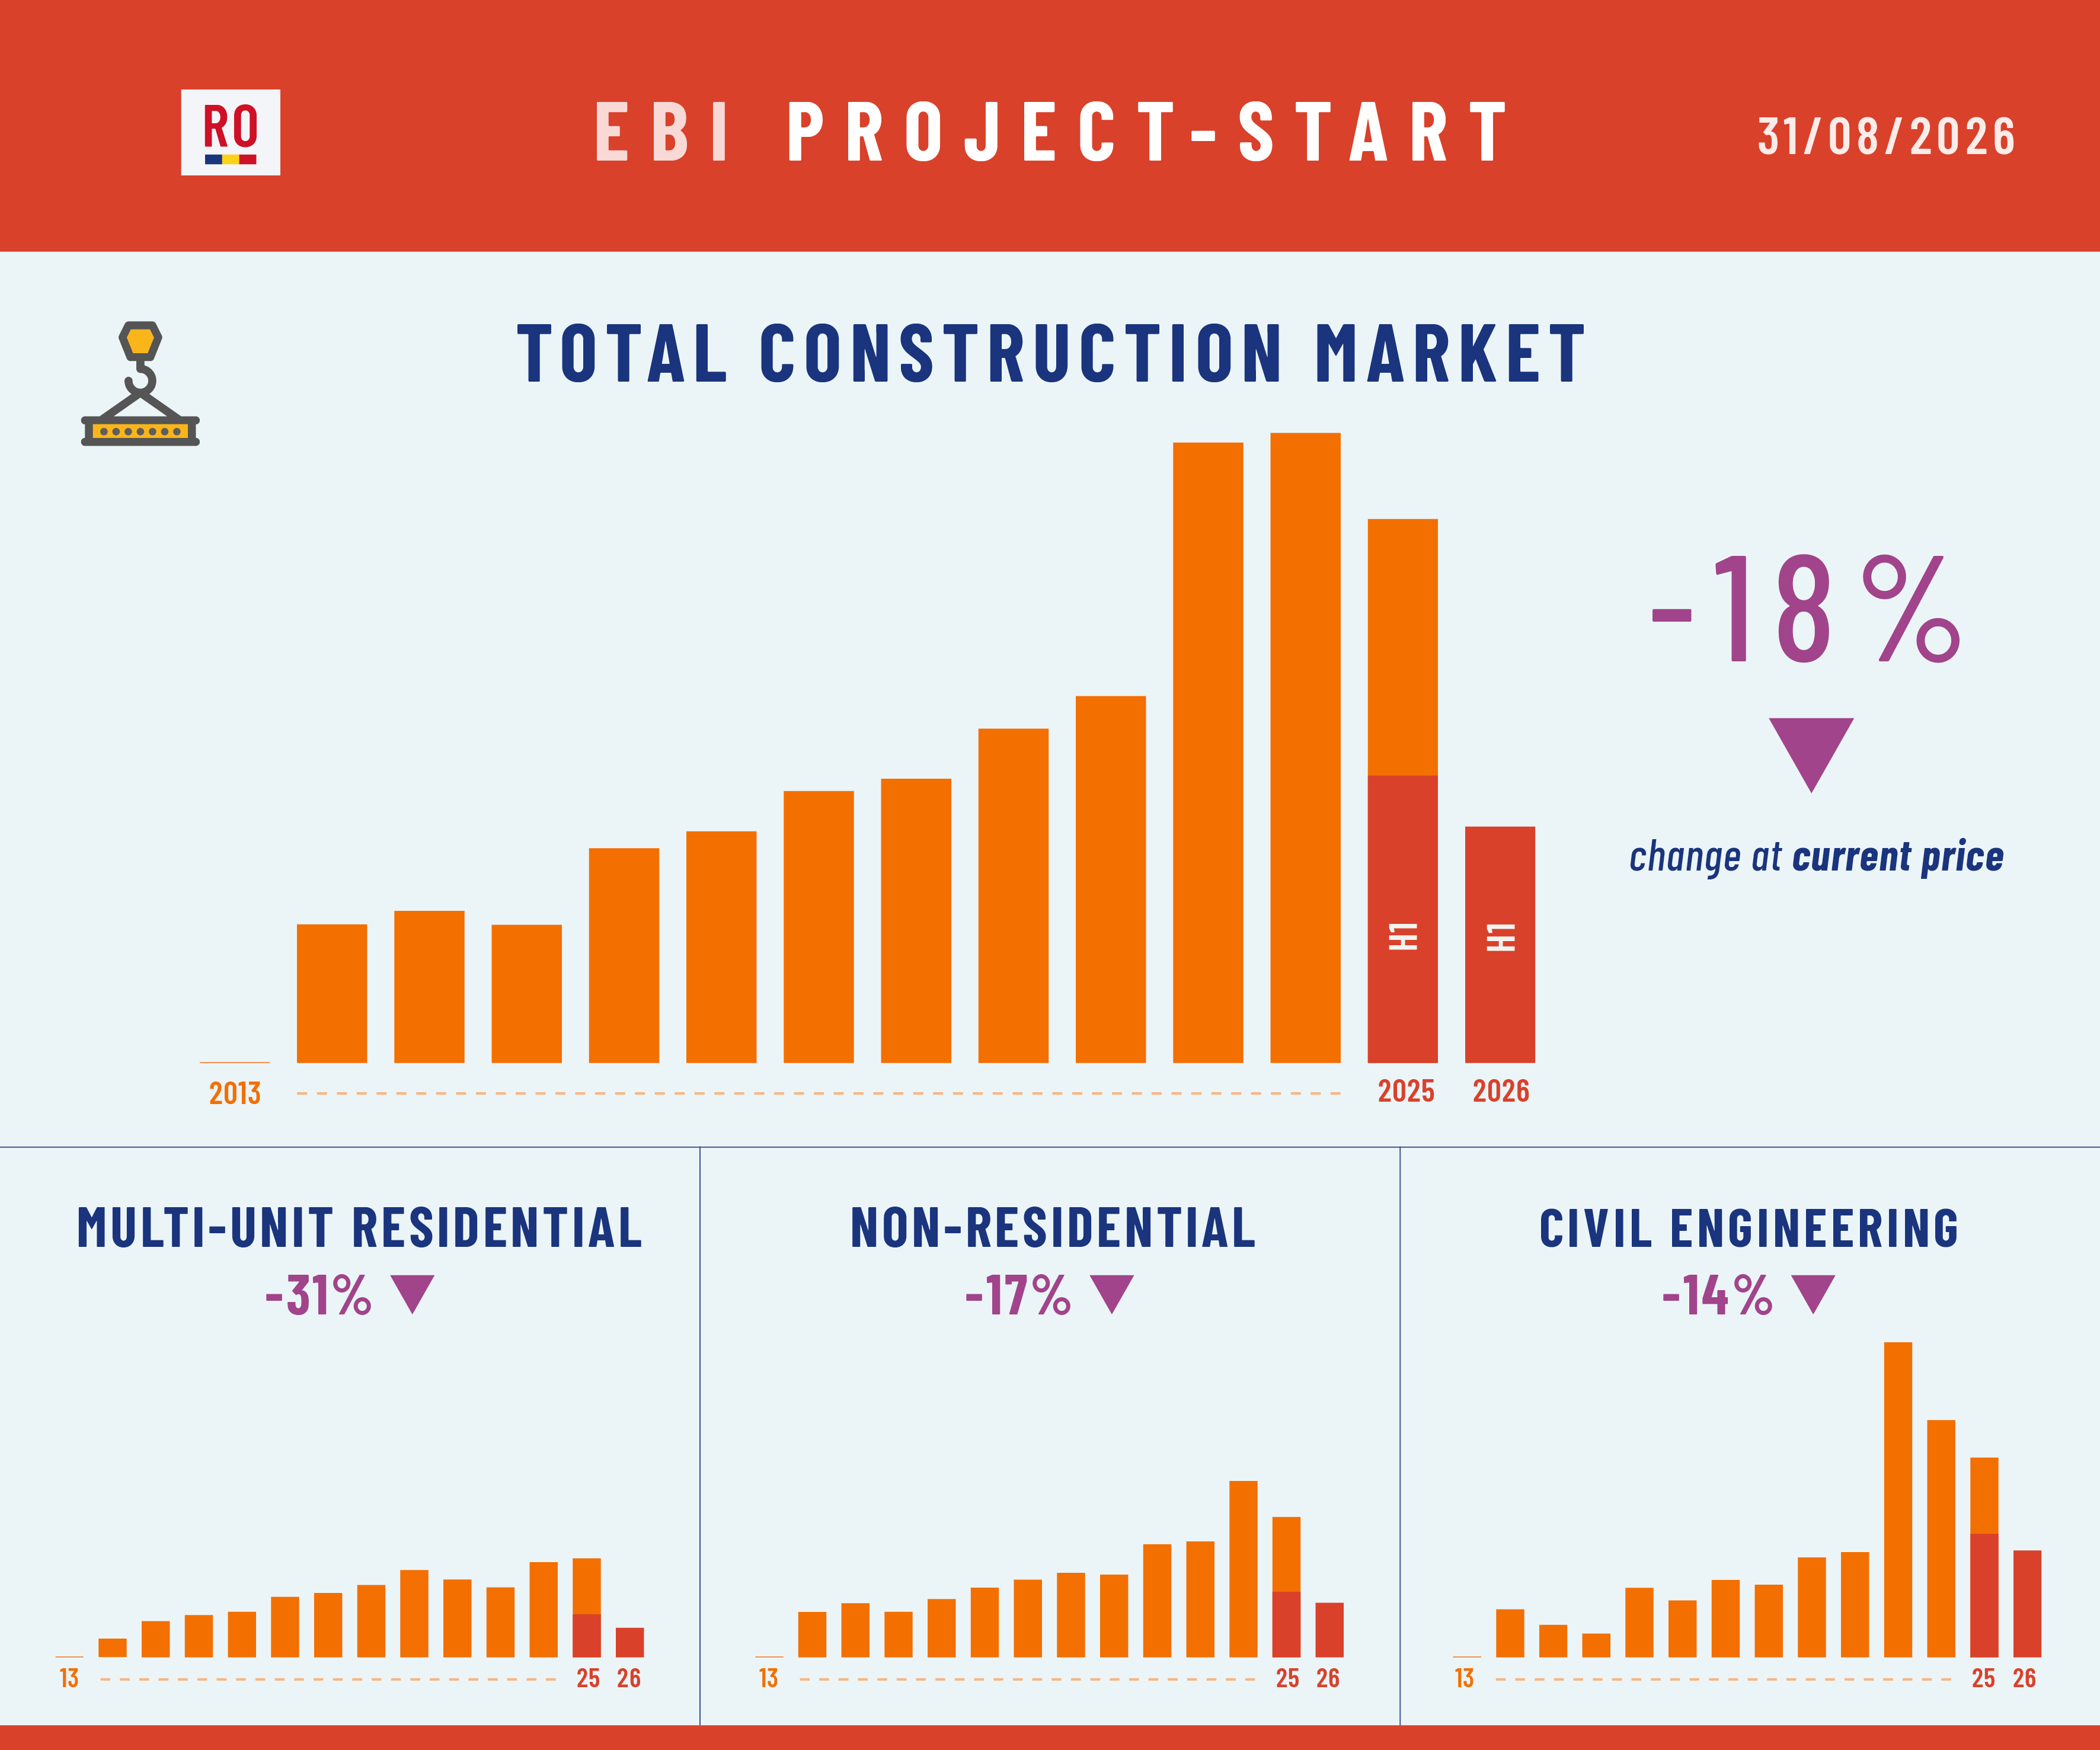
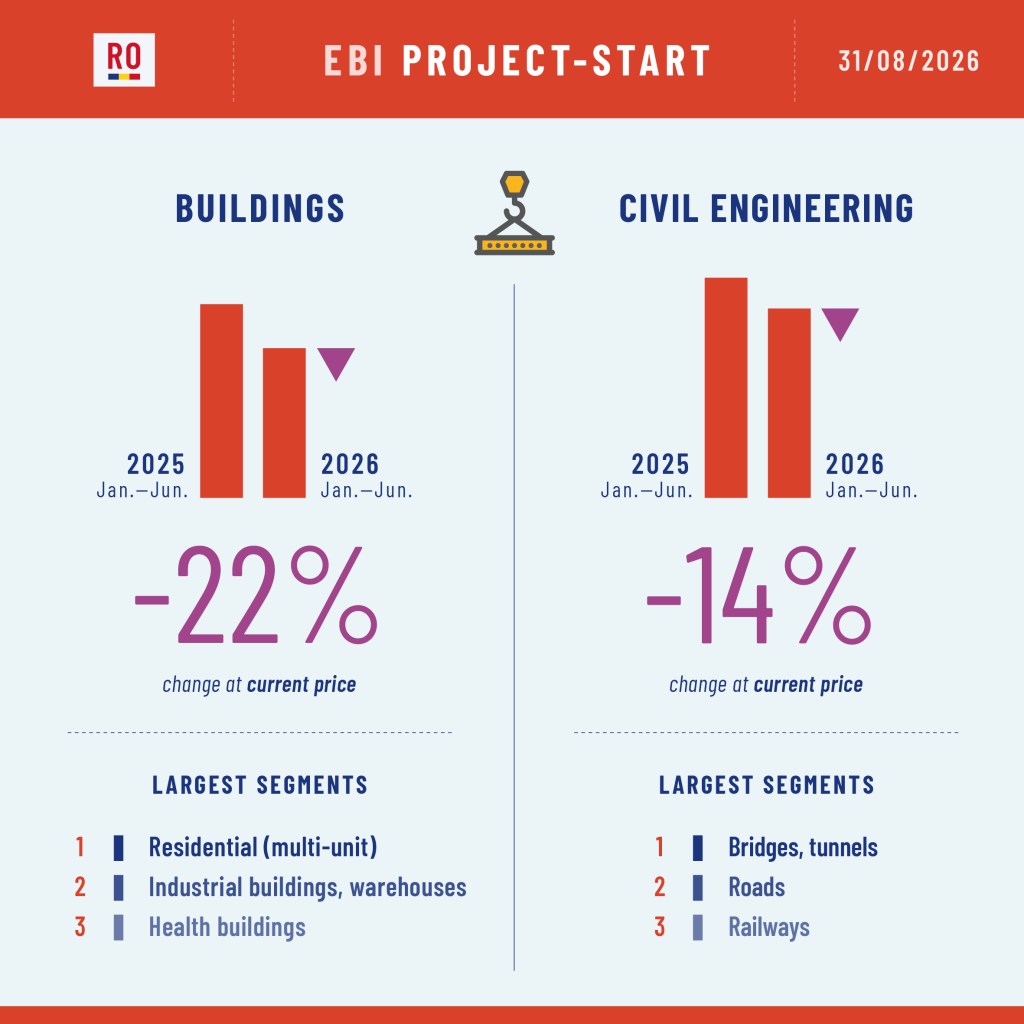
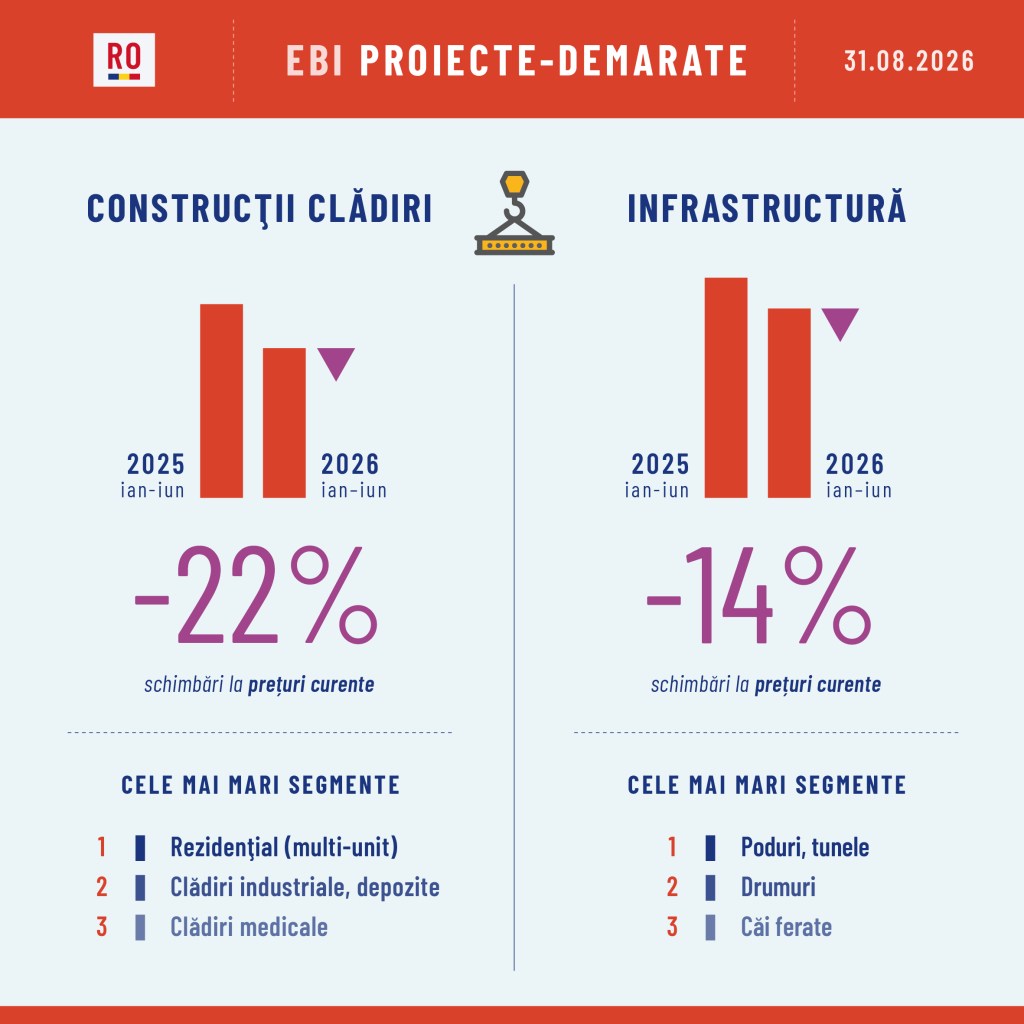
The value of newly started construction projects in Romania was much lower in the first half of 2026, according to the latest EBI Construction Activity Report Romania, with Project-Start in decline across almost every submarket. “Q1 was relatively strong, but not enough to change the overall downward trend. A combination of economic slowdown, persistent inflation, elevated interest rates, and reduced public spending continues to constrain the market” – says Dr. Sebastian Sipos-Gug.
The total value of commenced multi-unit residential projects experienced the largest drop (-31% compared to H1 2025) as developers face more difficult financing terms and cooling market demand. Home prices are rising more slowly than inflation or construction costs, which also makes residential projects less appealing for speculative development. The ransomware attack on the land registry database also hindered new construction, since it froze property transactions, mortgage contracts, land surveys and construction authorizations for weeks. As the administration will have to handle the backlog created during the shutdown in addition to new requests, the situation is unlikely to improve for the remainder of the year.
Project-Start also fell in case of non-residential construction, though at a more moderate pace (-17% year-on-year). Performance within the submarket was uneven: publicly funded buildings, particularly in healthcare and education, were behind much of the decline as government investment comes under strain from austerity measures and the focus on ongoing NRRP-funded projects. The private sector is showing signs of strong resilience, as evidenced by the detailed breakdown in the report (for instance, the remodeling of mall Palas Iasi started in Q2 2026, at an estimated value of EUR 80mln), and could help the submarket weather this period of poor performance.
The infrastructure submarket fared the best of all three, but it still declined significantly (-14% year-on-year) since new projects took a backseat in favor of completing existing works, with the administration focused on increasing absorption before the August 2026 NRRP deadline. The ongoing government crisis has further complicated both the launch of new projects and the financing of those already underway, but a ramp up of the 2021-2027 EU funding programs could help sustain the submarket by the end of the year. For instance, in H1 2026 construction started on the renovation of one of the oldest railroad connections in the country: Bucharest North – Jilava – Giurgiu North – Giurgiu North Border (55 km), with EUR 423mln co-funded from the CEF 2021-2027 budget.
EBI Construction Activity Report Romania analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). We have renamed our indicators for the sake of easier understanding; from now on we refer to the total value of started/completed construction works as Project-Start/Completion.To get the report, please contact us.
There was no construction start indicator in Romania, so we have created an estimation for it.
This poster is a summary of our monthly findings. It shows how the total value of started construction works have changed over the same period last year. Besides, it presents which segments have the biggest start value in the current year. We call this indicator Project-Start. And they are computed every month for 18 construction segments by aggregating data of construction projects. The projects are from the iBuild database and ELTINGA and Buildecon found the way of creating indicators out of them.
If you need short-term foresight, you will like it.
Brief comment from Janos Gaspar, head of Buildecon:
Project-Start in the multi-unit housing submarket was 30% lower in the first half of this year than last year. The non-residential submarket as a whole also declined, but several segments within it are performing quite well. The total value of started construction works increased in all of the hotel, office, retail and industrial segments compared to the first half of last year. Project-Start in civil engineering is still high despite the drop. In the first half of the year, 14 projects with a value of over EUR 50 million per each started.
We have renamed our indicators for the sake of easier understanding; from now on we refer to the total value of started/completed construction works as Project-Start/Completion. In the EBI Construction Activity Visualization and Report we are also switching to the terms of Project-Start/Completion instead of the previously used Activity-Start/Completion.
Every month this poster will be available here on our blog. If your interest is deeper, we have the EBI data visualization (with indicators for all the 18 segments of the construction market), updated monthly and we have the EBI Construction Activity Report Romania (with data and explanations), published quarterly in English and in Romanian. All these are packed into a yearly subscription. For the specifics, please contact us.
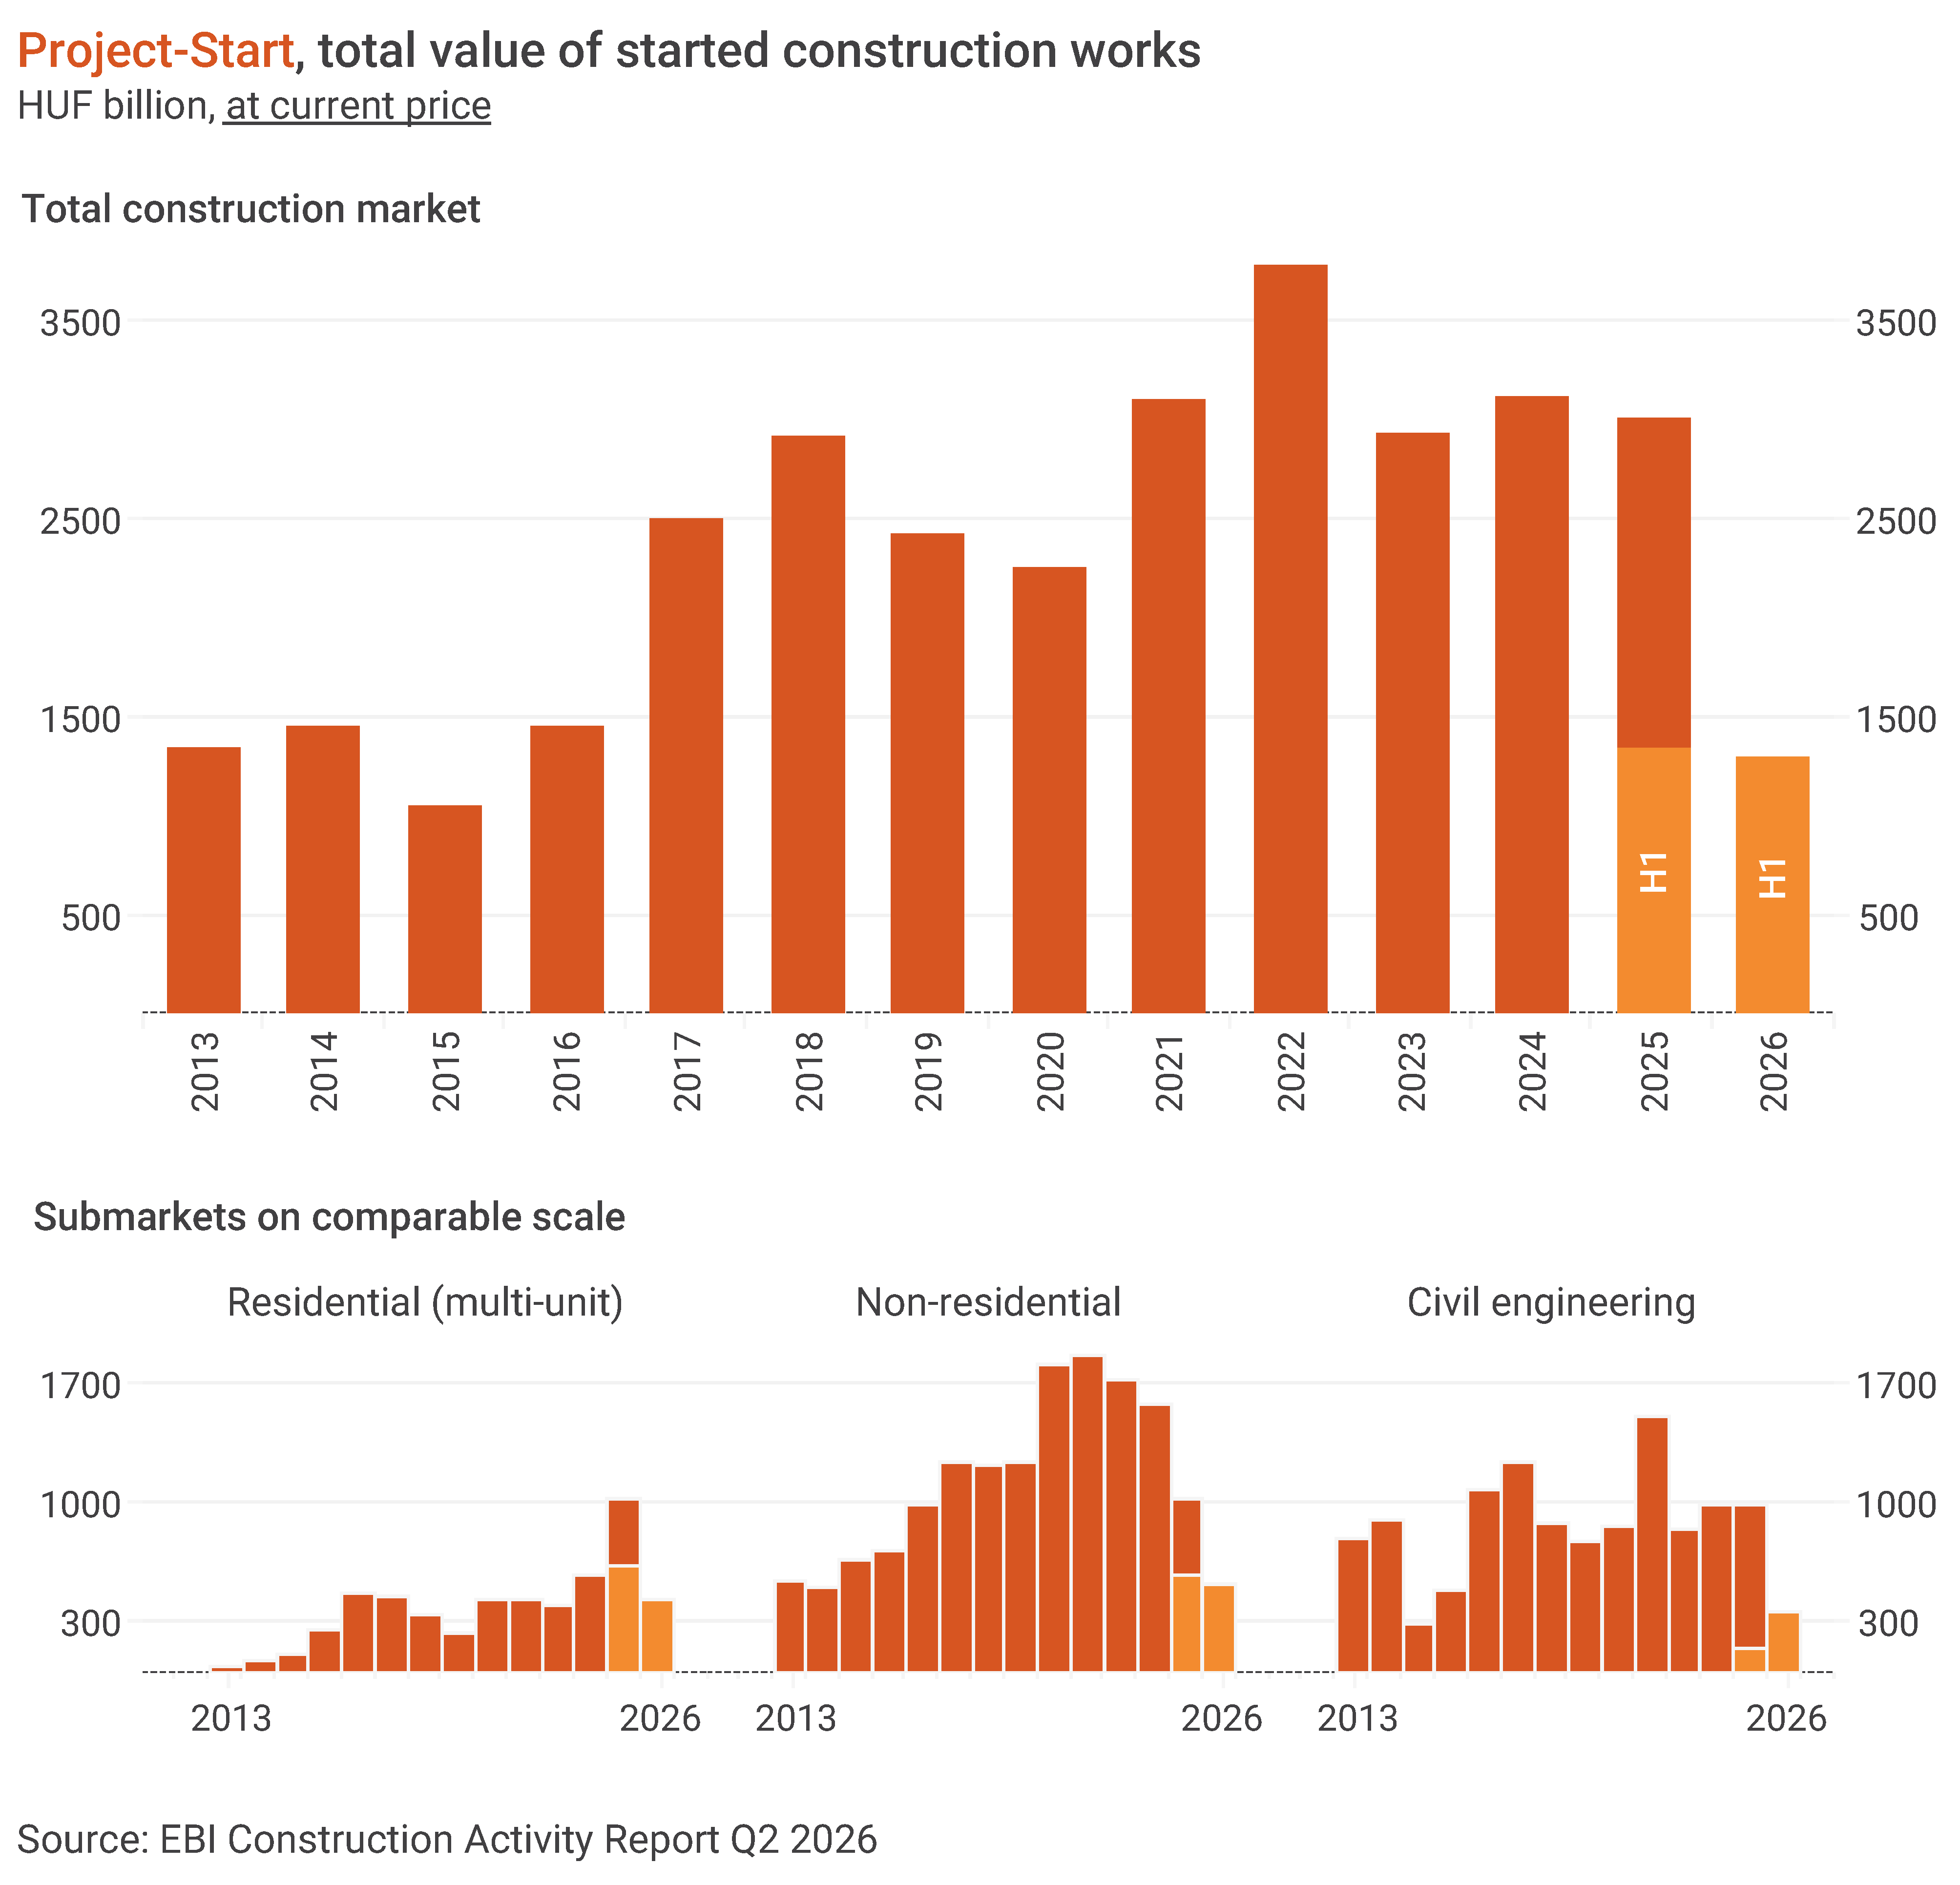
Although Q1 data suggested that early 2026 started well for construction, in Q2 the sector saw a way more moderate investment mood: the level of Project-Start shrank to roughly half of the Q1 level. The latest EBI Construction Activity Report found that projects worth less than HUF 470 billion started – the third lowest value since 2021. The value of construction projects started in Q2 was about 41% lower than the average three-month value between 2021 and 2026. Thanks to the outstanding Q1 figures due to Paks 2 andthe high number of multi-unit residential project starts, however, the overall level of Project-Start in H1 is still not drastically low: the drop is just over 3% like-for-like. Yet, compared to the first six months of 2021-2024, the decline is between 17% and 45%.
EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database).To order the report, please contact us.
We have renamed our indicators for the sake of easier understanding; from now on we refer to the total value of started/completed construction works as Project-Start/Completion.
Building construction: Q2 brought much lower Project-Start than Q1
As per the latest EBI Construction Activity Report, the value of projects entering construction in Q2 did not reach HUF 350 billion, making it the second worst quarter since 2021. Looking at the first half of the year, the Project-Start of less than HUF 1,000 billion at current price has been the lowest level since 2021, falling 10%-27% short of the figures of the first 6 months of the past 6 years. Although Q2 brought lower Project-Start for both multi-unit residential and non-residential buildings, the latter did not post such a radical drop. Overall, non-residential projects worth slightly more than HUF 500 billion entered construction during H1 2026 – the lowest level in the past 6 years and 10%-52% lower than in the same period of previous years.
Among the biggest non-residential projects launched in Q2 2026 was the construction of Airport Service Centre Office Building, Phase 2 of Petőfi Theatre in Veszprém, and several logistics ones such as Phase2 of CTP logistics park in Érd, the next phase of the Weerts Logistics Centre project, as well as the final works of Phase 2 of Kecskemét Campus.
Civil engineering: projects launched at a much lower value in Q2
Owing to the high Project-Start due to the Paks 2 project in Q1 2026, in Q2 the value of Project-Start slightly exceeded HUF 120 billion. Started projects were primarily non-road and non-railway projects, with the largest being the combined cycle gas turbine power plant in Visonta and the hybrid geothermal power plant in Zsana. Project-Start in the road and railway segments continued to be at a minimal level where the biggest project was the Baja southern bypass and junction.
Central Transdanubia overtaking Budapest
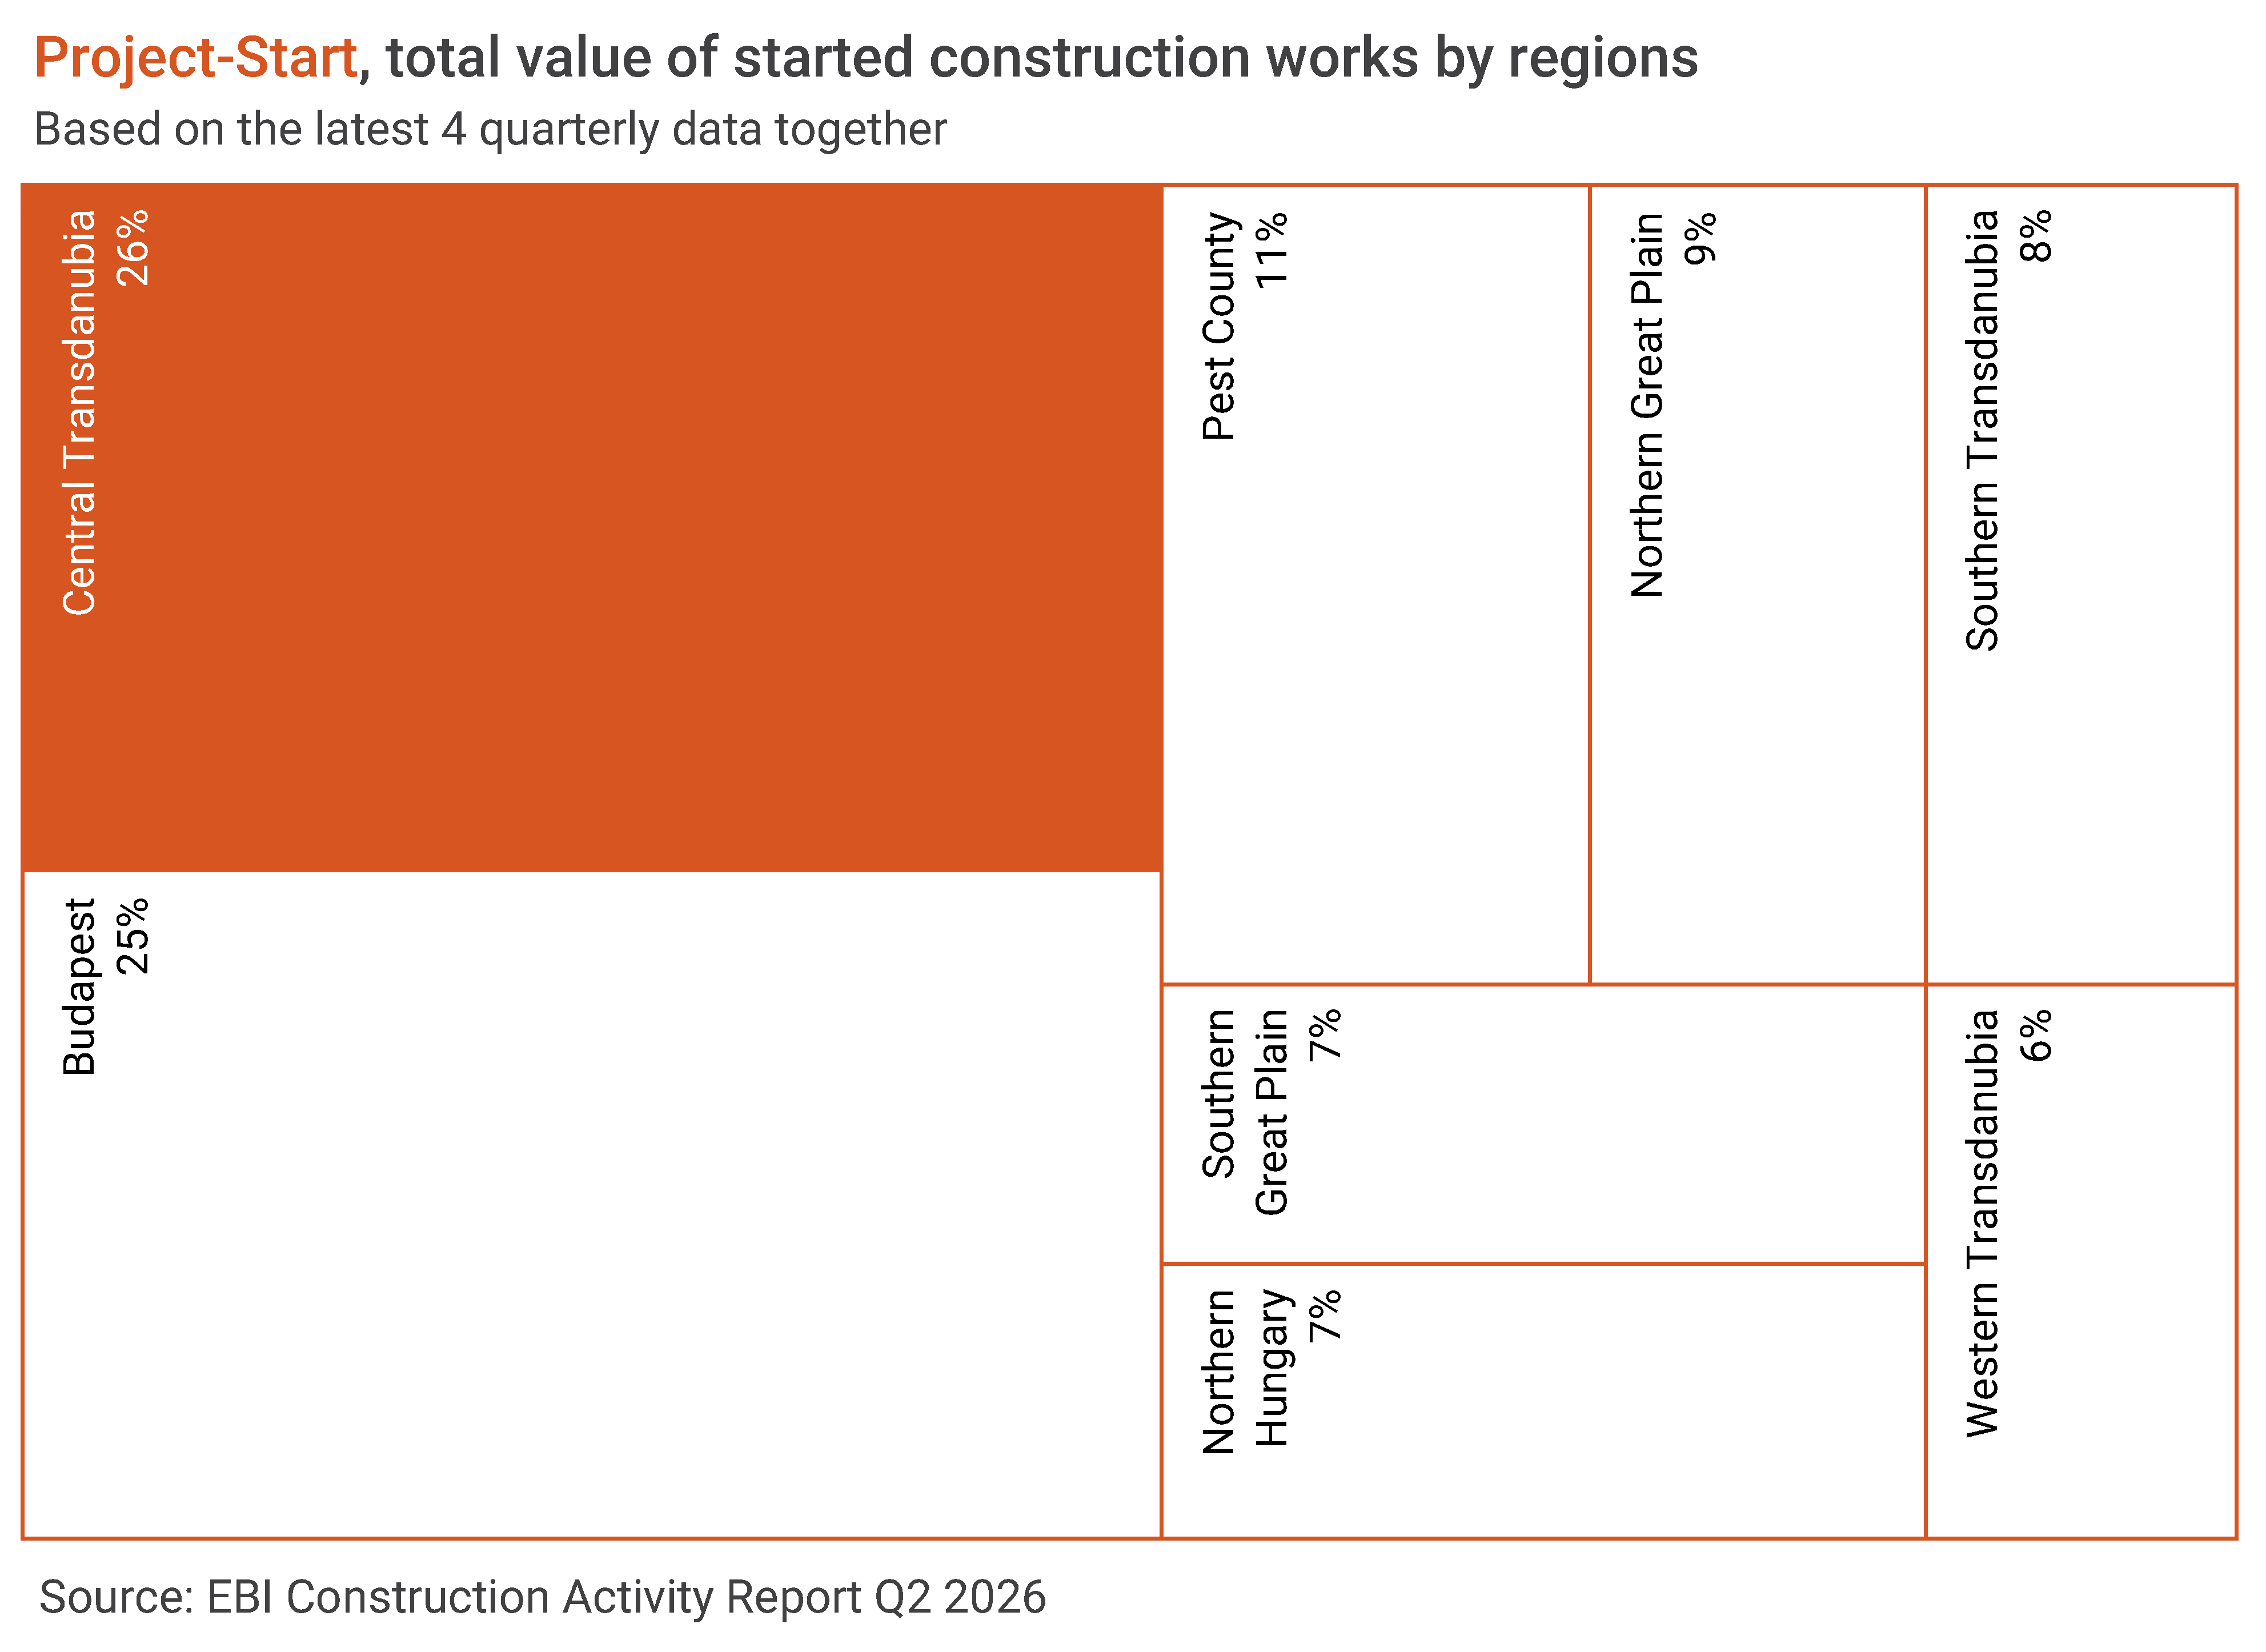
Looking at construction projects launched in the past four quarters, the biggest-value ones started in Central Transdanubia, largely due to the M1 motorway expansion that started in Q3 2025. The region’s share grew to 26%, exceeding the capital city (25%). The lowest value of Project-Start was in Western Transdanubia (6%), while the share of other regions ranged between 7% and 11%.
Decline in the value of started multi-unit constructions in the second quarter
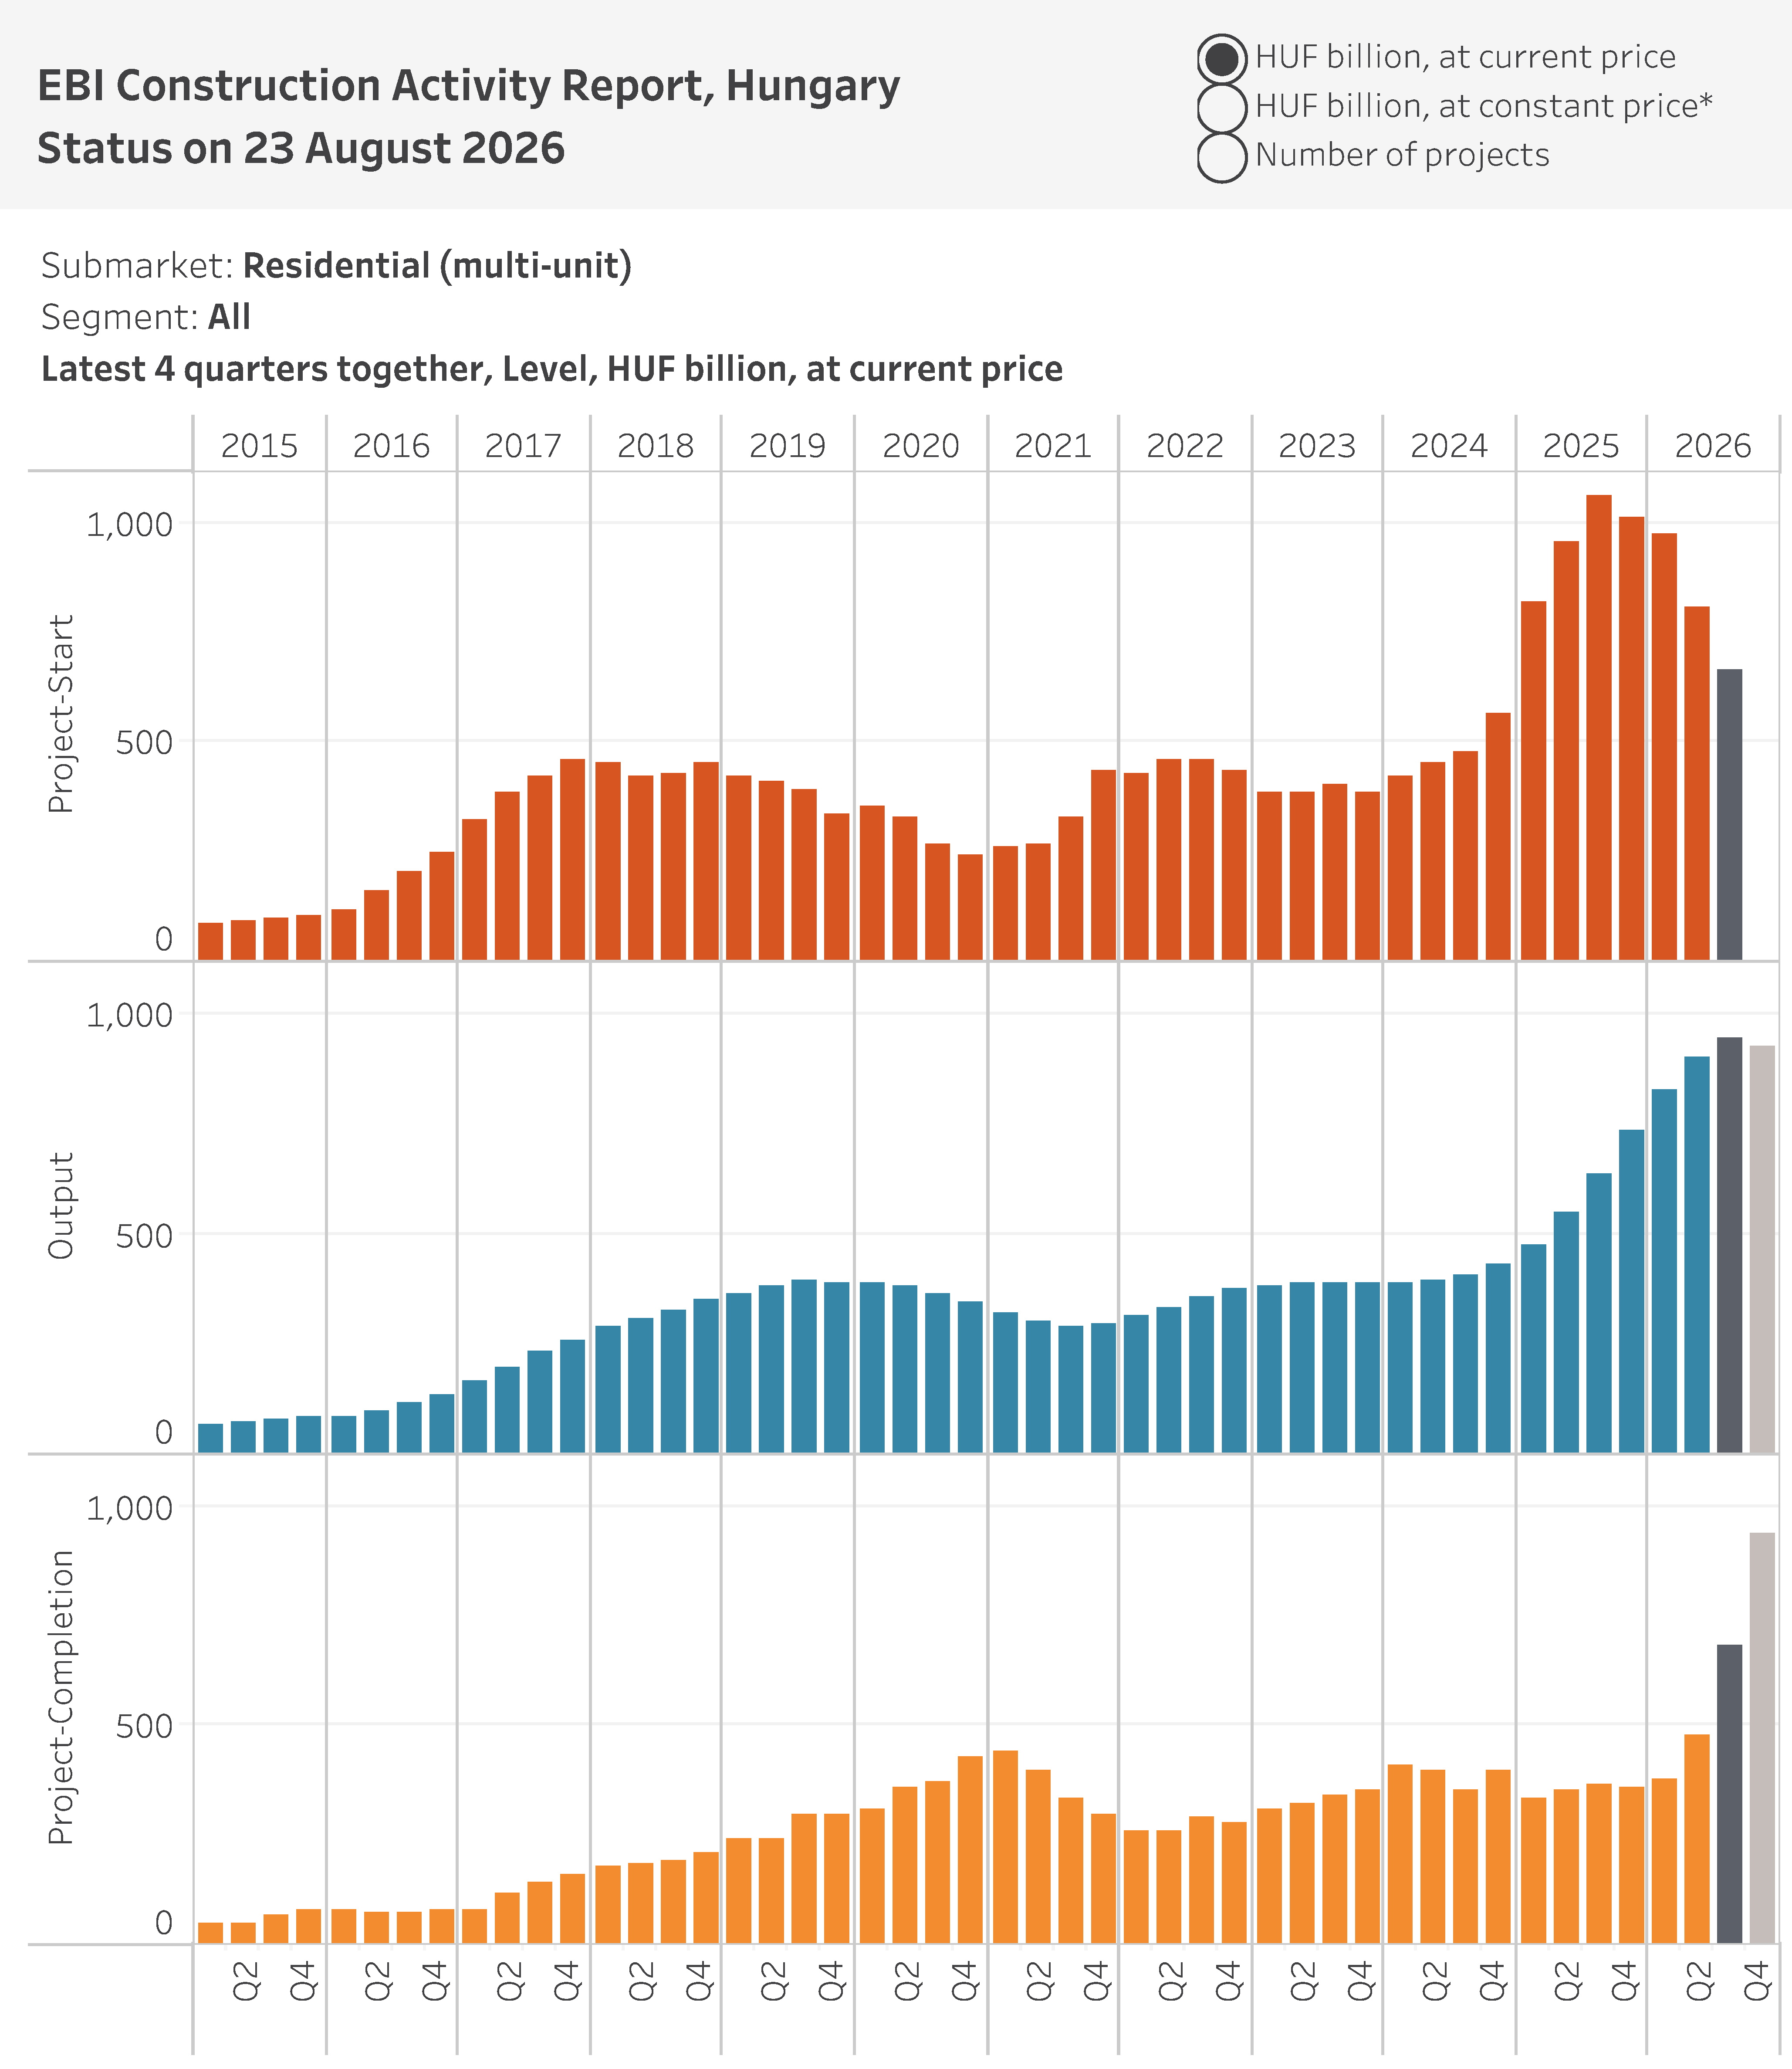
According to the latest EBI Construction Activity Report, multi-unit residential Project-Start barely exceeded HUF 100 billion in the second quarter of this year, which was unprecedented in the past two years. But because construction works in the segment started at a great value in Q1 2026, the figures of the first half year in 2026 overall, even at constant price, only show a 35.5% decline like-for-like. Also, started multi-unit residential works far exceeded the first half-year levels of the years between 2019 and 2024.
Several factors are behind the more subdued project starts in Q2. First, some correction was expected after the near-record Q1. Second, developers may have become more cautious with project starts due to government change and moderate demand. Q3 will also bring lower Project-Start, and reduction is expected for the rest of the year. The suspension and review of certain projects that previously received state support under the Home Start Program is also delaying construction start, which may affect 17 000 dwellings. As of now, little is known about the newly announced Wekerle Housing Program (government initiative for affordable rental housing and student dormitories) as its specifics are expected by the end of the year. What is certain is that the program, with EUR 550 million of EU money, can play a great role in the development of multi-unit residential construction and can launch big projects – although its impact may be more pronounced in mid-term.
Looking at individual regions, the biggest decline in multi-unit residential construction starts compared to the previous quarter was in Pest County and the Northern Great Plain, where the value of projects entering construction was 80% and 84% less in Q2 than in Q1 this year, respectively. The decrease was also 68% in Budapest and Western Transdanubia. Similar trends are visible compared to the average quarterly Project-Start for Q4 2024-Q1 2026, with the largest drop in Pest County and the Northern Great Plain region, followed by Central Transdanubia and the Southern Great Plain. Budapest registered the fifth biggest decrease (55%).
Despite the decline, Budapest played a key role in multi-unit residential starts this year as well, with at least 70% of such constructions starting here in Q1-Q2 of the year. Based on the average of the past years, the capital city’s share of Project-Start in the past year was 63%, while Northern Great Plain had 8%, Western Transdanubia and Southern Transdanubia had a 7% share each. In the past one year, works started in the lowest value in Northern Hungary: the region’s share was only 2%.
The biggest projects this year are also in Budapest where the construction of the last buildings of Kincsem Residential Park and the first buildings of Láng Quarter started. In case of rural locations, the largest project was Liget Residential Park in Tatabánya, but it did not make it into the top 10 biggest projects. A similar trend was seen in previous years: the largest projects were in Budapest, with only few rural projects making it to the top 10 list that started near Lake Balaton, in Debrecen or Paks.
The value of completed multi-unit buildings spiked to HUF 180 billion in Q2 2026, the highest Project-Completion in the past 11 years at current price but also considered high at constant price. Q2 saw the completion of several phases of Kincsem Residential Park and Phase 1 of Beluga Bay condominium whose construction started in 2023 and 2024. Project-Completion in the multi-unit residential segment may remain high in the second half of this year as well since Epresliget Residential Park in Debrecen and Újbuda Garden condominium in Budapest are expected to be completed.
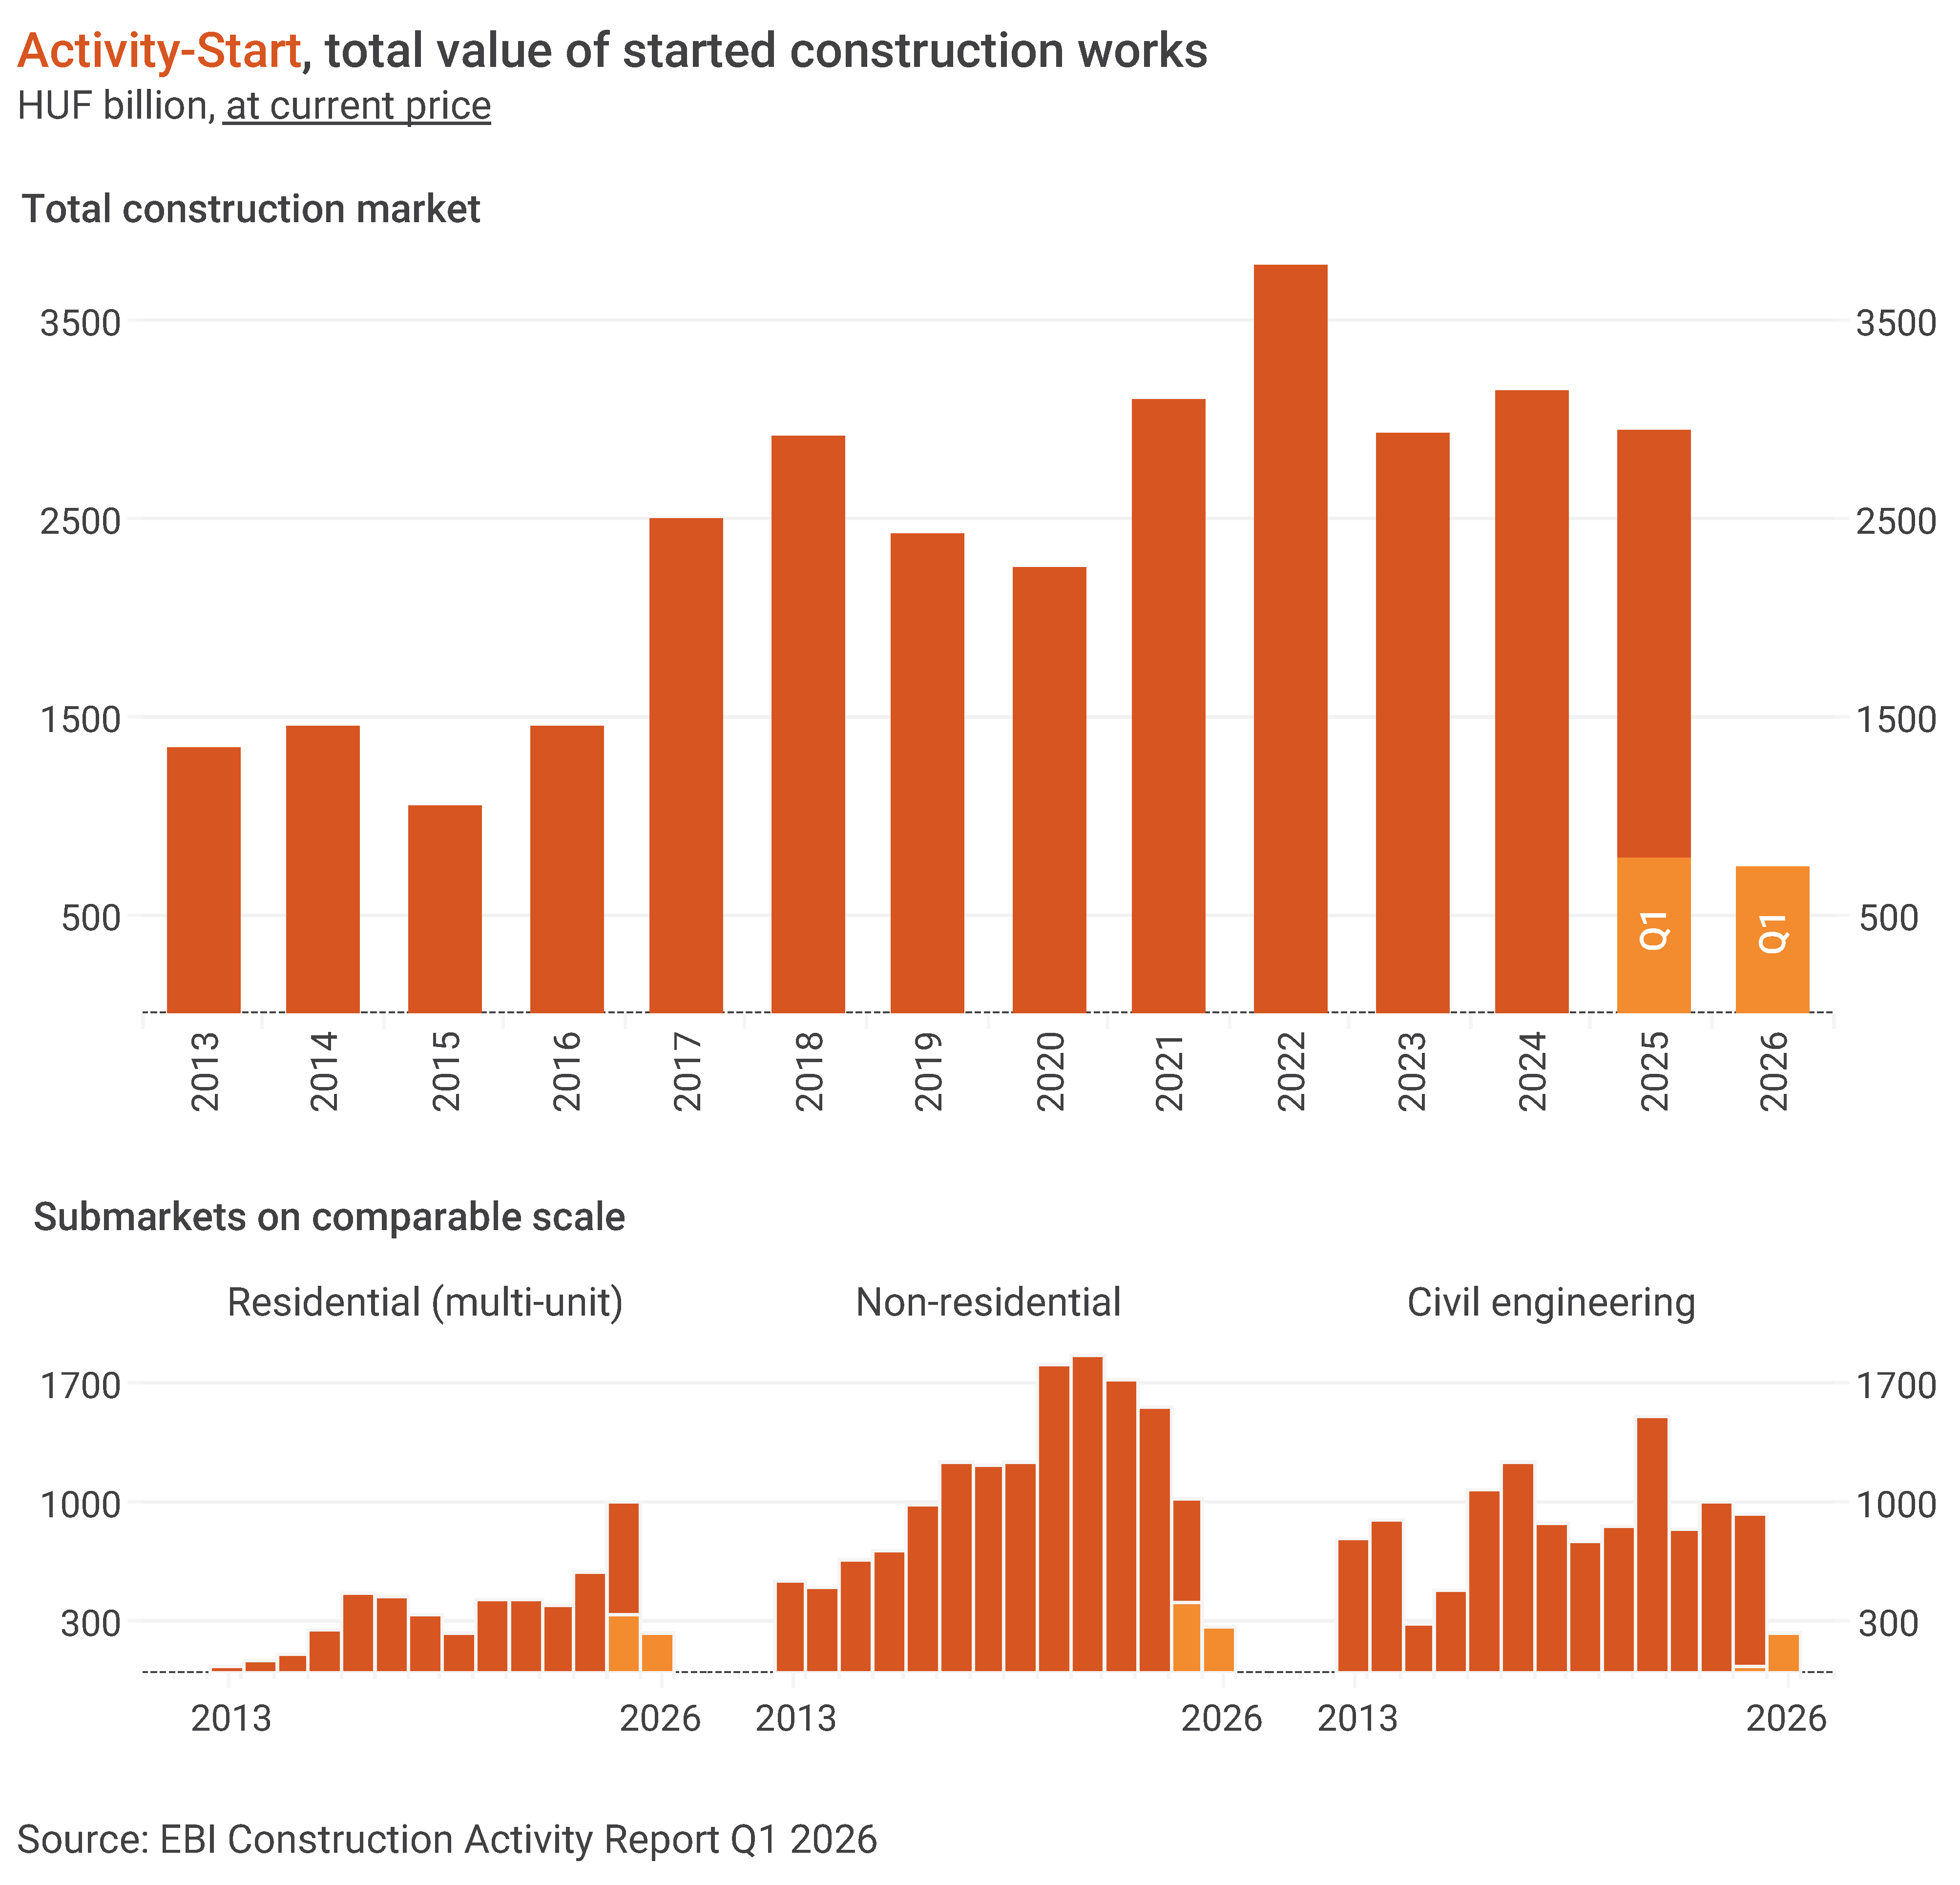
As per the latest EBI Construction Activity Report, 2026 did not start badly in Hungary for construction. Activity-Start in Q1 did not substantially lag behind Q1 2025 and Q1 2023, in fact, it slightly exceeded the average quarterly values of these years. At the same time, the start of foundation works of Block 5 of Paks 2 nuclear plant played a major role in higher numbers, adding a more nuanced picture. Projects worth around HUF 740 billion entered construction in Q1 2026. At constant price, Activity-Start did not lag greatly behind the same period of 2025 (-9%), but we have still seen the weakest first three months since 2016.
EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). To obtain the report, please contact us.
Building construction returns to last year’s level
2026 started much weaker in building construction than last year, but the Activity-Start of around HUF 500 billion was roughly in line with the average quarterly level of 2025 and was only 6% below the average quarterly value of 2024. Hence, no major decline compared to the previous two years at current price. Even at constant price, the value of construction projects started in the first three months was close to the average quarterly level of last year, but it was double-digit below the average three-month Activity-Start between 2016 and 2024.
Multi-unit housing construction is still the segment keeping building construction at a higher level. Activity-Start for non-residential construction between January and March this year (HUF 263 billion) exceeded the average quarterly value of 2025, which was considered weak, but fell 33-44% short of the average values between 2021 and 2024. At constant price, this year’s first-quarter Activity-Start has been one of the weakest since 2015.
Biggest started non-residential projects in Q1 2026 comprised several logistics and office buildings such as Phase 3 of Láng-negyed V1 office building and Frontiers Campus office and research centre in Budapest, and the renovation of BorsodChem offices in Kazincbarcika, Phase 3 of CTP VCS5 Logistics Centre in Vecsés, building D of VGP Park Beta logistics centre in Győr, building B of Panattoni Logistics Park in Mosonmagyaróvár, and Phase 1 of Penny Market logistics centre cold storage in Alsónémedi.
Paks 2 boosted civil engineering figures
In Q1 2026, the value of started civil engineering works neared HUF 240 billion boosted by the start of foundation works of Block 5 of Paks 2 nuclear plant, while the Activity-Start in road and railway projects was only HUF 20 billion. Apart from Paks 2, only one civil engineering project got into the largest projects in Q1 2026: the construction of Phase 2 of the industrial park in Nyíregyháza.
Budapest: regional heavyweight again
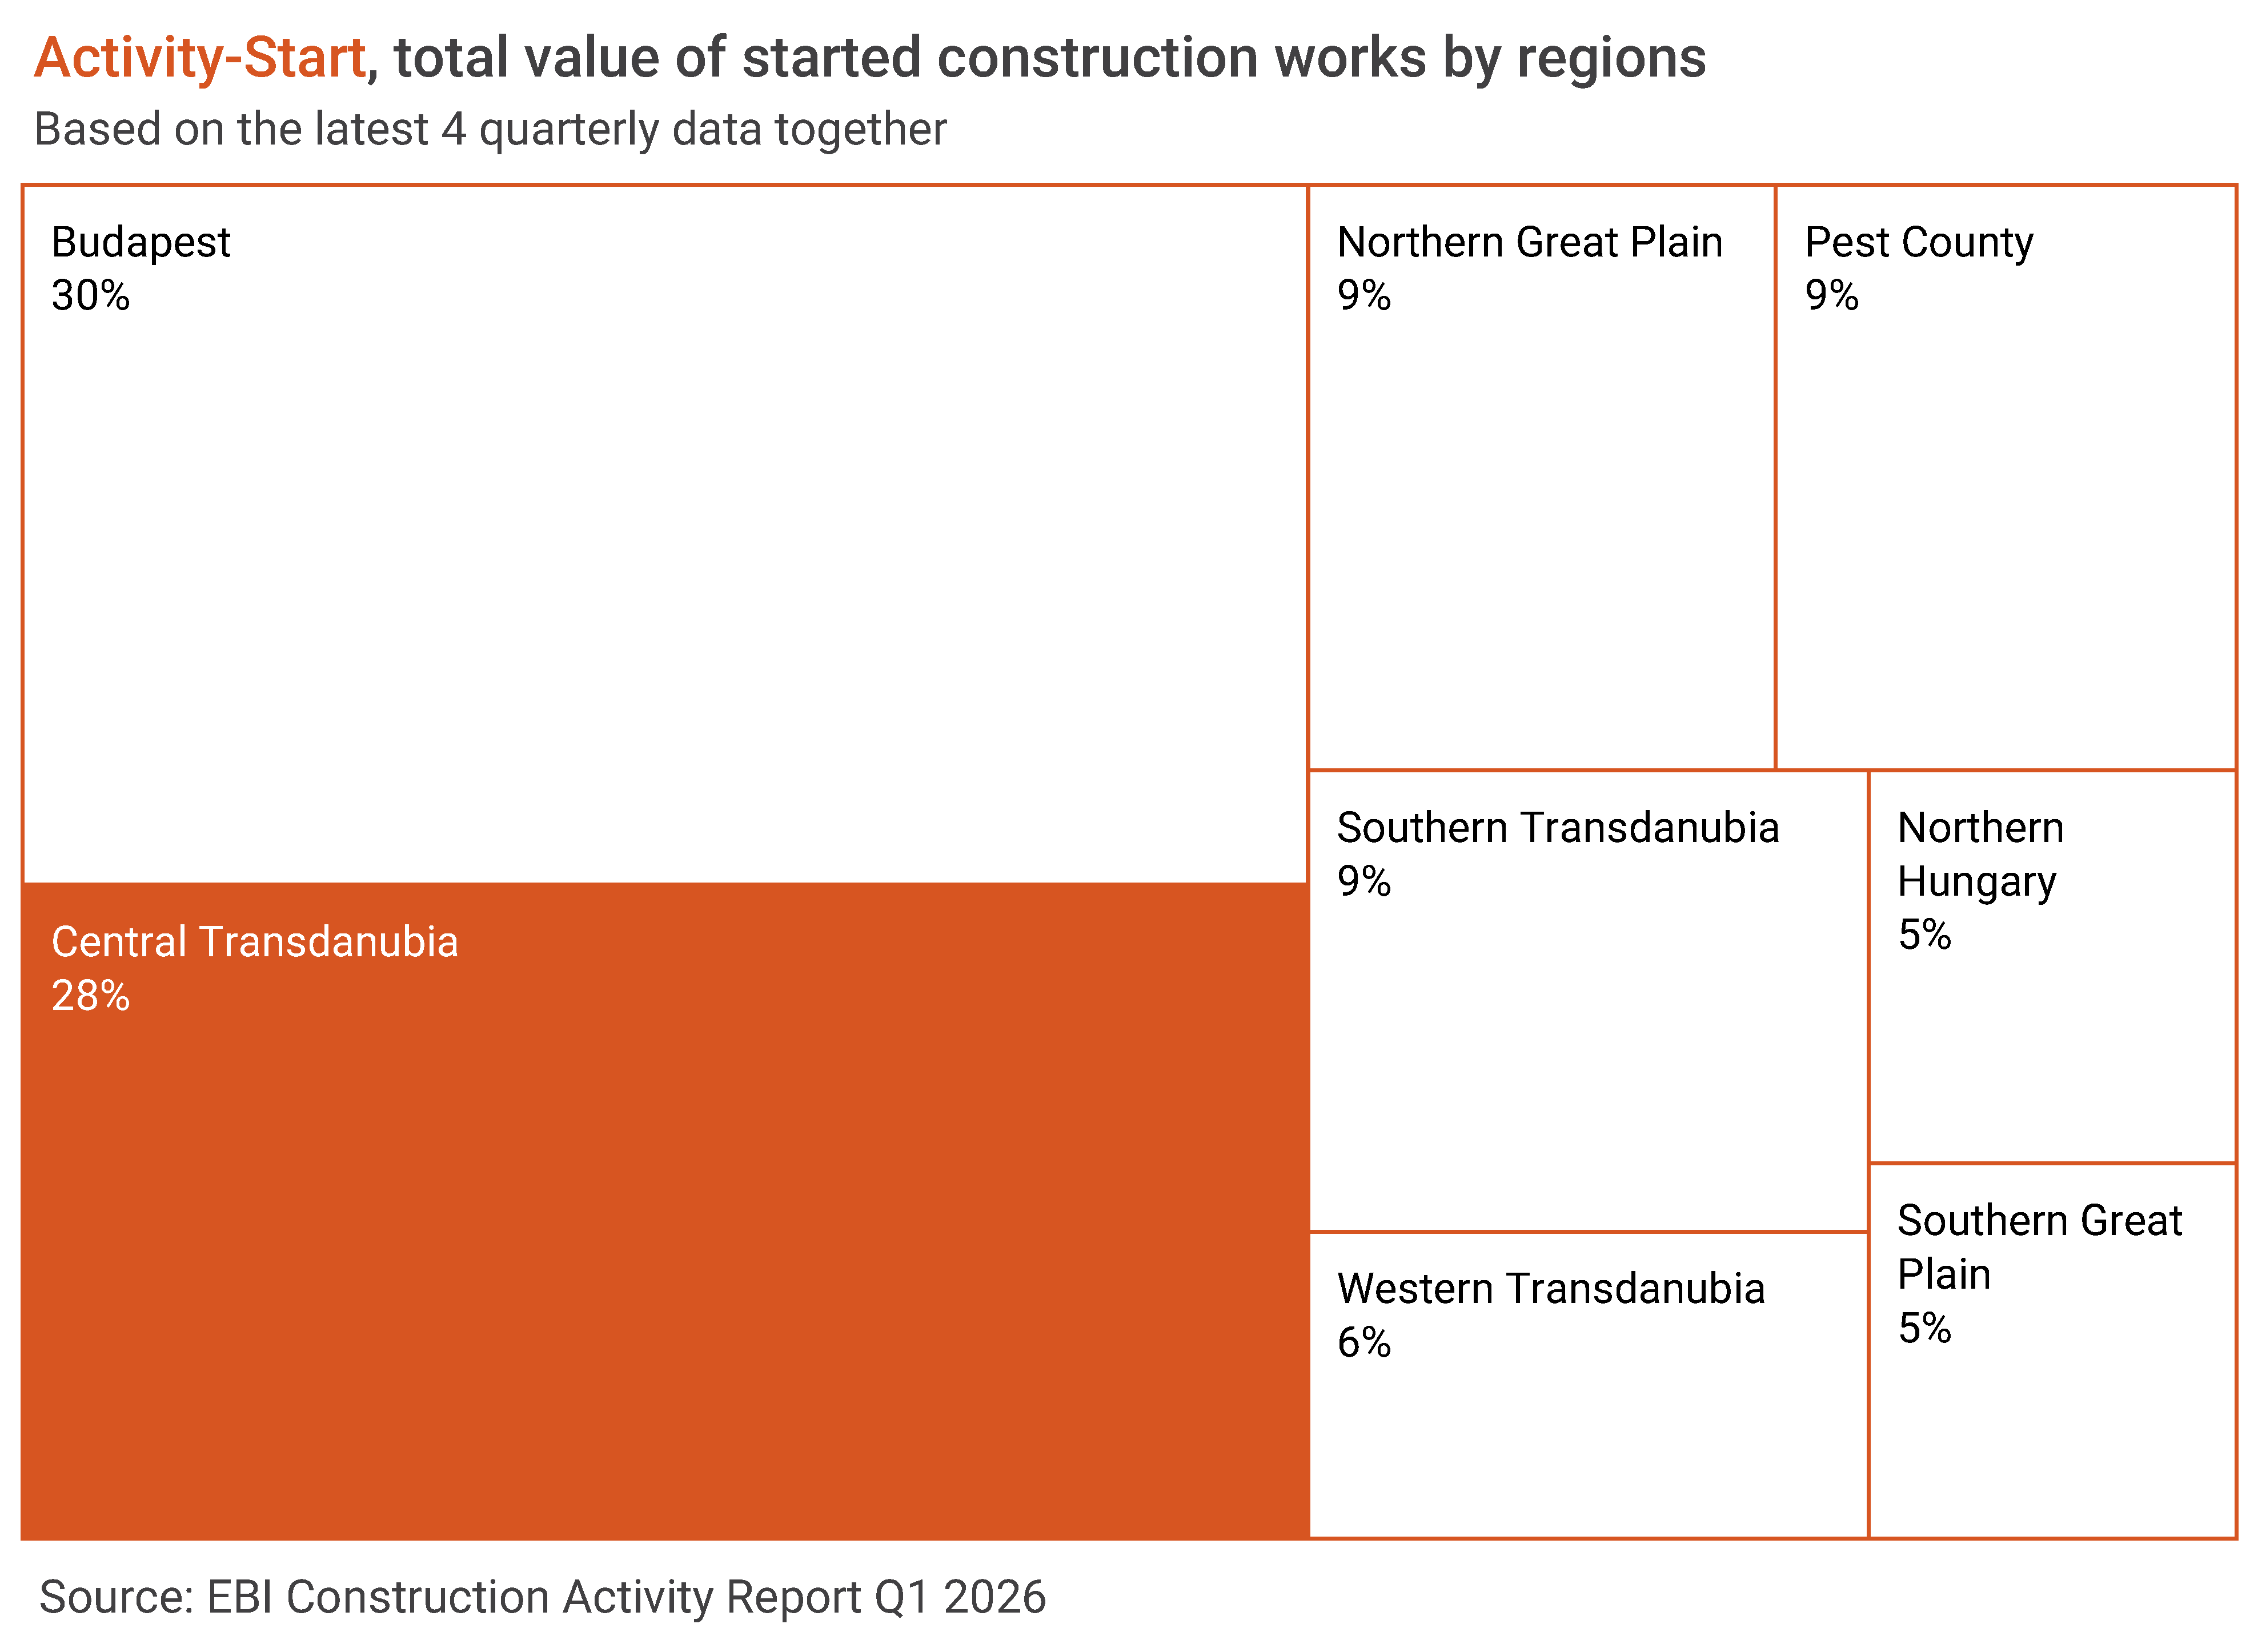
Budapest continued to be the region with the highest value of construction works started in Hungary with a share of 30% in total Activity-Start in Q1 2026. Based on the four-quarter moving averages, the share of Central Transdanubia was still considerably higher than in previous years thanks to the M1 motorway expansion launched in Q3 2025. Pest County, Southern Transdanubia and the Northern Great Plain accounted for about 9% of started constructions, while the share of other regions varied between 5% and 6%.
Multi-unit home construction still high
After a weaker final quarter last year, this year started with an extremely strong first three months for multi-unit housing. Between January and March, the value of started construction works exceeded HUF 240 billion at current price; the third highest quarterly Activity-Start since 2014. This value is significant even at constant price: only 2017-2018 and last year had stronger quarters.
The great increase in permits last year suggested strong activity at the beginning of this year. The latest EBI Construction Activity Report has found that many large projects have moved closer to planned start recently, also predicting a higher Q2 Activity-Start in the segment. However, there is a lot of uncertainty in the market now as projects within the Otthon Start Program are expected to be reviewed, which may change developers’ plans.
In Q1 2026 the value of completed multi-unit building was about HUF 83 billion, still considered a moderate level. At constant price, it is particularly low. But it comes as no surprise as previous years were characterized by restrained project launches, and the large-scale projects that started last year are set to be completed only later.
Looking at the past four quarters, about two-third of multi-unit building projects entering construction phase concentrated in Budapest, so the capital’s share remains exceptionally high. About 69% of projects started in Central Hungary, 13% of the Activity-Start was linked to Eastern Hungary, while Western Hungary’s share was 18%.
Non-residential construction: after a weaker last year, this year started slowly
Within the subsector, two segments accounted for the majority of the Activity-Start: offices and industry. Offices performed rather poorly in previous years but recovered somewhat in Q1 2026 with their share within non-residential construction going up to 34% compared to 9% in the previous two years. Industrial properties and warehouses continued to account for the other major part despite the decline (their share dropped to 36% against 44-54% in the previous four years). In the first three months of this year, about 9-10% of started non-residential projects were related to wholesale and retail and education.
In 2026, besides the previously mentioned office, industrial and logistics projects, the largest non-residential projects also included Cholnoky Jenő Student Camp in Révfülöp, Rheinmetall RDX explosives factory in Várpalota, Mixvill shopping center in Debrecen, and Phase 1 of MyRA Park M3 shopping park. In 2025, non-residential construction was also characterized by weaker Activity-Start, but several high-value projects were launched such as the special operations barracks in Szolnok, BYD’s assembly hall, logistics warehouse, press plant and lightweight construction plant in Szeged.
In the past three years, non-residential projects reached completion at an exceptionally high value, between HUF 1,600 and 1,700 billion. During this period, Phase 1 of eMAG logistics centre, certain elements of BMW and Mercedes-Benz projects and several logistics projects were completed, including Robert Bosch logistics hall in Miskolc. Activity-Completion indicator may remain at a high level this year as well. The Hungaroring paddock building has already been handed over and several elements of BYD projects, Samsung Göd expansion, and several CATL buildings in Debrecen may also be completed.
Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)
With the latest governmental decision, the number of projects in designated rust belt action areas reached 91 in Hungary. 50 thousand dwellings1 are estimated to be built on these brownfield sites. The sole purpose of this post is to follow these projects and to see how they will or will not help the recovery of the new residential construction sub-market in Hungary.
Status on 1 May 2026. Before the election project starts slowed down.The newly elected government promises to double the number of built homes. — Completed: 4 018 dwellings Under construction: 12 622 dwellings Before construction: 27 180 dwellings
Brief background
Rust belt action areas (let me shorten them to rusty) are practically brownfield areas with special benefits. The owner of the site or the developer should initiate the process (with specific development plans) and there is a Committee to examine if the proposed site is entitled for the rusty status. Based on the opinion of the Committee, the final decision is made by the government. The decisions (about the exact sites) are announced in a decree and the special benefits coming with it are:
priority investment status, meaning e.g. faster permitting procedures2,
newly built homes can be sold at 5% VAT without limitation in time3,
By the current regulations, it means a min. 5% and a max. 27% price advantage over competitors developing on non-rusty area until 2030 (depending on when the permit was obtained) and a 27% price advantage from 2031 on.
Our focus
What we do is to turn the mentioned decree into information we need for forecasting. With the help of Eltinga Building Permit Monitor database and the iBuild project information database, actual projects are identified from the lot numbers specified in the decree. Among all the general project specifics, the number of dwellings (where it is known), are attached to these projects.
The map shows the stages of the housing projects that were given rusty status. Bluish dots are those before construction, neon yellow dots are those under construction and the dot disappears once the project is completed.
OK, it is very convenient to see projects on a map, but our focus is more on the chart under the map where the yellow is the number of homes under construction.
What we are curious about is if and when the right end of the yellow curve shows a strong upturn.
In other words, we are curious whether the regulation ignites a recovery or not. In the first years of the regulation, it was more common that the yellow line has increased because projects having started in the past were given the rusty status. (So they were just re-qualified, it did not mean new project starts.) In parallel, it was less common that projects start after they were given the status. Just two extreme examples for these: Unipark Buda had been under construction between 2019 and 2024 and it got the rusty status at the end of 2023, while Láng District was given the rusty status in 2021 and actual works commenced 5 years later. This has changed by now. So currently the yellow line increases if new projects starts. More precisely if the number of dwellings in newly started projects outnumbers the number of dwellings in completed projects.
The charts are updated quarterly.
Another way we like to look at it is a list. Here we do not separate the projects to phases (like on the map) and it gives a quick understanding on how each rusty project moves ahead from 1 February 2024 on.
Data sources
The data mostly come from Eltinga Building Permit Monitor (in Hungarian: Építési Engedély Figyelő). This is a very detailed database on before construction multi-unit housing projects in Budapest. It is aiming primarily at developers who would like to understand the competition. For further information on this, please turn to Mr Zoltán Sápi, Eltinga, sapiz@eltinga.hu. Besides, we use the iBuild project information database.
This is an estimation based on the median size of those rusty projects where the number of homes were announced ↩︎
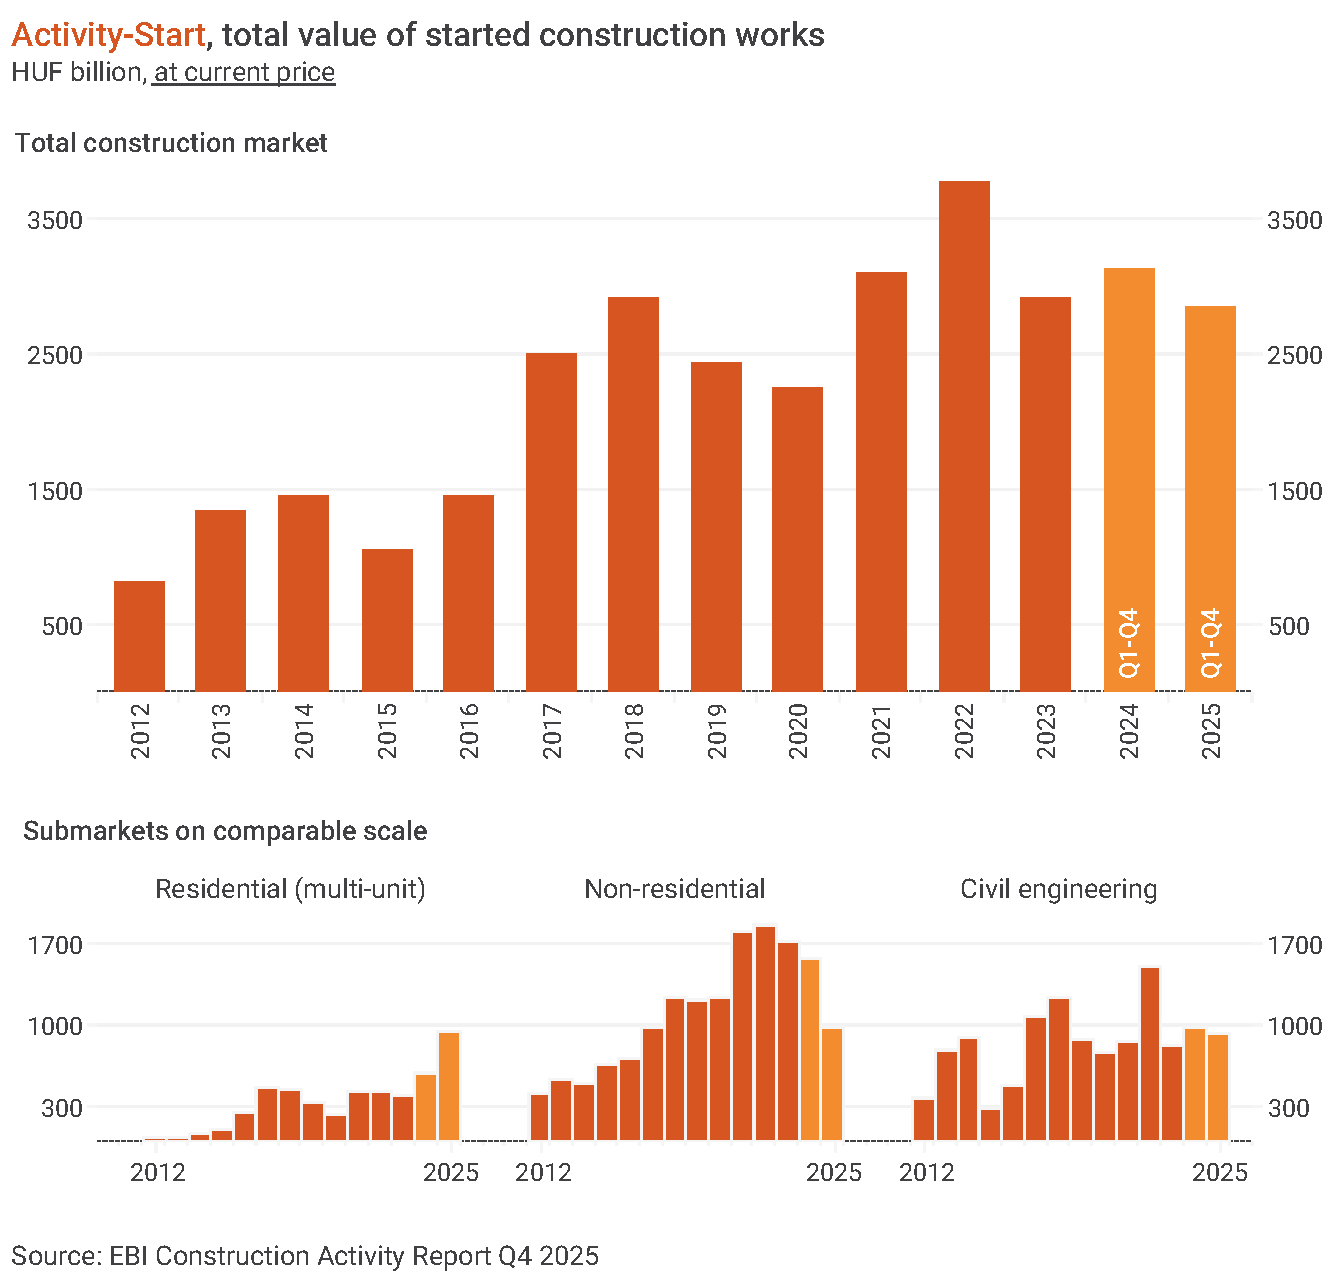
The latest EBI Construction Activity Report has found that although the expansion of M1 motorway caused a considerable surge in the value of started construction projects in Q3 2025, Q4 brought very low Activity-Start. Even at current price, such a low number of construction projects did not start in a quarter in the past 9 years. However, thanks to the high numbers in Q3, annual Activity-Start only slightly sank against 2024. In total, projects worth nearly HUF 2,900 billion entered construction phase in 2025.
EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). To obtain the report, please contact us.
Declining Activity-Start in building construction in Q4 2025
In Q4 2025, Activity-Start in building construction decreased significantly compared to previous quarters. However, due to the higher first quarter value, the full-year decline remained 10% compared to 2024, while the decrease was 8% over 2023.
Overall, construction works started in the segment last year were worth slightly less than HUF 2,000 billion, the lowest level between 2021 and 2025. Due to the significant increase in multi-unit residential construction in 2025 and the few construction starts in non-residential buildings, multi-unit residential construction accounted for almost half of building construction Activity-Start, which has not been the case since the first half of the 2000s.
Non-residential construction was characterized by a decline in Q4, and the value of started construction works was roughly at the same level as in Q2, which was also modest. For the year as a whole, non-residential Activity-Start was around HUF 1,000 billion, the lowest value in the period between 2018 and 2025. It also shows a 37.5% decline compared to 2024 at current price, and a 43% drop over 2023.
The largest non-residential projects entering construction phase in Q4 2025 included the construction of several logistics centres, such as CATL warehouse in Debrecen, Porsche Parts Center logistics-warehouse centre in Budaörs, and Building C of VGP Park Budapest Aerozone. Several hotel projects began, too, including the construction of Mama Shelter Hotel and Ruby Hotel in Budapest, and Danubius Hotel Annabella ***Superior in Balatonfüred.
M1 highway expansion boosting civil engineering Activity-Start in 2025
Following Q3 2025, which registered high Activity-Start due to the expansion of M1 motorway (M0-Concó rest area), Q4 2025 saw a very low value of started civil engineering works in Hungary. Few projects started not only in value, but also in number.
Thanks to the motorway project, annual figures tell a nicer story with projects starting in the value of nearly HUF 1,000 billion in 2025. It did not differ much from 2024, although the figures then were also boosted by the start of one large project, the construction of the Mohács Danube Bridge and related road network. Overall, in 2024-2025, apart from these two large projects, the value of civil engineering projects entering construction phase would have been very moderate. In Q4 2025 not a single project made it to the list of biggest started ones, indicating the reduction in civil engineering in that quarter.
Budapest continues to lead Activity-Start
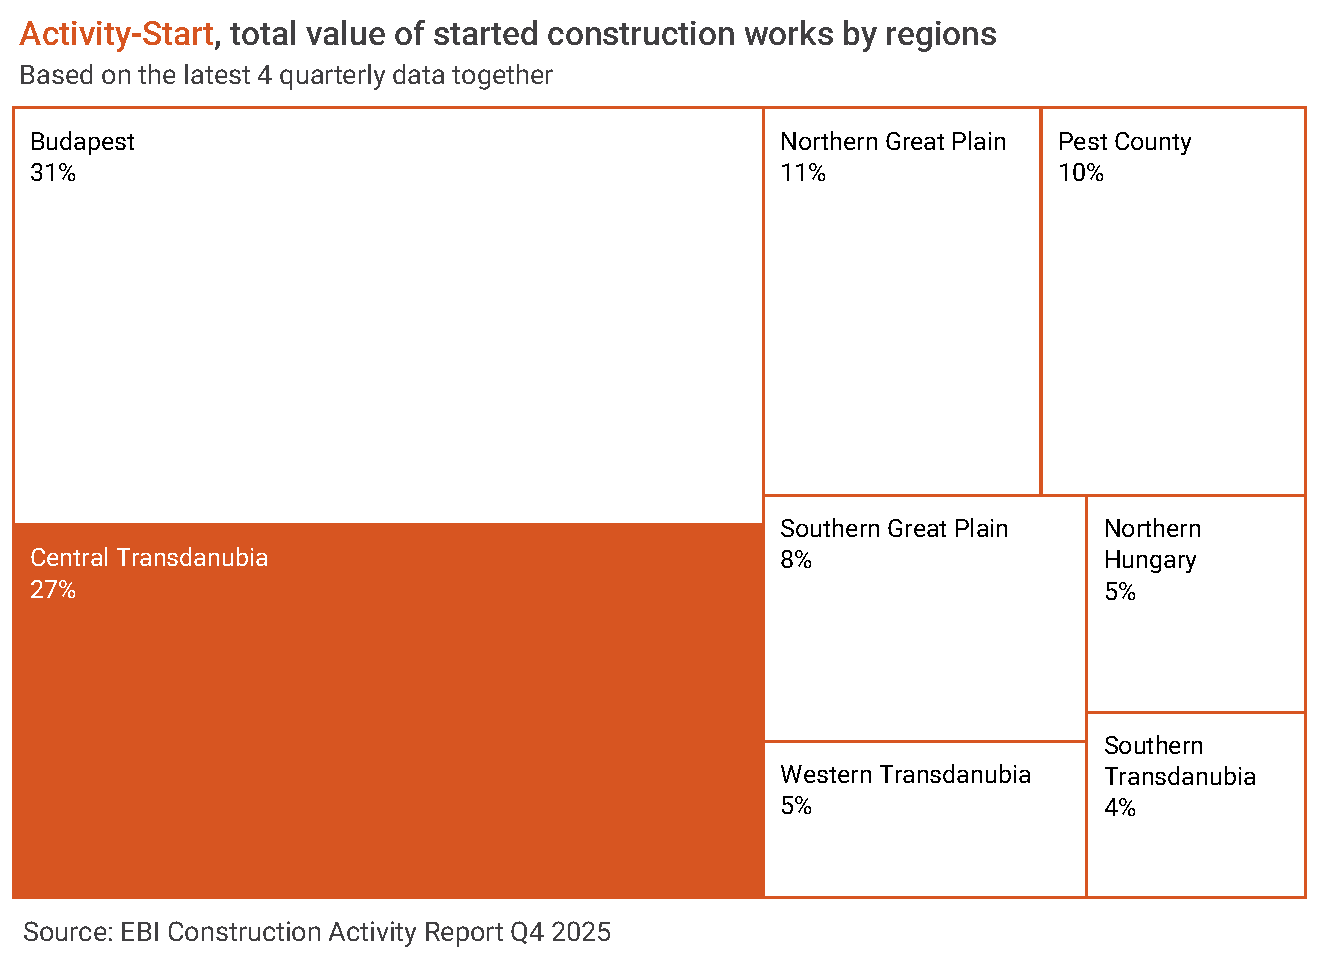
Budapest had the highest share, 31%, within total Activity-Start in the last four quarters. Central Transdanubia also had a high proportion, more than 27%, primarily due to the M1 highway expansion. Together, more than 40% of works started in Central Hungary, 36.4% were related to Western Transdanubia, while the share of Eastern Hungary was 23%.
Sluggish multi-unit residential developer activity in Q4 2025
Q4 2025 saw another decrease in the value of started multi-unit residential constructions, with the cost value of started works falling below the level of Q2-Q3 2024, the second lowest value in the past two years.
However, 2025 overall was still a record year thanks to the high activity in the first 3 quarters of the year. Works worth nearly HUF 1,000 billion started, exceeding the Activity-Start of the previous year by 60% even at current price. At constant price, it was roughly equivalent to the record holder years of 2017-2018.
2026 may also register strong multi-unit residential construction as last year’s preliminary data shows surge in building permits. Further boost may come from the Otthon Start Program which was launched in September 2025 (subsidy helping first-time homebuyers secure up to HUF 50 million in mortgage financing with a fixed 3% interest rate and a maximum 25-year term) and the Capital Program, which was also started last year. In connection with the former, the construction of several thousand units has been announced in priority projects, and applications for several thousand more may be given green light. Since sales deadlines must also be met in priority projects, their start is expected soon with many construction works beginning this year.
The weaker project start in recent years was also visible in the Activity-Completion indicator in 2025. Multi-unit homes worth a total of HUF 370 billion were completed last year, roughly 8% below the 2024 value.
Regionally, in the past 4 quarters, most multi-unit residential Activity-Start was related to Budapest with 68% of works starting here in 2025. Central Hungary, including the capital city, accounted for 70%. 16% of works started in Western Hungary and 14% in Eastern Hungary.
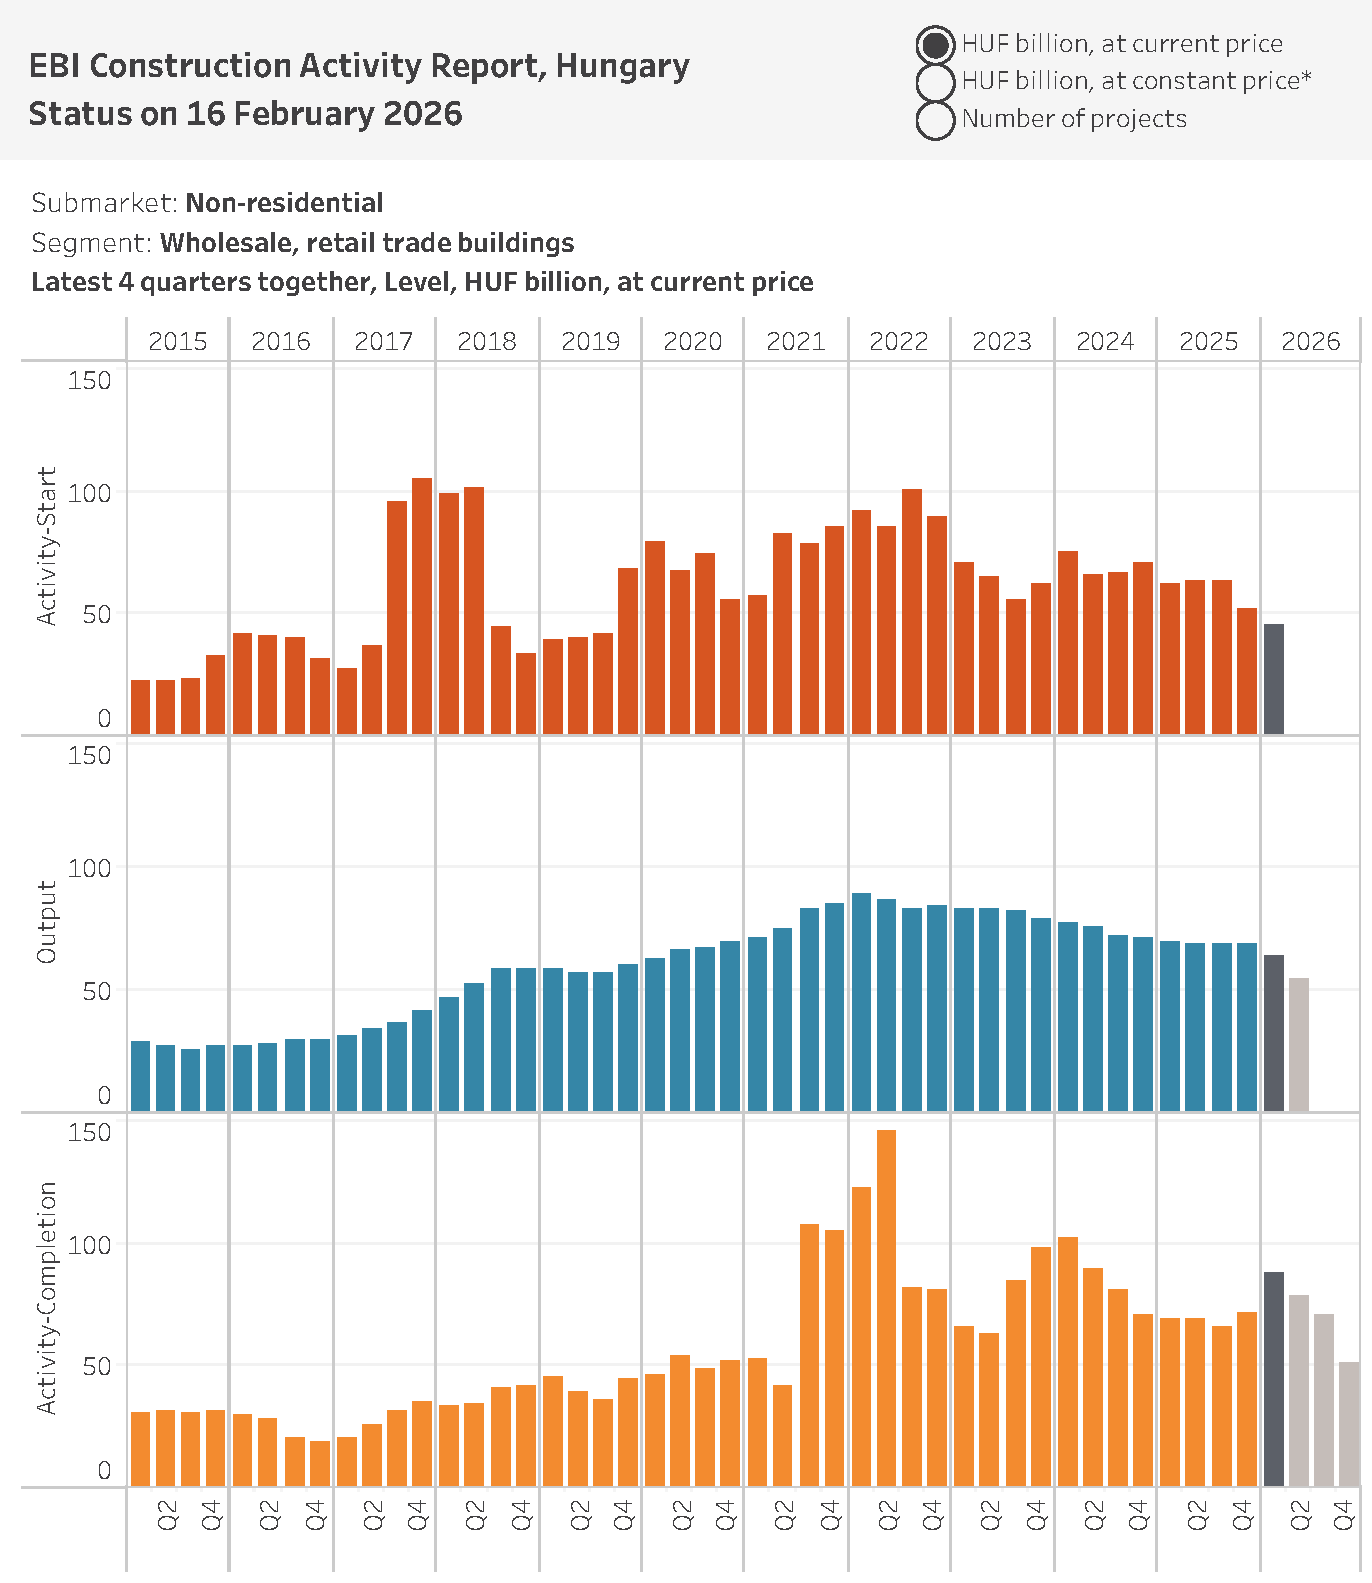
Moderate wholesale and retail Activity-Start in Q4 2025
The last time an outstanding Activity-Start was registered in wholesale and retail was in 2017 and 2021-2022. In 2017 the start of construction of Etele Plaza contributed with the highest value, while in 2022 two big project starts played a major role in higher numbers (ActiCity Event Center in Veszprém and Phase II of Zenit Corso shopping centre in Zugló).
2025 brought a rather modest Activity-Start in wholesale and retail, works started by a 27% lower value than in 2024. The decline compared to 2023 was also 16%, roughly at the level of 2020, and the shrinkage compared to the peak years (2017 and 2021-2022) was 39-50%. Despite the drop, larger projects began last year, such as OBI DIY store and Drive-in in Kistarcsa and Stop Shop in Salgótarján.
In 2025, a total of HUF 71 billion worth of wholesale and retail properties were completed, the same as in 2024, for example, the shopping court in Táncsics Mihály Street in Komárom, Phase I of Time Out Market in Budapest, Mömax home improvement store in Székesfehérvár, and Spar store and Dera Park shopping park in Szentendre.
Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)
EECFA released its 2025 Winter construction forecast on 12 December. Check out a sample report and place your order on eecfa.com. For discount, please contact us.
Southeast European construction markets
“Bulgaria’s total construction output is forecasted to increase by 3% on average for 2026-2027” – says Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian research institute. He adds that this is to follow estimates for a similar performance of almost 3% in 2025. The sectoral background, however, shows, a nuanced picture – cooling of residential construction, positive news from non-residential and a robust performance of civil engineering. The latter will benefit from investments which will be backed by the absorption of EU funds through the Recovery and Resilience Plan (RRP) and classical operational programmes, both with implementation deadlines in 2026 and 2027. At the same time, Bulgaria’s economy is to expand by 2.4% on average in 2026-2027 – a period continuously shaped also by the Euro adoption on 1 January 2026.
Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s Croatian members, think that declining dwelling sales in Croatia have, paradoxically, failed to stop the growth in the value of Croatian residential output, because increases in the price per square meter of those dwellings that do get sold have more than compensated for the lower number of square meters bought. “But how long this can continue is unclear” – they add. “The policies that the Croatian government is implementing in order to ease the country’s housing crisis are confusing the residential picture still more, since a number of those policies have contradictory effects on output. As to non-residential building construction, output growth during the period covered by the current forecast will depend greatly on the sector, with some likely to continue to benefit from catch-up growth and EU support for a bit longer and others moving toward a steady state or even a decline. In civil engineering, EU funds continue to play the dominant role in financing construction of all sorts. Sports facility construction is experiencing a boom, but given the speed with which such projects are completed, the effect on output will be relatively brief. Renewable energy construction should be growing rapidly, but regulators’ hostility toward the sector are holding it back.”
“Romania’s economy is entering a challenging period as the recently implemented measures to reduce the national account deficit begin to take effect” – reports Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild. “While most forecasters do not anticipate a recession, economic growth is expected to remain subdued over the next two years. Inflation is the highest in the EU, boosted in 2025 by increases in sales taxes. As a result, consumer prices are rising at a pace that is forecasted to outstrip wage growth, leading to a decline in real incomes in both 2025 and 2026. Government spending is also facing cuts, thus both private and public consumption are predicted to decline, with a chilling effect on most construction activity types. There is also the challenge of the massive level of public investment required by civil engineering projects that have started since 2023, which will be difficult to sustain under the austerity and the mounting pressure of losing even more EU funding. On the brighter side, both the economy at large and the labour market are expected to be quite resilient. By 2027, assuming the deficit reaches manageable levels, the effects of contractionary policies should fade out, inflation could ease, and interest rates could come down. This means that demand for construction would rebound and with it, construction activity.”
Dejan Krajinović, EECFA’s Serbian researcher (Beobuild) says that “Serbia’s overall construction output sank into a negative territory in 2025, primarily owing to the weaker performance in civil engineering. This year recorded growth in building construction, but the substantial consolidation in civil engineering dragged totals in red. The completion of major road, railway and energy projects contributed mostly, but delayed construction starts played a role as well. Residential construction is stable and is on historical levels, while non-residential construction is booming led by the hosting of the EXPO 2027 in Belgrade. Investments into commercial, hotel and office buildings are all spurred by the event, with the purposely built EXPO 2027 complex consisting of numerous venues being the single largest investment in non-residential. Improving financial conditions and sustained demand still support relatively high construction activity, but a lot of global political and economic uncertainties are dimming future prospects.”
Dr. Aleš Pustovrh at Bogatin, EECFA Slovenia, says that Slovenia’s construction sector is holding steady at EUR 6bn, though growth has cooled. Residential buildings remain the anchor, with output expected to show only a slight dip in 2025, helped by strong employment, rising wages and cheaper mortgages. Property transactions rebounded in early 2025, reversing last year’s slump, while prices continue to climb amid land shortages and slow permitting. Public housing programmes are ambitious, but private developers are concentrating on Ljubljana and coastal towns. Non-residential construction is mixed: offices are recovering slowly, retail stays subdued, but industrial and warehousing thrive on export demand and automation while health and education remain at very high levels. Civil engineering and public works lean on EU-backed projects and are anticipated to reach historically high levels by 2026.
Eastern European construction markets
Andrey Vakulenko at Macon, EECFA’s Russian research institute notes that “the high key rate and the overall economic slowdown are constraining the Russian construction industry with negative trends expected for the current year and over the next two years. An easing of monetary policy, which has already begun, could help normalize the situation, but a positive effect is not expected until 2027. The main drag on construction output will likely be the residential subsector where high rates and revised government demand support principles are reducing activity among both buyers and developers. Negative trends will also likely persist in most non-residential segments due to declining growth rates of budget financing, a general decrease in business activity and a slowdown in consumption. The overall descending dynamics in the construction market may somewhat be mitigated by stable growth in civil engineering driven by export projects in energy and transport, but this growth is not predicted to be enough to keep the construction market in a positive zone”.
Prof. Ali Türel, EECFA’s Turkish researcher, reports that “the major effect of inflation-curb policies in Türkiye is the decline in disposable income and in the purchasing power of wage earners and pensioners. The moderate to lower-income population is unlikely to save enough equity for buying a home when rents have also become unaffordable for many. Ironically, housing sales have been increasing at a much higher rate than the growth of households. This can be attributed to the typical trend in Türkiye, where, during inflation, people expect a higher real return on their financial assets from real estate investments compared to alternative investment options. The reconstruction of earthquake-damaged buildings and infrastructure also contributed to the high rate of growth in building starts and completions from Q2 2025 onward, leading to the highest rates of change in the construction sector’s contribution to GDP compared to other sectors. Our latest forecast indicates that total construction output in Türkiye may reach 6.4 trillion TL in 2027 (EUR 180 billion), all at 2024 prices.”
According to Prof. Sergii Zapototskyi of Uvecon, EECFA Ukraine, despite the war and high risks, Ukraine’s construction industry remains one of the key drivers of economic recovery in 2025. The RDNA4 (the latest Rapid Damage and Needs Assessment Report) estimates Ukraine’s reconstruction needs for the next decade to be USD 486-524 billion, creating long-term demand for residential, non-residential and civil engineering construction works. Major challenges persist, including the uncertainty regarding the duration of the war, especially in frontline regions, labour shortages, bureaucratic barriers in the urban planning legislation, and logistical constraints due to the relocation of production facilities, and often, shortages in building materials. At the same time, the industry is demonstrating resilience: developers are diversifying supply chains, stabilizing procurement schedules, and increasing activity in the Central and Western regions. Demand for housing, intensive infrastructure restoration, and international investment from the EBRD, EIB, and other partners continue to support positive dynamics. The sector’s development prospects for 2026-2027 will largely depend on the security situation and the effectiveness of state recovery programs.
The latest EBI Construction Activity Report Hungary has found that it was mainly due to the ongoing M1 motorway expansion that the value of started construction projects rose significantly in the third quarter of this year. The value of projects entering construction in July-September 2025 exceeded HUF 1,000 billion at current price – the second highest level in the past ten years. Without this motorway expansion, accounting for around 60% of Activity-Start, the figures would have been much more modest, though.
EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database).
Building Construction Activity-Start
In Q3 2025 the value of started building construction projects was HUF 400 billion, around the same value as between April and June. Thanks to the outstanding figures between January and March, the value of building construction projects entering construction phase exceeded HUF 1,500 billion, only 4 points short of the same period in 2023 and 2024. At constant price, Activity-Start between January and September of this year was the lowest in the past 9 years.
Activity-Start of EBI Construction Activity Report in multi-unit housing construction, although greatly sank, stayed at a high level, with the total value of projects started in Q3 2025 exceeding HUF 170 billion. The situation was the opposite in non-residential construction. The segment recovered somewhat between July and September from the previous quarter’s low point, but projects still entered construction at a low value: Activity-Start was around HUF 230 billion. Since 2017 non-residential construction projects haven’t started at a lower value than in the first 9 months of this year.
The largest non-residential projects entering construction in Q3 2025 included MCC’s talent centre in Miskolc, BYD’s electric bus assembly plant in Komárom, Panattoni Logistics Park Building A in Mosonmagyaróvár, IGPark automotive parts manufacturing hall in Nyíregyháza, Phase 2 of Weerts Ebes logistics centre, and MVM Neuron headquarters office building in the 3rd district of Budapest.
Civil engineering Activity-Start
Civil Engineering Activity-Start of EBI Construction Activity Report registered a surge in Q3 2025 due to M1 motorway expansion (M0-Concó rest area). Outside road construction, the value of construction projects started in other civil engineering segments was moderate. While total Civil Engineering Activity-Start exceeded HUF 760 billion, the value of non-road and railway projects started was only around HUF 50 billion in Q3. In addition to the two phases of M1 motorway expansion, only Phase 7 of the closure of the Gyöngyösoroszi ore mine could make it to the list of the biggest started civil engineering projects.
Budapest on top among regions
In the past four quarters, the highest value of construction projects in Hungary started in Budapest and its share in total Activity-Start was 28%. Central Transdanubia also had a large share of 23%. 39% of projects started in Western Hungary, 38% in Central Hungary, while Eastern Hungary’s share was 23%.
Still high multi-unit housing Activity-Start
Although Q3 2025 was the second consecutive year to see a significant drop in the value of started multi-unit housing construction works, Activity-Start stayed high, far exceeding the average of recent years. At current price, multi-unit housing construction works started at an over HUF 170 billion, the fourth highest value after the first two quarters of 2025 and the last quarter of 2024. Overall, the successful first 9 months of this year brought a huge jump in multi-unit housing Activity-Start at current price, but it was also outstanding at constant price, only surpassed by the same period in 2017 in the last 10 years.
Multi-unit housing construction is likely to remain strong. There was a high number of building permits issued in the first three quarters of this year, meaning plenty of projects to get started. In Q3 2025 permitting was boosted by the preferential loan program dubbed Otthon Start available since September which could continue to have a positive impact on the number of homes under construction.
In Q3 this year, multi-unit homes worth around HUF 80 billion were completed at current price, while in the first 9 months, multi-unit housing Activity-Completion was well over HUF 200 billion, only slightly lower than in the same period in 2023-2024.
Looking at the past 4 quarters, Budapest continued to have a major share in multi-unit constructions entering construction (73%). Central Hungary had a 76%, while Western Hungary and Eastern Hungary had a share of 12% each.
Still weak Activity-Start in industrial buildings and warehouses
Industrial buildings and warehouses thrived between 2022 and 2024 when construction works worth between HUF 700 billion and 1,000 billion started annually. For example, construction started on several BMW plants around Debrecen, on Mercedes-Benz projects in Kecskemét, and on several battery factories. This year has seen a decline so far and the value of projects started during three months in Q2-Q3 2025 has been the lowest since 2021. Overall, in the first 9 months of 2025, Activity-Start in industrial buildings and warehouses was around HUF 400 billion, 37% lower than in the same period of 2024, and 29%-39% lower than the 2022-2023 values. Trends are similar at constant price: the period of 2021-2023 was exceptionally good for industrial buildings and warehouses, while there was a strong decline in 2025. In the last 10 years, Activity-Start at constant price in the first 9 months has not been so low as now.
The biggest projects started between January and September 2025 were CTP’s logistics halls in Biatorbágy and Vecsés, HelloParks’ logistics hall in Fót and BYD’s projects in Szeged and Komárom. Construction of Phase 1 of Halms automotive parts manufacturing plant in Miskolc and Panattoni Logistics Park Building A in Mosonmagyaróvár also started.
Activity-Completion was relatively high in all three quarters of 2025 as several projects that started in 2022-2024 reached completion. The value of projects completed since the beginning of 2025 neared HUF 700 billion. For example, this year saw the completion of CATL warehouse and metalworking plant in Debrecen and its surroundings, two BMW factories, and the hangar complex of the Helicopter Base in Szolnok. And Activity-Completion may also remain high in the last quarter of this year.
Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)
On a quarterly level, the value of started construction projects in the second quarter of this year has been the second lowest since 2020 and the Activity-Start of EBI Construction Activity Report Hungary at current price did not reach HUF 470 billion. In the first half of the year, projects entering construction phase were worth around HUF 1,200 billion, far below the previous years and close to H1 2020 when the pandemic hit.
EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). Inquiry and price offer for the report.
Building construction performed poorly in Q2 2025
In Q2 2025 the value of building construction starts fell below HUF 400 billion, barely reaching half of the Activity-Start of Q1. After 2020 it was only in Q3 2024 when the value of construction starts was at a similarly low level. The decline in building construction was even more pronounced at constant price: Activity-Start of EBI Construction Activity Report at constant price was last lower in Q1 2015 than in Q2 this year.
Such a poor performance in building construction occurred despite the extremely successful quarter in multi-unit housing construction. The Activity-Start for non-residential construction fell to a critically low level not seen since Q1 2015, below HUF 120 billion. At constant price, the decline is even more drastic, the value in Q2 2025 was less than half of the previous negative record.
The largest building construction projects during Q2 2025 were mostly multi-unit housing ones. Only one non-residential project made it to the list of the biggest projects, Phase 1 of Halms automotive parts manufacturing plant in Miskolc.
Better Civil Engineering Activity-Start, but still at a low level
Q2 2025 saw an improvement over Q1 in Civil Engineering Activity-Start of EBI Construction Activity Report, but projects started only at a value of around HUF 100 billion. In the road and railway construction segment, there was an increase in Q2 2025 against Q1 with projects entering construction phase on HUF 50 billion, a level not considered high.
The biggest civil engineering projects launched in Q2 2025 include the railway infrastructure of the Ivancsa industrial-innovation development area, the XIV/A water shaft in Tatabánya, and the development of the drinking water networks in Ács, Bábolna and Koppánymonostor.
The capital city has the highest share in total Activity-Start
Looking at construction projects launched in the past four quarters, Budapest had the highest value with a share of 34% in total Activity-Start. It still exceeds the 20%-30% typical of the period between 2021 and 2023.
In the previously leading Northern Great Plain, 16% of projects started. The share of Southern Transdanubia was 15%, and that of the Southern Great Plain was 11%. The lowest values were registered in Northern Hungary and Western Transdanubia during the period, with a share of 4% each. In Central Transdanubia and the Pest region, a respective 8% of projects were launched.
Favourable trend continuing in multi-unit housing construction
Q2 2025 far exceeded the average of recent years in terms of the value of construction starts: multi-unit housing constructions started at HUF 250 billion at current price. This is an absolute record, the second highest value after Q1 2025 registered since 2014. Activity-Start of EBI Construction Activity Report in the segment exceeded HUF 200 billion for the third consecutive quarter, way more than the previous highest HUF 144 billion until H1 2024. The expansion was also significant compared to previous years, even when calculated at constant price.
The momentum fuelled so far by maturing government bonds and interest payments may continue this autumn with the launch of the Home Start Program (providing first-time home buyers with a fixed-rate loan of up to HUF 50 million at a 3% interest rate). Also, this autumn, projects financed by the Housing Capital Program this year (a government initiative to help the supply side) may also appear among sold homes. As a result of these, a pick-up in both demand and supply is expected for the rest of the year. In Budapest, the projects of the Housing Capital Program may be the source of a further high level of Activity-Start. In the countryside, more multi-unit housing projects may start due to the livelier demand thanks to the launch of the Home Start Program. In the capital city, the number of available new homes is already at one of the highest levels in recent years because of the previous significant construction starts. This, in addition to the new supply, may make developers more cautious with project launches as the end of the year approaches.
The value of completed multi-unit homes in Q2 2025 was around HUF 90 billion, a slight increase compared to Q1. Overall, Activity-Completion of multi-unit housing constructions slightly dropped in the first half of the year compared to the previous year, remaining roughly at the 2023 level.
Looking at the past four quarters, Budapest has had a massive share in multi-unit housing constructions entering construction phase (75%), while none of the other regions reached 10%. In Central Hungary 77% of such projects started and in Western Hungary 14%, while only 9% of the Activity-Start was registered in Eastern Hungary.
Hotels in focus: the year started off sluggishly for projects, but growth is visible
Hotel construction works boomed in 2019-2020 most, but projects also commenced in 2021 and 2023 at relatively high values. 2024 saw a slight decline, and this year also started rather sluggishly. The second quarter brought some expansion, though; between April and June 2025, the total value of construction starts in the segment was over HUF 20 billion, a major improvement compared to the previous, very weak quarter, and roughly the same as the median for the period between 2023 and 2025. At constant price, we also see that Activity-Start of EBI Construction Activity Report in Q2 2025 does not differ much from previous quarters but is far behind the high values between the end of 2019 and the beginning of 2021. The largest started hotel projects in H1 2025 included Phase 1 of Staybridge Suites Hotel in Budapest and the MCC Talent Development Center project in Miskolc.
Several hotel projects that were launched in previous years have now reached completion. In Q2 2025, Activity-Completion in the segment set a record, approaching HUF 90 billion at current price and exceeding HUF 160 billion at constant price. For example, the 4-star hotel next to the Balaton Park Circuit racetrack and Le Primore Hotel in Hévíz have been completed.
Also, many hotel projects are currently underway which are due for delivery next year, such as the renovation of the Grandhotel Galya in the countryside, and a number of hotels under construction or under renovation in Budapest: Sofitel Budapest Chain Bridge, hotel in Kígyó street, VP36 Boutique Hotel, Paulay Opera Hotel, Hotel Paulay (Puro), Moxy Budapest Downtown by Marriott, and Hilton Garden Inn. Hotel Gellért in the capital city is also undergoing renovation and may be completed in 2027. Klotild Palace St. Regis Hotel and K36 Hotel and Student Hostel are also nearing completion and could open this year.
Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)