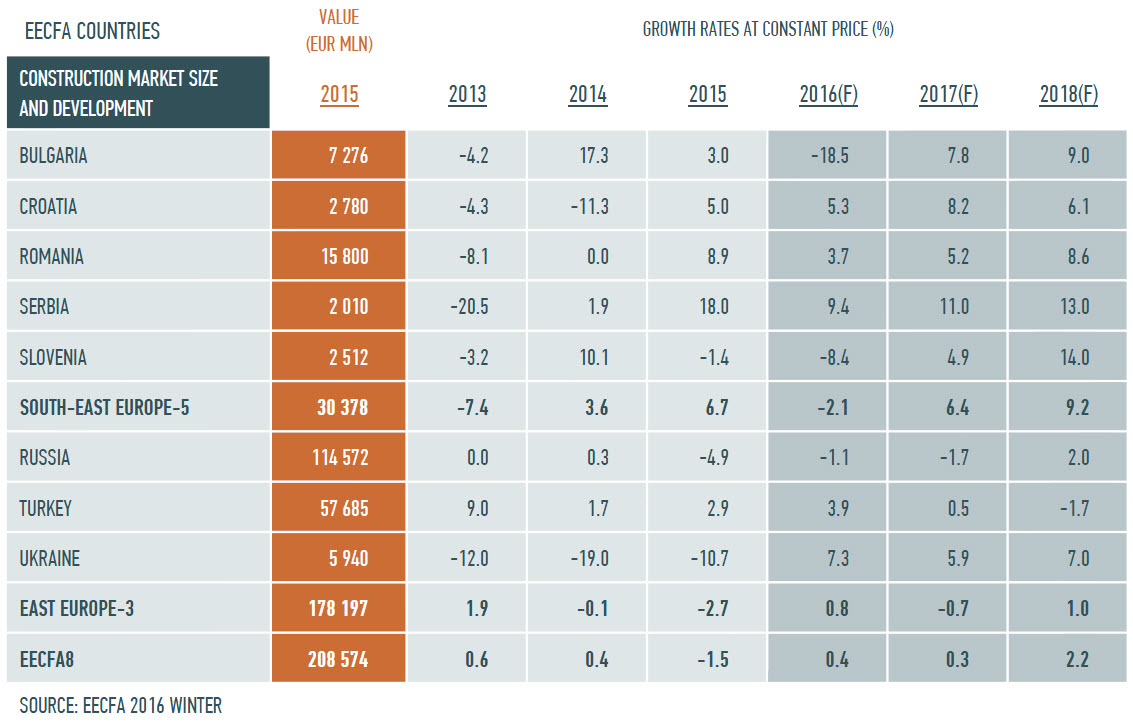
The 2019 Winter EECFA Construction Forecast Report has been released. It can be purchased, and a sample report can be viewed at www.eecfa.com. EECFA (Eastern European Construction Forecasting Association) conducts research on the construction markets of 8 Eastern-European countries.
Southeast Europe
Building construction market of the Balkan countries of EECFA is in prosperity phase. In the 2016-2019 period the market size expanded by 30%. We think that the current cycle is getting closer to the peak and for the upcoming 2 years we foresee a deceleration. One extreme is Serbia’s building construction market. It well outperformed the rest of the countries in the past 4 years and hardly sees any further expansion. As we are getting closer to the end of the current EU programming period, the civil engineering submarket is projected to contribute more positively to total construction market growth.
Bulgaria. Construction output in Bulgaria continues its recovery as both building and civil constructions are contributing. Residential construction is boosted by increasing real wages and low interest rates on housing loans which make buying a home more and more affordable. Persistent demand for contemporary office premises, along with the ongoing expansion of industrial and warehousing projects, will likely continue to be a tailwind for non-residential construction in 2019-2021. Civil engineering construction is forecasted to continue its upward trend in line with EU fund absorption. Growth here in the upcoming years will be fuelled by large transport infrastructure projects and the public utility sector. Total construction output is set to grow by 8.7% in 2019, and to add another 6.5% in both 2020 and 2021.
Croatia. Construction in Croatia is in transition. Some sectors are reaching the limits of catch-up growth. Others are only now beginning to benefit from it. While the direction and inevitability of this transition is clear, the timing is less so, with each sector likely to follow its own, unique path. This said, certain factors, among them emigration, the slowness of key reforms (especially regarding the judiciary), rising construction costs, the government’s ability to secure EU and other official funds and increased international competition for the tourists on which, for better or worse, Croatia’s economy relies, will affect all construction sectors. The outlook is by no means grim. Croatia is not nearly done with its transition, certainly not as far as construction is concerned. Many opportunities remain.
Romania. Romania’s construction subsectors have seen different trends. Residential and non-residential have been on a growth path for several years, while civil engineering has been declining since 2015. Residential construction should remain the main contributor to growth in the forecast period on the back of increased income and high demand for new construction, though regulatory and tax changes have slowed down the subsector. Romania’s economic growth, one of the strongest in the EU, and increased public consumption are feeding the need for new non-residential construction; however, increased skilled labour shortages and costs keep the segment in check, hindering development. For civil engineering, increased construction costs, elections and government changes counter much of the potential growth. Overall, construction across Romania is predicted to expand by 6.4% in 2019 but switch to a lower gear in both 2020 and 2021.
On
24 June 2019, the 2019 Summer EECFA Construction Forecast Report up to 2021 was
published. Full reports can be purchased, and a sample report can be viewed at www.eecfa.com. EECFA (Eastern European
Construction Forecasting Association) conducts research on the construction
markets of 8 Eastern-European countries.
Southeast Europe
Good years are predicted to continue in the construction markets of Eastern and Western Balkan countries of EECFA. Altogether around 15% cumulated real growth is foreseen for the region as a whole in 2019-2021. The annual pace of growth, however, is gradually decelerating on the forecast horizon. In this upcoming period civil engineering is expected to outperform building construction in all countries, except for Romania.
click to enlarge
Bulgaria’s construction output remains on a growth path since both building construction and civil engineering continue to expand. Residential construction is still an attractive investment due to increasing profitability on the back of a positive change in disposable income and low interest rates. Growth in non-residential construction is backed by the acceleration in office segment and a stable performance in manufacturing and warehousing. Civil engineering is to be driven by road and public utility segments, while major projects in railway construction are struggling to start. Construction output is projected to grow by 5% in 2019 and 4% in 2020. The end of the EU programming period of 2014-2020 will likely give and additional boost of 7% in 2021.
Construction in Croatia is at a crossroads. Some sectors that have shown strong catch-up growth will soon slow. Others, so far less favored, will soon benefit from such growth. The country is also at a crossroads in another sense. An aging population, continued emigration, rising construction costs and increased international competition for tourists will threaten a number of construction sectors unless wise political choices are made. All in all, though, while the forecast for the Croatian construction industry as a whole is not as sunny as it once was and while patches of cloud have begun to appear in some places, other areas are expected to enjoy significantly more favorable conditions than in the past.
Romania’s construction is set to grow by 6% in 2019. Residential construction, after a remarkable growth between 2016 and 2018, might be hindered by legal and policy changes. Despite some concerns over the contrary, residential activity is still predicted to remain one of the main drivers of the Romanian construction market, at least until 2020. Demand remains high for most types of non-residential construction as well. But talent shortages and higher operating costs would, likewise, limit the growth of the segment. Of notable interest is the expected growth in civil engineering segments which considerably dropped after 2015 but are to return to a positive trend with renewed interest due to availability of national and EU funding and increased public interest in the election years.
In Serbia the booming cycle is now encompassing practically all construction segments, with strong performance in both buildings and civil engineering. While residential and non-residential buildings were leading the growth in the previous period, civil engineering is expected to again take charge in 2019. With increased spending in road construction and major large-scale projects now underway in energy and railroad, there is a strong expansion of outputs in this forecast horizon. Although extensive growth in previous years already doubled outputs in many segments, particularly in buildings, there is yet more to come. Total construction output in 2021 will likely at least double the volumes from 2015.
Construction industry in Slovenia continues to grow fast, recording a second consecutive year of double-digit growth. Based on strong economic growth, easy access to credit and strong demand for residential housing, its foundation would remain strong also in 2020 unless a major external shock reversed the current optimism on the market. Even in such case, there are several large civil engineering projects, especially the construction of a new railway towards Port Koper that began in early 2019, that will induce growth in construction output for several years.
East
Europe
The East-European countries EECFA covers show a completely different picture from that of the Balkan. The cumulated growth expectation of the region is -1% for 2019-2021. Turkey’s construction market is in such trouble as previously predicted, and this drags down the whole region’s performance. On country level, only Turkey sees negative cumulated growth until 2021, while Russia is prognosticated to be moderately positive. And Ukraine can reach the highest growth rates. In each country civil engineering is forecast to perform better (less worse in case of Turkey) than building construction until 2021.
click to enlarge
In 2018 Russia’s construction output registered a higher-than-expected growth of 2.4%, thanks to the partial revision of construction statistics and the completion of major infrastructure projects related to the FIFA World Cup. In 2019, though, with the disappearance of these two growth factors, construction output is set to be near zero. Forecast for 2020-2021 is more optimistic (2.8%-3.3% per year) as economic growth is expected to accelerate and state funding for the industry will likely have a major push. Civil engineering and housing construction will enjoy most state funding directed to new road and railway projects, energy infrastructure and residential real estate developers.
In August 2018 the economy of Turkey trembled owing to the massive depreciation of Lira that greatly hit many sectors, especially construction. Building permits also dropped sharply last year, after historical peaks a year earlier, but completion of buildings in terms of floor area rose by 5%. This trend continues in 2019, but housing sales declined by 20% in the first five months, together with large decreases in real housing prices.Further, building material output registered a more than 20% drop within a year until May 2019. Construction companies experience a hard time and those active in civil engineering have decreasing workloads due to the presidential decree (issued in October 2018) not to tender new projects except for priority ones. Plus, the budget to central and local governments for projects this year is less than last year. Against this backdrop, recovery in the construction sector can only begin in 2021.
The Ukrainian construction industry has all the conditions for a sustainable growth in the future by an estimated 6.8% rise this year, a 3.6% increase in 2020 and a 7.2% growth in 2021. A positive trend is the systemic state support for the industry, including more transparent and clear rules of the game in the construction market, simplification of permits, and powerful investment support, especially in civil engineering. Hindering construction industry, and the economy as a whole, though, is the lack of financing. The slight drop in residential construction is offset by the growth of non-residential and civil engineering subsectors.
____________
Source
of data: EECFA Construction
Forecast Report, 2019 Summer
Written by Dejan Krajinović, Beobuild Core D.O.O., EECFA Serbia
Left: Business Garden; Top right: Sirius Business Center; Bottom right: Green Heart Source: Beobuild Core D.O.O.
Office has been struggling to sustain steady growth as its output performance surprisingly meandered in the previous period. Finally, investments are picking up, but will it be enough to improve market conditions?
Office construction
Although Serbia’s office segment has been enjoying positive developments during the ongoing expansion, its performance has been rather bumpy and below market expectations. The initial strong recovery of construction outputs in 2016 had a short breath and corrected back by a double-digit margin in the following year. This was not expected in any way since permit numbers continued surging unabated, while investment-wise all market conditions improved further.
Find out more about office construction in the EECFA Serbia Construction Forecast Report. Sample report
The sudden decrease in 2017 was largely caused by the delay in two major planned projects in Belgrade which had received their permits, but construction start did not follow as planned. With its small base and still recovering outputs, this was enough to produce a significant delay in new deliveries and sway outputs of the entire segment.
Weak office stock growth during the last decade – Source: Beobuild Core D.O.O.
Unlike other regional centers, the Belgrade market is still underdeveloped and substantially behind in stock size owing to a delayed transition and the lack of institutional funds and developers from the EU that already invested in Central and Eastern Europe. Because the downturn of 2008 and 2009 reduced financing, most office projects have been developed in a pre-leased manner, thus keeping vacancy at a constant low and rents at a stable high. Consequentially, the costs of renting class A office in Belgrade can go 40% higher than its regional peers such as Zagreb or Sofia.
The construction of office buildings has again accelerated in 2018 and 2019, and the project pipeline is slowly entering realization, meaning that new deliveries should start increasing the modern stock by a significant rate in the coming period and vacancy could also temporarily increase. Having in mind the very propulsive take-up figures in the last three years, there is no fear of a prolonged vacancy at the moment. Belgrade is the largest market and there was only 10.000m2 of new stock delivered in 2018, making a tiny contribution to the total of 860.000m2.
On the other hand, several larger projects entered realization in the same period, so another GLA 120.000m2 is under construction in Belgrade and will enter the market in H2 2020. The gap between demand and supply is already very wide and although bigger projects entered construction, it will take time for new offices to become available. Furthermore, most new projects will be leased before or during construction, so, the effect, if any, on the rent costs should be very limited in this cycle. Pressures on the demand side are set to remain strong in mid-term, so more investments will be necessary if Belgrade is to keep its regional competitiveness.
EECFA (Eastern European Construction Forecasting Association), conducting research on the construction markets of 8 Eastern-European countries, released its 2018 Winter Construction Forecast Reports on 5 December 2018. Key findings are summarized below. Full reports can be purchased, and a sample report can be viewed at www.eecfa.com.
In many previous forecast rounds we have argued for a soft-landing scenario in Turkey. However, the dramatic fashion of the currency depreciation in summer 2018 unearthed many structural problems of the construction industry and made us revise our forecast to an even more pessimistic one. Unlike the stop-and-go like reactions to previous crises, we tend to believe in a stop-and-stay scenario this time. In Russia, we are less pessimistic thanks to a recently announced governmental program expected to affect the market positively.
Optimism still prevails in the Eastern and Western Balkan countries of EECFA. For the region as a whole the new forecast sees just a little downward revision. However, on country level, the stories are different. Less optimism in Croatia and more optimism in Serbia and Slovenia compared to the previous forecast round. In Romania, the largest construction market of this region, the outlook of the building construction submarket has been adjusted downward.
Bulgaria. Construction output in Bulgaria is speeding up with an expected growth of 7.4% in 2018. Residential construction continues to expand on the back of increases in economic activity and real disposable income, and historically low interest rates on housing loans. Additionally, the non-residential segment is also predicted to grow driven mainly by office and industrial constructions. Civil engineering construction has continued its recovery path in 2018, Continue reading EECFA 2018 Winter Construction Forecast
Written by Dejan Krajinović, Beobuild Core D.O.O, EECFA Serbia
Residential construction in Serbia is performing extremely well, and the long-awaited recovery is now well underway, with 2018 volumes again surpassing initial expectations. The situation on the market has been brewing for some time, with a strong investor confidence as well as very favorable financial conditions fueling expansion.
There has been a steady growth in construction activity for 4 years in a row now, but this trend has all the necessary conditions to sustain these levels and produce more growth in the coming years. Housing construction is flourishing, being already one of the best performing sectors in the overall building construction.
New projects are lining up, boosting permit numbers to record levels. Although it is expected for permits to hit the roof in 2020, the amount of permitted homes will certainly drive this growth cycle for several more years.
Serbia’s residential market though is coming from a very low-end of its potential – hitting historical bottom after a long and very deep recession that ended in 2014. With such a small basis at the time, an upswing was expected in construction volumes, but the current strength and speed of the recovery seemed too optimistic.
Investment activity has accelerated, with the strong contribution of both domestic and foreign investors, creating a real boom in the construction of multi-unit buildings. Investors from around the world have already entered the market, particularly Belgrade’s starved luxurious segment and yielding high-end residential projects. The competition of large-scale projects by international and domestic investors is bringing a whole new level of market sophistication, with different services, features and amenities.
The most notable is the Belgrade Waterfront development, a large-scale re-urbanization of the banks of the Sava River in Central Belgrade, covering 80ha of prime construction land. This project is a joint venture of the Republic of Serbia and Abu Dhabi-based investment fund ‘Eagle Hills’, estimated to be worth more than EUR 3bln. Continue reading From gloom to boom: Serbia’s residential
The Eastern European Construction Forecasting Association (EECFA) – the forecasting association conducting research on the construction markets of 8 Eastern European countries – has released its 2018 Summer Construction Forecast Reports up to 2020. The main findings of the reports are summarized below. The full reports can be purchased, and a sample report can be viewed at eecfa.com
Construction up to 2020 in ‘South-East Europe-5’ (Bulgaria, Croatia, Romania, Serbia, Slovenia)
The region is posting a strong economic growth which is fuelling building construction. Some of the region’s housing markets are seeing record-breaking results, so the first voices for overheating appeared. We think these markets are far from it, though. At the same time, construction labour shortage, due to economic migration from these countries to Western Europe, is one factor giving cause for concern in the future. With accelerating absorption of EU funds, civil engineering is expected to contribute positively to growth all the way on the forecast horizon.
Bulgaria
Construction output in Bulgaria continues its recovery and is expected to reach an 8.8% growth in 2018. The star performer is the residential construction segment, benefitting from improved employment and real disposable income, as well as the ongoing process of the concentration of population in big cities. Additionally, the steady economic development will increase investments in non-residential projects. Civil engineering construction is forecasted to contribute strongly in the next few years after EU fund absorption started catching up. Therefore, estimations for 2019 and 2020 are for an additional growth of 7.1% and 6.0%, respectively.
Croatia
Croatia’s construction output is likely to grow at a respectable rate until 2020 (by an estimated 2.2% in 2017 and a forecast 11.6%, 6.2% and 4.0% in 2018, 2019 and 2020, respectively). Particularly well performing sectors include hotel construction, education and health and certain civil engineering subsectors, especially railways. A global trade war, fallout from the Agrokor crisis and rapidly rising construction costs are threats to Croatia’s construction industry. And all are now significantly more likely to occur than they were at the time of EECFA’s 2017 Winter Report. But fortunately, none yet constitutes an imminent danger. In 2021 or soon thereafter growth will probably begin to tail off in a number of important sectors as Croatia’s catch-up phase gradually comes to an end, but exactly when and how this will occur is not yet clear.
Romania
The housing and non-residential segments are set to continue their excellent performance in 2018, and, in spite of an underwhelming performance in the civil engineering segment, the total growth of the construction sector in 2018 is forecasted to reach 7.1% (up from +6.8% in Winter 2017). As projects co-funded by the EU are starting to be implemented, Continue reading EECFA 2018 Summer Construction Forecast
EECFA (Eastern European Construction Forecasting Association) – the forecasting association conducting research on the construction markets of 8 Eastern-European countries – published its 2017 Winter Construction Forecast Reports on 4 December. A concise summary on the main findings is outlined in this article. Please consider that foreseen development stories are rather different for the 3 submarkets (residential, non-residential, civil engineering) of construction in the countries we cover. In Russia, for example, civil engineering is expected to drive the total market back to expansion. Unless you need only an impression about the total market, we kindly suggest consulting with our reports.
Construction outlook up to 2019 in South East Europe: the countries EECFA dubs ‘South East Europe-5’ are Bulgaria, Croatia, Romania, Serbia and Slovenia. The overall picture is still very optimistic, but the expansion rate of the total construction market has been revised a bit downward, mostly due to the worsened expectation in EU fund absorption on the forecast horizon. This affects largely the civil engineering submarket, where 9% cumulated growth is foreseen for 2018-2019 for the region as a whole. In a very favorable macro environment where money is cheap, building construction is set to continue to recover; with a 17% cumulated market growth predicted for the upcoming 2 years. Shortage of skilled labour in construction is a major constraint of a more rapid growth, though.
Bulgaria: the country is facing a 7% growth in total construction output in 2017 as EU funds of the new cycle are fuelling civil engineering construction which dragged down the whole sector in 2016. Thus, total construction output comes from a very low level; in 2016 it nosedived by 35.2% (compared to the forecasted 31.1%). In 2018, the construction sector is set to register a 5.6% increase (as opposed to the 6.4% forecasted earlier), while 2019 should bring a 5.7% rise (up from the +4.5% predicted formerly).
Croatia: the good news for construction growth in Croatia is the country’s increasing capacity to obtain EU funds, at which the current government seems to be getting better and better. Continued strong growth in GDP, private consumption, retail turnover and industrial production should also benefit construction. Total construction output growth is estimated to be 6.3% for 2017, which has been revised down from the 11.2% growth expected in summer due primarily to caution shown by buyers, bankers and developers in the residential segment and to delays in some government-led, civil-engineering projects. Continue reading EECFA 2017 Winter Construction Forecast and Revision
Serbia’s retail segment is enjoying a robust growth in the number of permitted buildings due to the permit reform introduced in 2015. With the first phase of the reform having commenced in 2015, and the second phase having been set out in 2016, the application procedure for permits has been made fully electronic in order to have full transparency. Consequently, not only did Serbia gain a better position in The World Bank’s 2016 Doing Business list, but is now seeing a new investment cycle of the construction of high-volume international-type shopping malls. The start of such several big-league projects should sustain this growth cycle and give a boost to construction volumes in the years to come.
Written by Dejan Krajinović, Beobuild Core D.O.O, EECFA Serbia
Delta Planet, Ada Mall (top row), IPM center, BIG Fashion (middle row), BW Gallery (bottom) – Source: beobuild.rs
In an effort to improve investment climate, permit procedures in Serbia were marked as a one of the main regulatory obstacles to development, with a long line of inefficient procedures and corrupt instances suffocating the economy. Before the reform was introduced, in some cases, it took almost a year to acquire a building permit, even if all legal conditions were met. During 2015, the government presented a multi-phase reform, which would include a total overhaul of the procedures, resulting in far cheaper and much faster permit procedures. Its implementation started in late 2015 and so far, it has been a resounding success, with building permit applications now being processed in just a few days. Furthermore, the second phase of the reform implementation started in January 2016, with building permit applications now a fully electronic system in Serbia. With electronic and centralized applications, the reform aims to lower the number of instances and the possibility of corruption and hush money in the process. This significant regulatory reform helped Serbia swiftly boost its ranks in the World Bank’s ‘Doing Business’ list, and from 91st in 2015 it reached 47th position in 2016, making it one of the most improving economies of the world in 2016.
With some anticipation of investors, new permit procedures resulted in a strong spike of permit numbers across the board. Practically all construction segments have seen their share of growth, but with almost two years into implementation of the new permit laws, some construction sectors are leading the way. It seems that the retail segment forwards as main beneficiary in building construction, with a very potent investment cycle carrying almost 1 million permitted square meters in just over two years. Coming from a very low post-crisis level, this several-fold increase of permitted retail buildings created a real sector’s boom. The reasons behind such a strong reaction of investors lay in a very opportunistic market, open for development of big city malls and retail parks. It is worth Continue reading Serbia’s retail – primed for take off
We have released our summer construction forecast on 16 June 2017 on Bulgaria, Croatia, Romania, Russia, Serbia, Slovenia, Turkey and Ukraine. This post intends to summarize the most important projections for these construction markets for the years 2017-2019. These are our main findings; for a deeper understanding, please consult our reports. You can contact us on eecfa.com.
Outlook for the EECFA regions
The highly optimistic outlook for South East Europe is maintained by EECFA. Leaving behind the transitory 2016, when the absorption of funds available in the new EU programming period (2014-2020) was still at a low level, the upcoming years are characterized by a bigger expansion of the construction market than that of GDP. Building construction is predicted to well outperform the total market, with a yearly average rate of 9% over the horizon. The small growth in the region’s total civil engineering market is attributed to the negative expectations in Romania.
Sideway moves, no further market expansion on the horizon are what we consider the most probable scenario for the 3 East European markets together. Turkey and Russia, being far the two biggest markets we cover in EECFA, is expected to show some similarities. In both countries our forecasts are moderately optimistic in the civil engineering market. While in the building construction market the outlook is clearly negative for Russia and neutral for Turkey. In Ukraine, the recovery experienced in 2016 is predicted to be sustained until 2019. Both building construction and civil engineering could expand further with a relatively good pace. Continue reading EECFA 2017 Summer Construction Forecast and Revision
EECFA has released its winter construction forecast reports on 2 December 2016. In this post you will find the concise summary on our expectations for the 8 construction markets we are dealing with: Bulgaria, Croatia, Romania, Russia, Serbia, Slovenia, Turkey and Ukraine. You can also find us and our reports on eecfa.com.
Regional outlook
South-East Europe is very optimistic. After the transitory 2016, when shrinkage in the civil engineering market in the EU countries of the region dragged down the region’s total performance, high growth is expected to characterize the total construction market in the upcoming years. Each EECFA country of the region predicts an expansion beyond 5% for 2017 and a further increase for 2018. Building construction, coming back from low levels, is predicted to expand faster than civil engineering in 2017.
Eastern Europe is at a standstill as a whole. In Russia, we expect a prolonged decline. The total construction market is not predicted to expand before 2018, and we believe that the growth of civil engineering sub-market can only alleviate the loss awaited in building construction in 2017. In Turkey, our stories for the upcoming years is rather similar to that of Russia, slight optimism in civil engineering, slight pessimism in building construction leads to a total market which is not predicted to grow until 2018. In Ukraine, all-round recovery is forecasted. From the very low levels, we expect relatively high growth rates for 2017 and 2018.