Slovenia’s housing squeeze no one can measure

Written by Dr Aleš Pustovrh – Bogatin, EECFA Slovenia

Slovenia’s housing market is in a curious state. Prices for both new and existing homes keep rising, yet the country still lacks a reliable measure of how far supply trails demand. Official data show steady appreciation across all major cities—Ljubljana most of all—while construction remains hampered by slow permitting, high input costs and a fragmented building industry. Politicians promise a surge in public and affordable housing but estimates of the true shortfall—whether based on household formation, demographics or unmet rental demand—are patchy and inconsistent. The average price per square metre has jumped by roughly 50% since 2021, but the structural imbalance behind this surge is harder to pin down, leaving policymakers to grapple with a problem they can only describe vaguely.

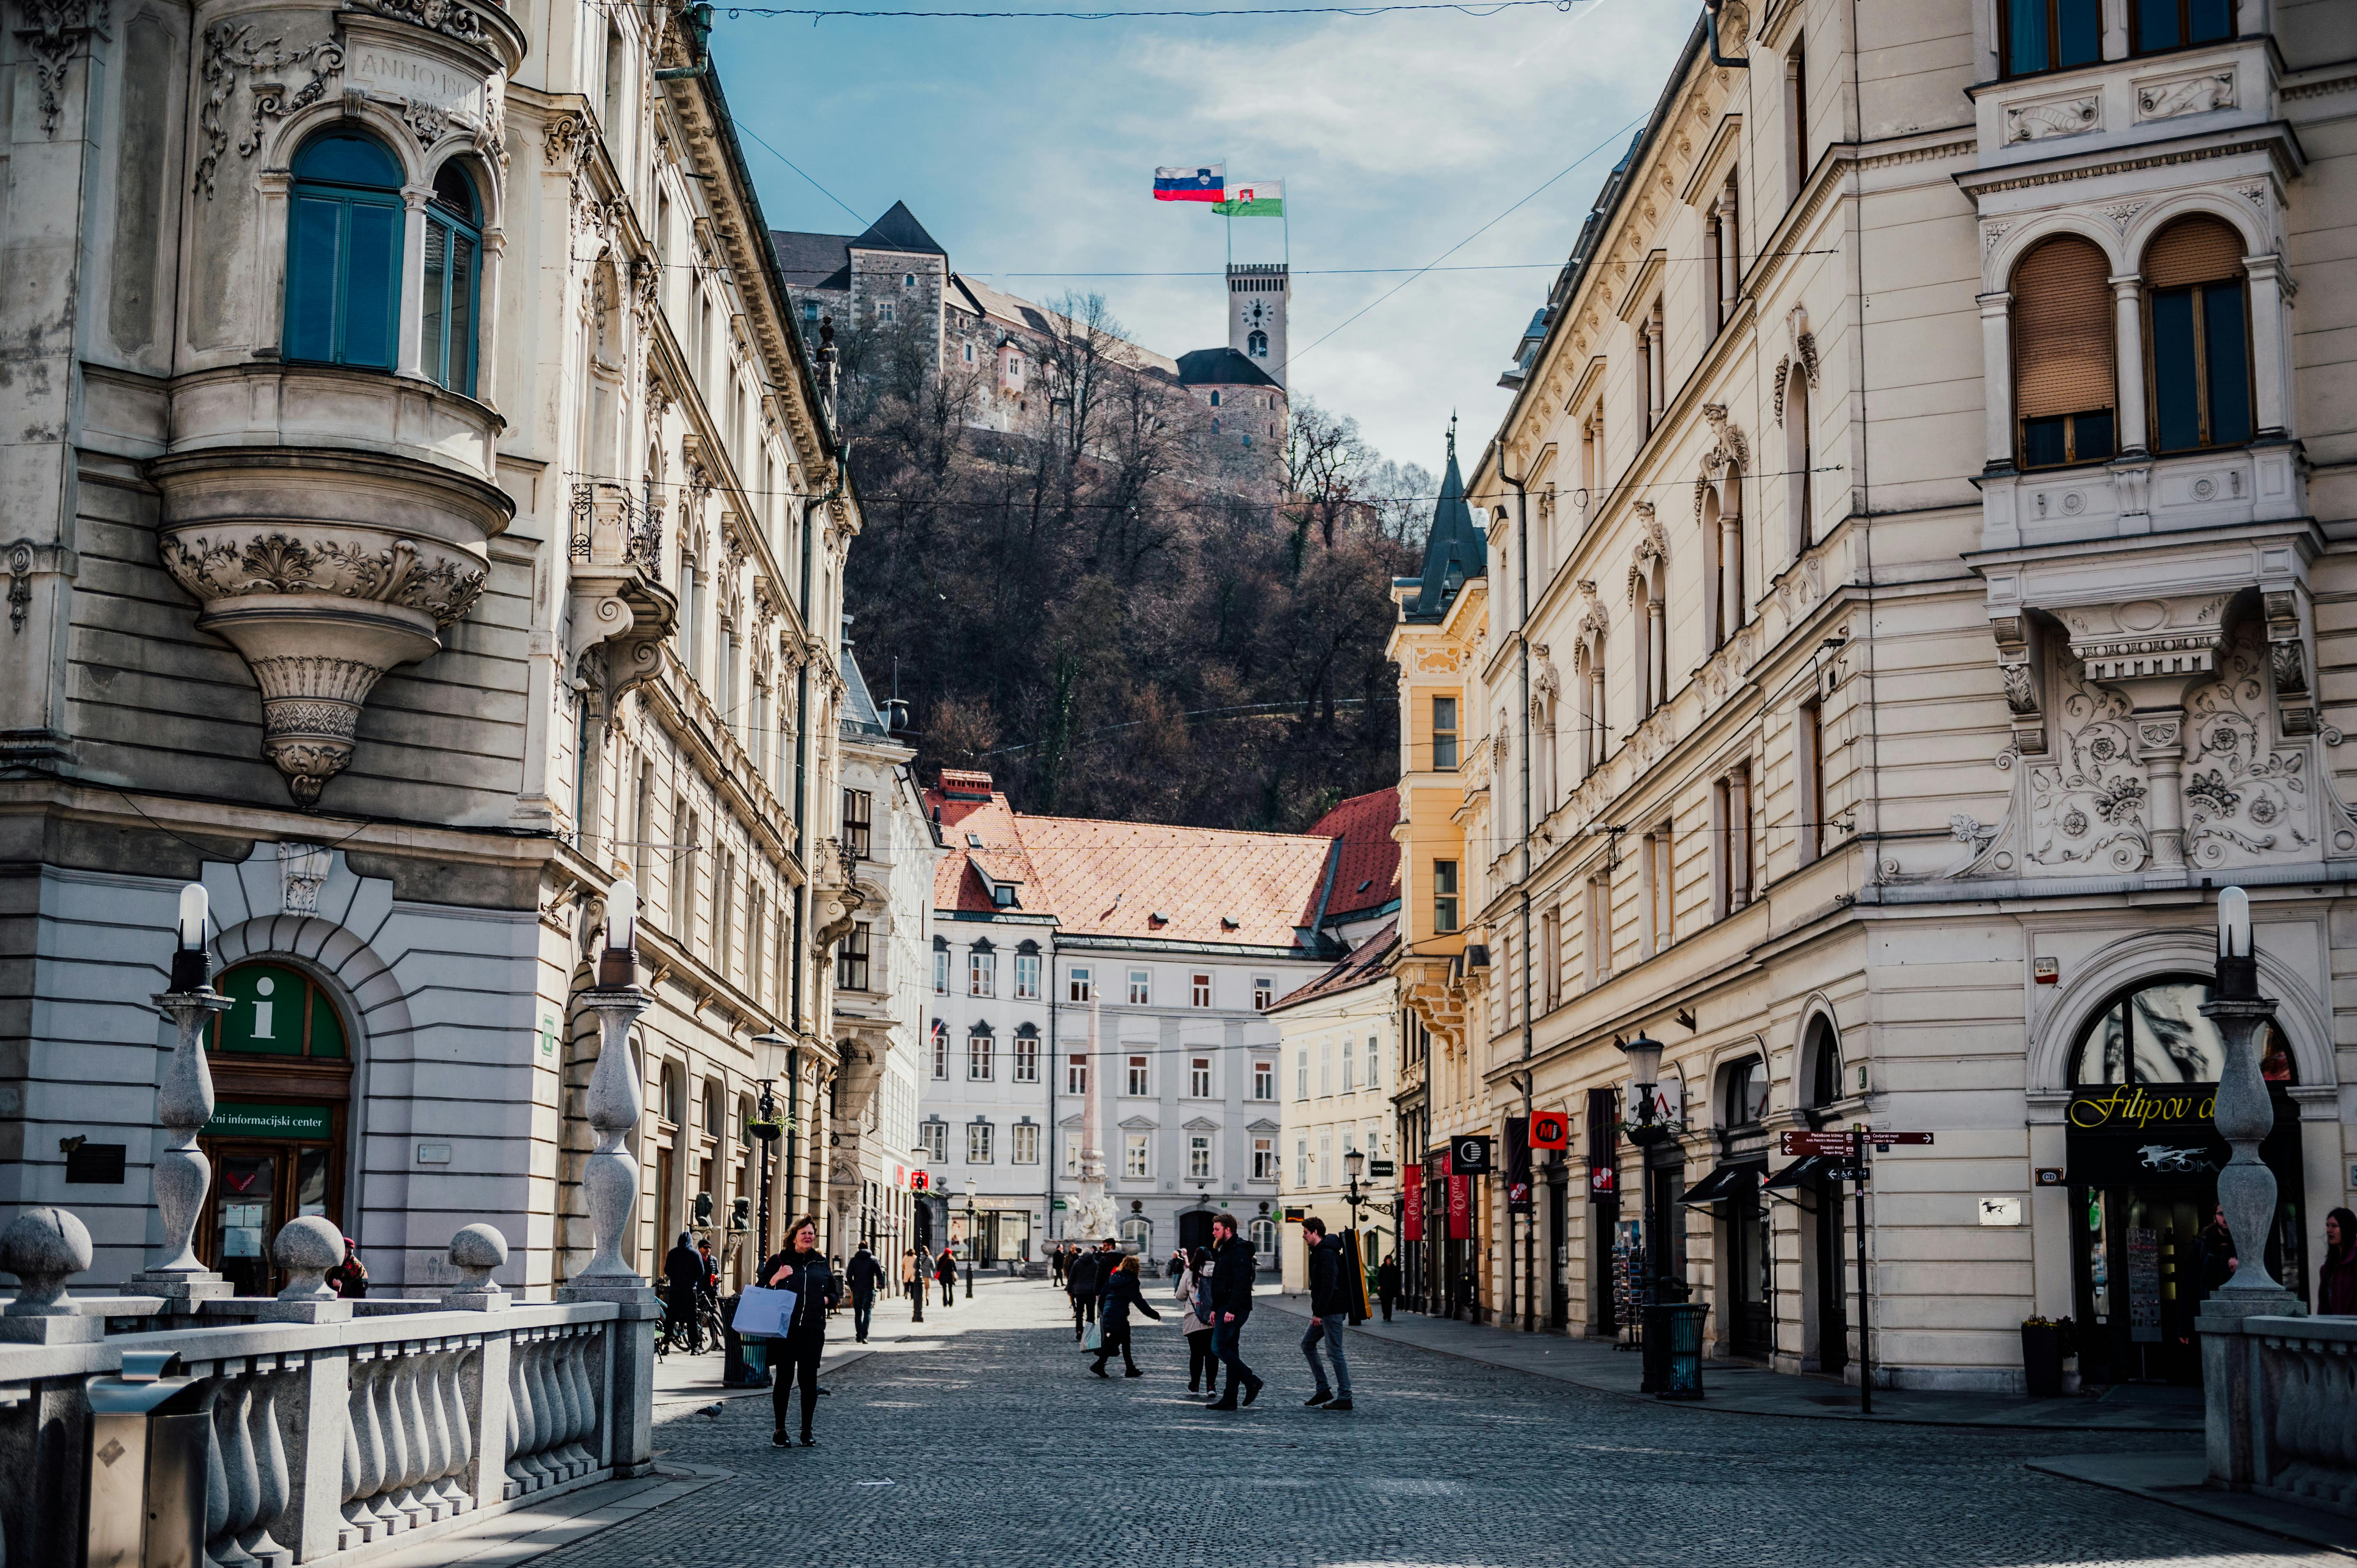
Ljubljana, Slovenia. Photo by Alexander Nadrilyanski on pexels.com

With a general election looming in March 2026, the absence of clear data creates fertile ground for confusion and political spin. The ruling coalition boasts of raising annual public‑housing investment to €100mn, pledging €1bn over the next decade. The public housing fund plans around 2,000 new units in the coming years, with perhaps 1,000 more from other public bodies. Private developers, especially in Ljubljana, are building briskly, too. Given that Slovenia completes about 5,000 homes a year, these additions ought to shift the market—at least in theory.

But the scale of need remains uncertain. In 2021 Slovenia counted 864,300 dwellings for 859,782 households—roughly one per household. Prices, though rising fast, remain below those in some neighbouring countries. The median price of used homes was €3,070 per square metre (nearly €5,000 in Ljubljana), while the average gross monthly wage was €2,500—yielding a price‑to‑income ratio lower than in many EU states. Mortgage credit is widely available and relatively cheap, with interest rates well below 4%. Outstanding housing loans rose from €8.5bn to more than €9bn in 2025, suggesting that many households are managing their residential construction investments without state support.

One of the outgoing government’s flagship measures—a clampdown on short‑term rentals—was meant to push more homes into the long‑term market. It may instead swell the ranks of empty properties: around 19% of dwellings already stand vacant. A straightforward remedy, a property tax to nudge owners to rent out unused homes, was avoided for fear of angering voters in a country where 75% of households own their homes.

The lack of solid data allows politicians to champion measures unlikely to achieve their stated aims, while sidestepping those that might work but would prove unpopular. Election season is rarely conducive to sober policymaking, but the next government will need better data—and the courage to act on it—if it hopes to make any meaningful dent in Slovenia’s housing woes.

More on Slovenia’s housing market and housing forecast up to 2027 can be found in the EECFA Slovenia Construction Forecast Report. Sample report and orders: https://eecfa.com/

EECFA 2025 Winter Construction Forecast

EECFA released its 2025 Winter construction forecast on 12 December. Check out a sample report and place your order on eecfa.com. For discount, please contact us.

Southeast European construction markets

“Bulgaria’s total construction output is forecasted to increase by 3% on average for 2026-2027” – says Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian research institute. He adds that this is to follow estimates for a similar performance of almost 3% in 2025. The sectoral background, however, shows, a nuanced picture – cooling of residential construction, positive news from non-residential and a robust performance of civil engineering. The latter will benefit from investments which will be backed by the absorption of EU funds through the Recovery and Resilience Plan (RRP) and classical operational programmes, both with implementation deadlines in 2026 and 2027. At the same time, Bulgaria’s economy is to expand by 2.4% on average in 2026-2027 – a period continuously shaped also by the Euro adoption on 1 January 2026.

Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s Croatian members, think that declining dwelling sales in Croatia have, paradoxically, failed to stop the growth in the value of Croatian residential output, because increases in the price per square meter of those dwellings that do get sold have more than compensated for the lower number of square meters bought. “But how long this can continue is unclear” – they add. “The policies that the Croatian government is implementing in order to ease the country’s housing crisis are confusing the residential picture still more, since a number of those policies have contradictory effects on output. As to non-residential building construction, output growth during the period covered by the current forecast will depend greatly on the sector, with some likely to continue to benefit from catch-up growth and EU support for a bit longer and others moving toward a steady state or even a decline. In civil engineering, EU funds continue to play the dominant role in financing construction of all sorts. Sports facility construction is experiencing a boom, but given the speed with which such projects are completed, the effect on output will be relatively brief. Renewable energy construction should be growing rapidly, but regulators’ hostility toward the sector are holding it back.”

“Romania’s economy is entering a challenging period as the recently implemented measures to reduce the national account deficit begin to take effect” – reports Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild. “While most forecasters do not anticipate a recession, economic growth is expected to remain subdued over the next two years. Inflation is the highest in the EU, boosted in 2025 by increases in sales taxes. As a result, consumer prices are rising at a pace that is forecasted to outstrip wage growth, leading to a decline in real incomes in both 2025 and 2026. Government spending is also facing cuts, thus both private and public consumption are predicted to decline, with a chilling effect on most construction activity types. There is also the challenge of the massive level of public investment required by civil engineering projects that have started since 2023, which will be difficult to sustain under the austerity and the mounting pressure of losing even more EU funding. On the brighter side, both the economy at large and the labour market are expected to be quite resilient. By 2027, assuming the deficit reaches manageable levels, the effects of contractionary policies should fade out, inflation could ease, and interest rates could come down. This means that demand for construction would rebound and with it, construction activity.”

Dejan Krajinović, EECFA’s Serbian researcher (Beobuild) says that “Serbia’s overall construction output sank into a negative territory in 2025, primarily owing to the weaker performance in civil engineering. This year recorded growth in building construction, but the substantial consolidation in civil engineering dragged totals in red. The completion of major road, railway and energy projects contributed mostly, but delayed construction starts played a role as well. Residential construction is stable and is on historical levels, while non-residential construction is booming led by the hosting of the EXPO 2027 in Belgrade. Investments into commercial, hotel and office buildings are all spurred by the event, with the purposely built EXPO 2027 complex consisting of numerous venues being the single largest investment in non-residential. Improving financial conditions and sustained demand still support relatively high construction activity, but a lot of global political and economic uncertainties are dimming future prospects.”

Dr. Aleš Pustovrh at Bogatin, EECFA Slovenia, says that Slovenia’s construction sector is holding steady at EUR 6bn, though growth has cooled. Residential buildings remain the anchor, with output expected to show only a slight dip in 2025, helped by strong employment, rising wages and cheaper mortgages. Property transactions rebounded in early 2025, reversing last year’s slump, while prices continue to climb amid land shortages and slow permitting. Public housing programmes are ambitious, but private developers are concentrating on Ljubljana and coastal towns. Non-residential construction is mixed: offices are recovering slowly, retail stays subdued, but industrial and warehousing thrive on export demand and automation while health and education remain at very high levels. Civil engineering and public works lean on EU-backed projects and are anticipated to reach historically high levels by 2026. 

Eastern European construction markets

Andrey Vakulenko at Macon, EECFA’s Russian research institute notes that “the high key rate and the overall economic slowdown are constraining the Russian construction industry with negative trends expected for the current year and over the next two years. An easing of monetary policy, which has already begun, could help normalize the situation, but a positive effect is not expected until 2027. The main drag on construction output will likely be the residential subsector where high rates and revised government demand support principles are reducing activity among both buyers and developers. Negative trends will also likely persist in most non-residential segments due to declining growth rates of budget financing, a general decrease in business activity and a slowdown in consumption. The overall descending dynamics in the construction market may somewhat be mitigated by stable growth in civil engineering driven by export projects in energy and transport, but this growth is not predicted to be enough to keep the construction market in a positive zone”.

Prof. Ali Türel, EECFA’s Turkish researcher, reports that “the major effect of inflation-curb policies in Türkiye is the decline in disposable income and in the purchasing power of wage earners and pensioners. The moderate to lower-income population is unlikely to save enough equity for buying a home when rents have also become unaffordable for many. Ironically, housing sales have been increasing at a much higher rate than the growth of households. This can be attributed to the typical trend in Türkiye, where, during inflation, people expect a higher real return on their financial assets from real estate investments compared to alternative investment options. The reconstruction of earthquake-damaged buildings and infrastructure also contributed to the high rate of growth in building starts and completions from Q2 2025 onward, leading to the highest rates of change in the construction sector’s contribution to GDP compared to other sectors. Our latest forecast indicates that total construction output in Türkiye may reach 6.4 trillion TL in 2027 (EUR 180 billion), all at 2024 prices.”

According to Prof. Sergii Zapototskyi of Uvecon, EECFA Ukraine, despite the war and high risks, Ukraine’s construction industry remains one of the key drivers of economic recovery in 2025. The RDNA4 (the latest Rapid Damage and Needs Assessment Report) estimates Ukraine’s reconstruction needs for the next decade to be USD 486-524 billion, creating long-term demand for residential, non-residential and civil engineering construction works. Major challenges persist, including the uncertainty regarding the duration of the war, especially in frontline regions, labour shortages, bureaucratic barriers in the urban planning legislation, and logistical constraints due to the relocation of production facilities, and often, shortages in building materials. At the same time, the industry is demonstrating resilience: developers are diversifying supply chains, stabilizing procurement schedules, and increasing activity in the Central and Western regions. Demand for housing, intensive infrastructure restoration, and international investment from the EBRD, EIB, and other partners continue to support positive dynamics. The sector’s development prospects for 2026-2027 will largely depend on the security situation and the effectiveness of state recovery programs.
Housing needs of internally displaced persons in Ukraine

Written by Sergii Zapototskyi – UVECON, EECFA Ukraine

The full-scale invasion of Russia caused a deep humanitarian crisis and exacerbated socio-economic disparities in Ukraine. One of the key challenges is to provide homes for internally displaced persons (IDPs). The mass movement of the population created a shortage of affordable and temporary housing as the infrastructure was not ready for such a load. The government is already working on a new housing policy, which might also help resolve the issue of housing for IDPs.

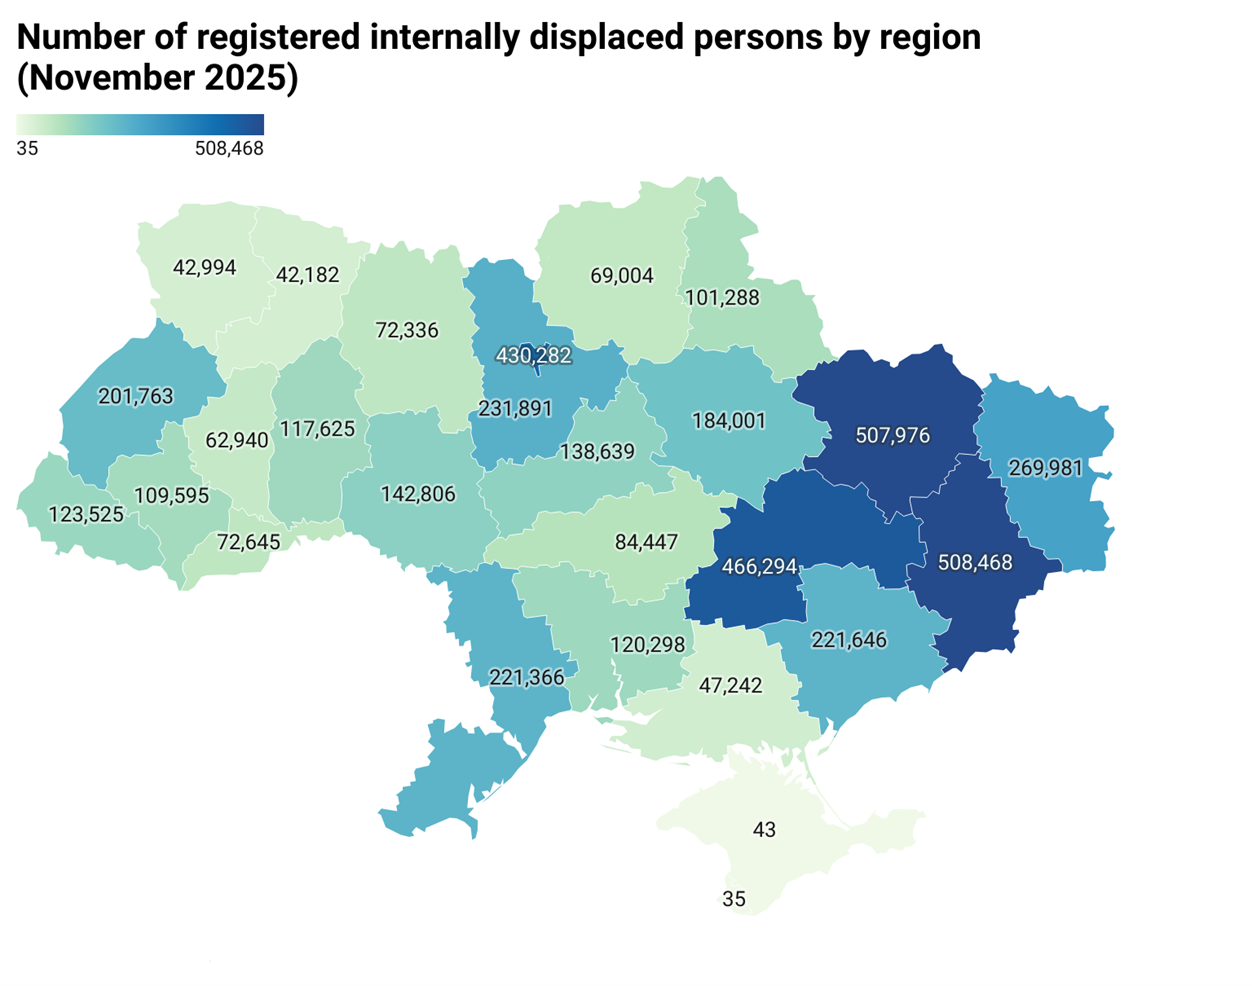
Source: https://www.ioc.gov.ua/analytics/dashboard-vpo

Statistics on internally displaced persons

As of 1 November, this year, 4,588,045 internally displaced persons were officially registered in Ukraine, including 838,436 children under the age of 18 [1]. Most IDPS are in Kharkiv region (508 thousand or 11%), followed by Dnipropetrovsk region (467 thousand or 10%), the city of Kyiv (430 thousand or 9.4%) and Kyiv region (232 thousand or 5%). [3]. IDPs in these regions total about 1.6 million people [1]. As per the result of the 16th round of the survey conducted by The International Organization for Migration (IOM, UN Migration), as of April 2024, about 2.7 million internally displaced people were from frontline areas.

Housing damages, needs and solutions

In total, more than 1.3 million Ukrainian households lost their homes because of the war, including not only IDPs, but also residents of settlements that suffered extensive destruction. The World Bank estimates total housing needs in Ukraine between 2025 and 2035 to be USD 86 billion, mostly to finance repair and reconstruction works of the housing stock (estimated at USD 75.5 billion including the cost of clearing rubble at USD 5.7 billion). USD 404.6 million should go to acute housing needs and funding has also been identified for organizational measures (USD 37.5 million) and regulatory and technical processes, including the development of strategies (USD 12.5 million) to coordinate and implement reconstruction programs [4].

Citizens have already submitted over 850,000 reports of housing damage through the Diia app (the national public-services portal) totalling over 60 million sqm of losses. For comparison, in the pre-war period, an average of 9-10 million sqm of homes were completed in Ukraine each year, demonstrating the scale of challenge and need for multi-level solutions in housing policy. Preferential lending programs are unable to solve this situation and cover the housing needs. The ‘jeOselia’ program provided loans worth over UAH 28 billion, but 52% of this went to military personnel, while IDPs received only 566 pieces of loans. In 2024, within the framework of this 3% mortgage program, only 500 families were provided with housing. The situation is even more critical in the rental market as the state program for subsidizing rental housing has shown low efficiency. The majority of IDPs (90-95%) rent homes unofficially, making them vulnerable to unreliable living conditions and unjustified rental charge increases or evictions.

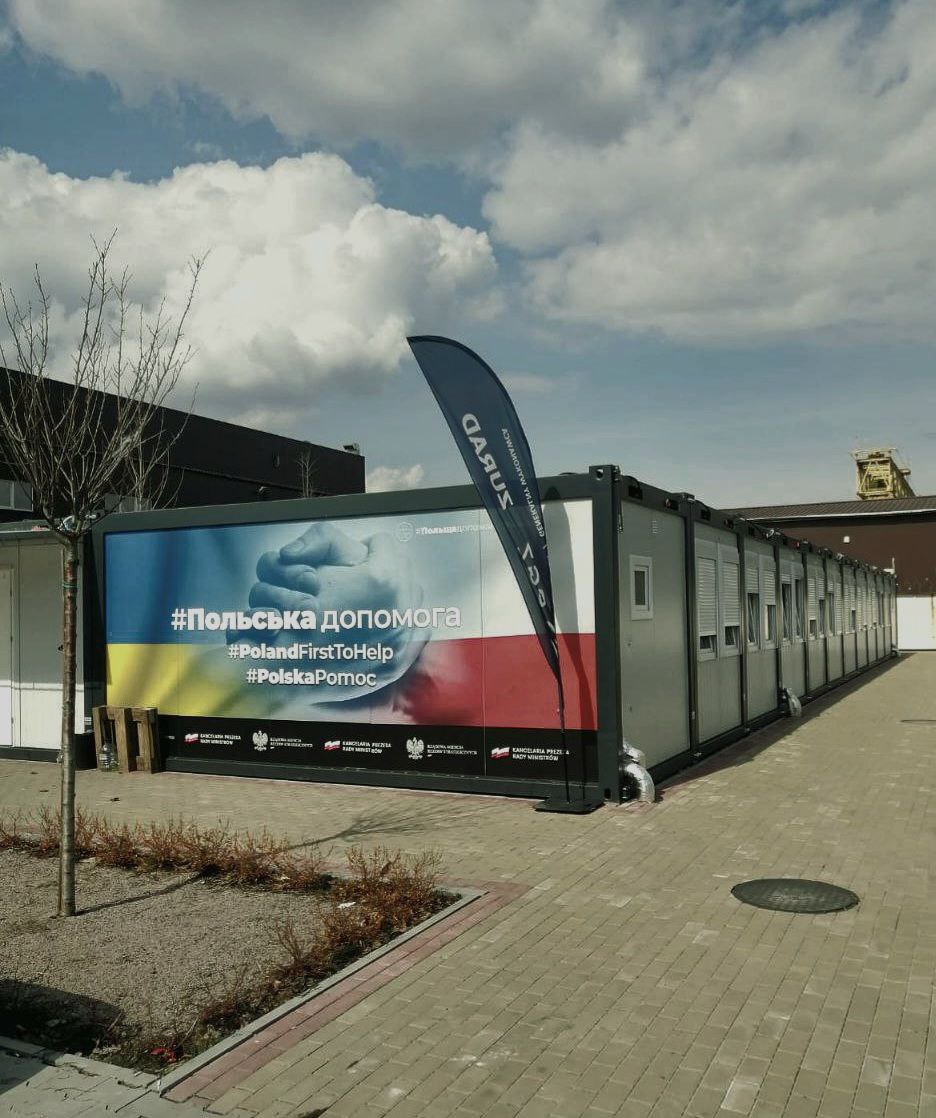
Modular settlement, Borodianka. Photo: Sergii Zapototskyi

Modular settlements are a key temporary housing for IDPs, although living conditions here cannot be considered fully comfortable. Initially, they were meant to be short-term but gradually became long-term housing for many families due to their limited finances. Today, besides the psychological difficulties and discomfort of residents, operating such facilities is also a major challenge. The maintenance of modular settlements, including payment for utilities, repairs and security, falls entirely on local budgets, an additional financial burden for communities which often do not have enough resources to sustainably finance these.

Modular settlement, Bucha. Photo: Sergii Zapototskyi

Housing policy changes

As the problem of providing housing for IDPs is systemic in nature and cannot be solved solely through financial instruments, a comprehensive review of state housing policy has become necessary, particularly the development of an affordable rental housing segment, social programs, and long-term support mechanisms for both IDPs and vulnerable categories of the population in general.

The Ukrainian Parliament is already working on several key legislative initiatives. The central one is draft law No. 12377 ‘On the Basic Principles of Housing Policy’ to replace the current Housing Code from 1983 which does not contain basic concepts for modern housing policy such as social rental housing or housing stock of communal ownership. Draft law No. 4080 is also important on the inventory of the housing stock. In parallel with drafting these laws, necessary by-laws are being prepared to regulate the practical mechanisms for implementing housing policy (creation and maintenance of housing queues, criteria for selecting recipients of state support, and the procedure of providing various forms of housing assistance). In addition, the government’s plans until 2027 include allocating EUR 650 million to the eRecovery Program, EUR 450 million to support IDPs, military personnel and the families of the deceased, creating a social housing fund and introducing a unified state online system for the long-term strategy of social integration and support for vulnerable categories of the population. All this might help resolve housing for IDPs.

Sources:

  1. Internally Displaced Persons. State Enterprise “Information and Computing Center of the Ministry of Social Policy, Family and Unity of Ukraine”: https://www.ioc.gov.ua/analytics/dashboard-vpo
  2. Housing crisis in Ukraine: how to provide IDPs with housing in 2025? International Renaissance Foundation: https://www.irf.ua/zhytlova-kryza-v-ukrayini-yak-zabezpechyty-vpo-zhytlom-u-2025-roczi/
  3. Internal Displacement Report, IOM Ukraine: https://dtm.iom.int/sites/g/files/tmzbdl1461/files/reports/IOM_UKR_GPS_Internal%20Displacement%20Report_Round%2016_UA_June%202024.pdf
  4. Rapid Assessment of Damage and Recovery Needs RDNA4, World Bank Group: https://documents1.worldbank.org/curated/en/099052925103531065/pdf/P180174-93c8e8c1-83a2-487d-aaec-a8435f9db418.pdf  
  5. Cedos, Housing and Residential Conditions in Ukraine: Survey Results, 2024: https://cedos.org.ua/wp-content/uploads/zhytlo-ta-zhytlovi-umovy-ukrayin_ok_rezultaty-opytuvannya.pdf

Aparthotels: new growth spot for non-residential construction in Russia

Written by Andrey Vakulenko – MACON, EECFA Russia

Russia’s resort real estate market has seen a dynamic growth in recent years, partly due to the emergence of aparthotels – a format attractive to both developers and hotel operators. The coming years are also expected to see a sharp increase in aparthotel construction, supporting the non-residential construction market – according to Andrey Vakulenko, EECFA’s Russian analyst.

Thriving aparthotel segment

Resort real estate has been one of the fastest-growing segments of the Russian construction market in recent years. Aparthotels – apartment complexes with minimal infrastructure and services, and with the mandatory availability of a trust management – have particularly seen a rapid growth, though they are relatively new to the Russian market. The core of the supply is (and will be) resort projects, i.e. aparthotels in locations with developed recreational and tourist infrastructure for seasonal vacations. Urban aparthotels – primarily in metropolitan areas with minimal infrastructure – are rather aimed at business travelers and to a lesser extent at traditional tourism and long-term rentals.

As of Q3 2025, the aparthotel market size stood at 25,200 units with a total area of ​​612,500 sqm and by the end of this year, roughly 143,000 sqm of new aparthotels, or 4,300 new units are expected to open. Based on the announced plans, the next three to four years will register a sharp rise, and by the end of 2029 aparthotels may amount to around 109,800 units with over 3.6 million sqm, almost six times higher than the current level.

Behind the growth

One of the main reasons for the anticipated expansion of the aparthotel format is that domestic tourism gained popularity after 2022 due to the reduced accessibility of many international resorts (because of the suspension of air travel, the weak ruble, visa issues, and other internal or external restrictions). Rise in domestic tourism created stable high demand for accommodation in virtually all key resorts in Russia.

Another reason is that developers specialized in multi-unit residential construction began to start many projects in aparthotel and resort real estate construction amid the decline in the residential real estate market following the cancellation of the mass preferential mortgage program.

Also, there are significant incentives and state support for developing tourism infrastructure and the domestic tourism industry, including the construction of hotel complexes and aparthotels.

Furthermore, in 2024 the status of aparthotels was legalized; they were included in the official hotel classification system, creating uniform standards for the segment and transparent conditions for market participants.

Besides, the departure of many large foreign hotel operators from the market in 2022 led to the expansion of Russian hotel chains (Azimut Hotels, Cosmos Hotel Group, Alean Collection, ZONT Hotel Group, VALO Hotel Services, Mantera Group, among others), which began collaborating with aparthotels, increasing the latter’s attractiveness and guaranteeing a high level of service and trust management services.

Moreover, many investors appeared in the market who found the trust management model used in aparthotels and the opportunity of generating passive income attractive. The operating return on investments in aparthotels in developed resorts managed by well-known hotel brands can reach 7%-10% and higher. And given the rise in the market value of apartments, long-term returns can reach 13%-17% per annum, exceeding the return on long-term bank deposits (currently 8%-10% per year for a three-year deposit).

All this suggests that aparthotels will be a major segment of non-residential construction in the coming years.

Coastal regions: top locations for aparthotels

The aparthotel format is developing most actively on the Black Sea coast, currently accounting for over half of the total supply in this segment. Urban aparthotels are primarily in Moscow and St. Petersburg with just over one-fifth of the total supply.

In the coming years, it is also the Black Sea coast that will likely register the biggest expansion in supply, but new aparthotels are also set to be actively emerging on the Caspian Sea coast, in Dagestan.

In coastal regions (Krasnodar Krai, Crimea, Dagestan), aparthotels under construction already amount to more than a quarter of all multi-unit residential real estate under construction and this figure is expected to grow further.

There is also an increase in the construction of similar projects in other resorts across the country, for example, on the Baltic coast or at mountain and spa resorts in the North Caucasus, the Altai Mountains and the Urals, among others.

EXPO 2027 boosts Serbian non-residential construction

Written by Dejan Krajinović, Beobuild Core d.o.o., EECFA Serbia

Overall construction output in Serbia is expected to decline this year, primarily due to the slowdown in civil engineering as several major road and railway projects were completed last year. By contrast, non-residential construction has entered a new growth cycle driven by investments connected to the hosting of EXPO 2027 in Belgrade. The event will be held in a purpose-built exhibition complex in the outskirts of the city, covering around 80 hectares. Alongside the construction of this complex, numerous public and private investments are indirectly tied to the event, including new hotels, accommodation, leisure, and commercial projects, as well as the reconstruction of museums, cultural heritage sites, and public spaces.

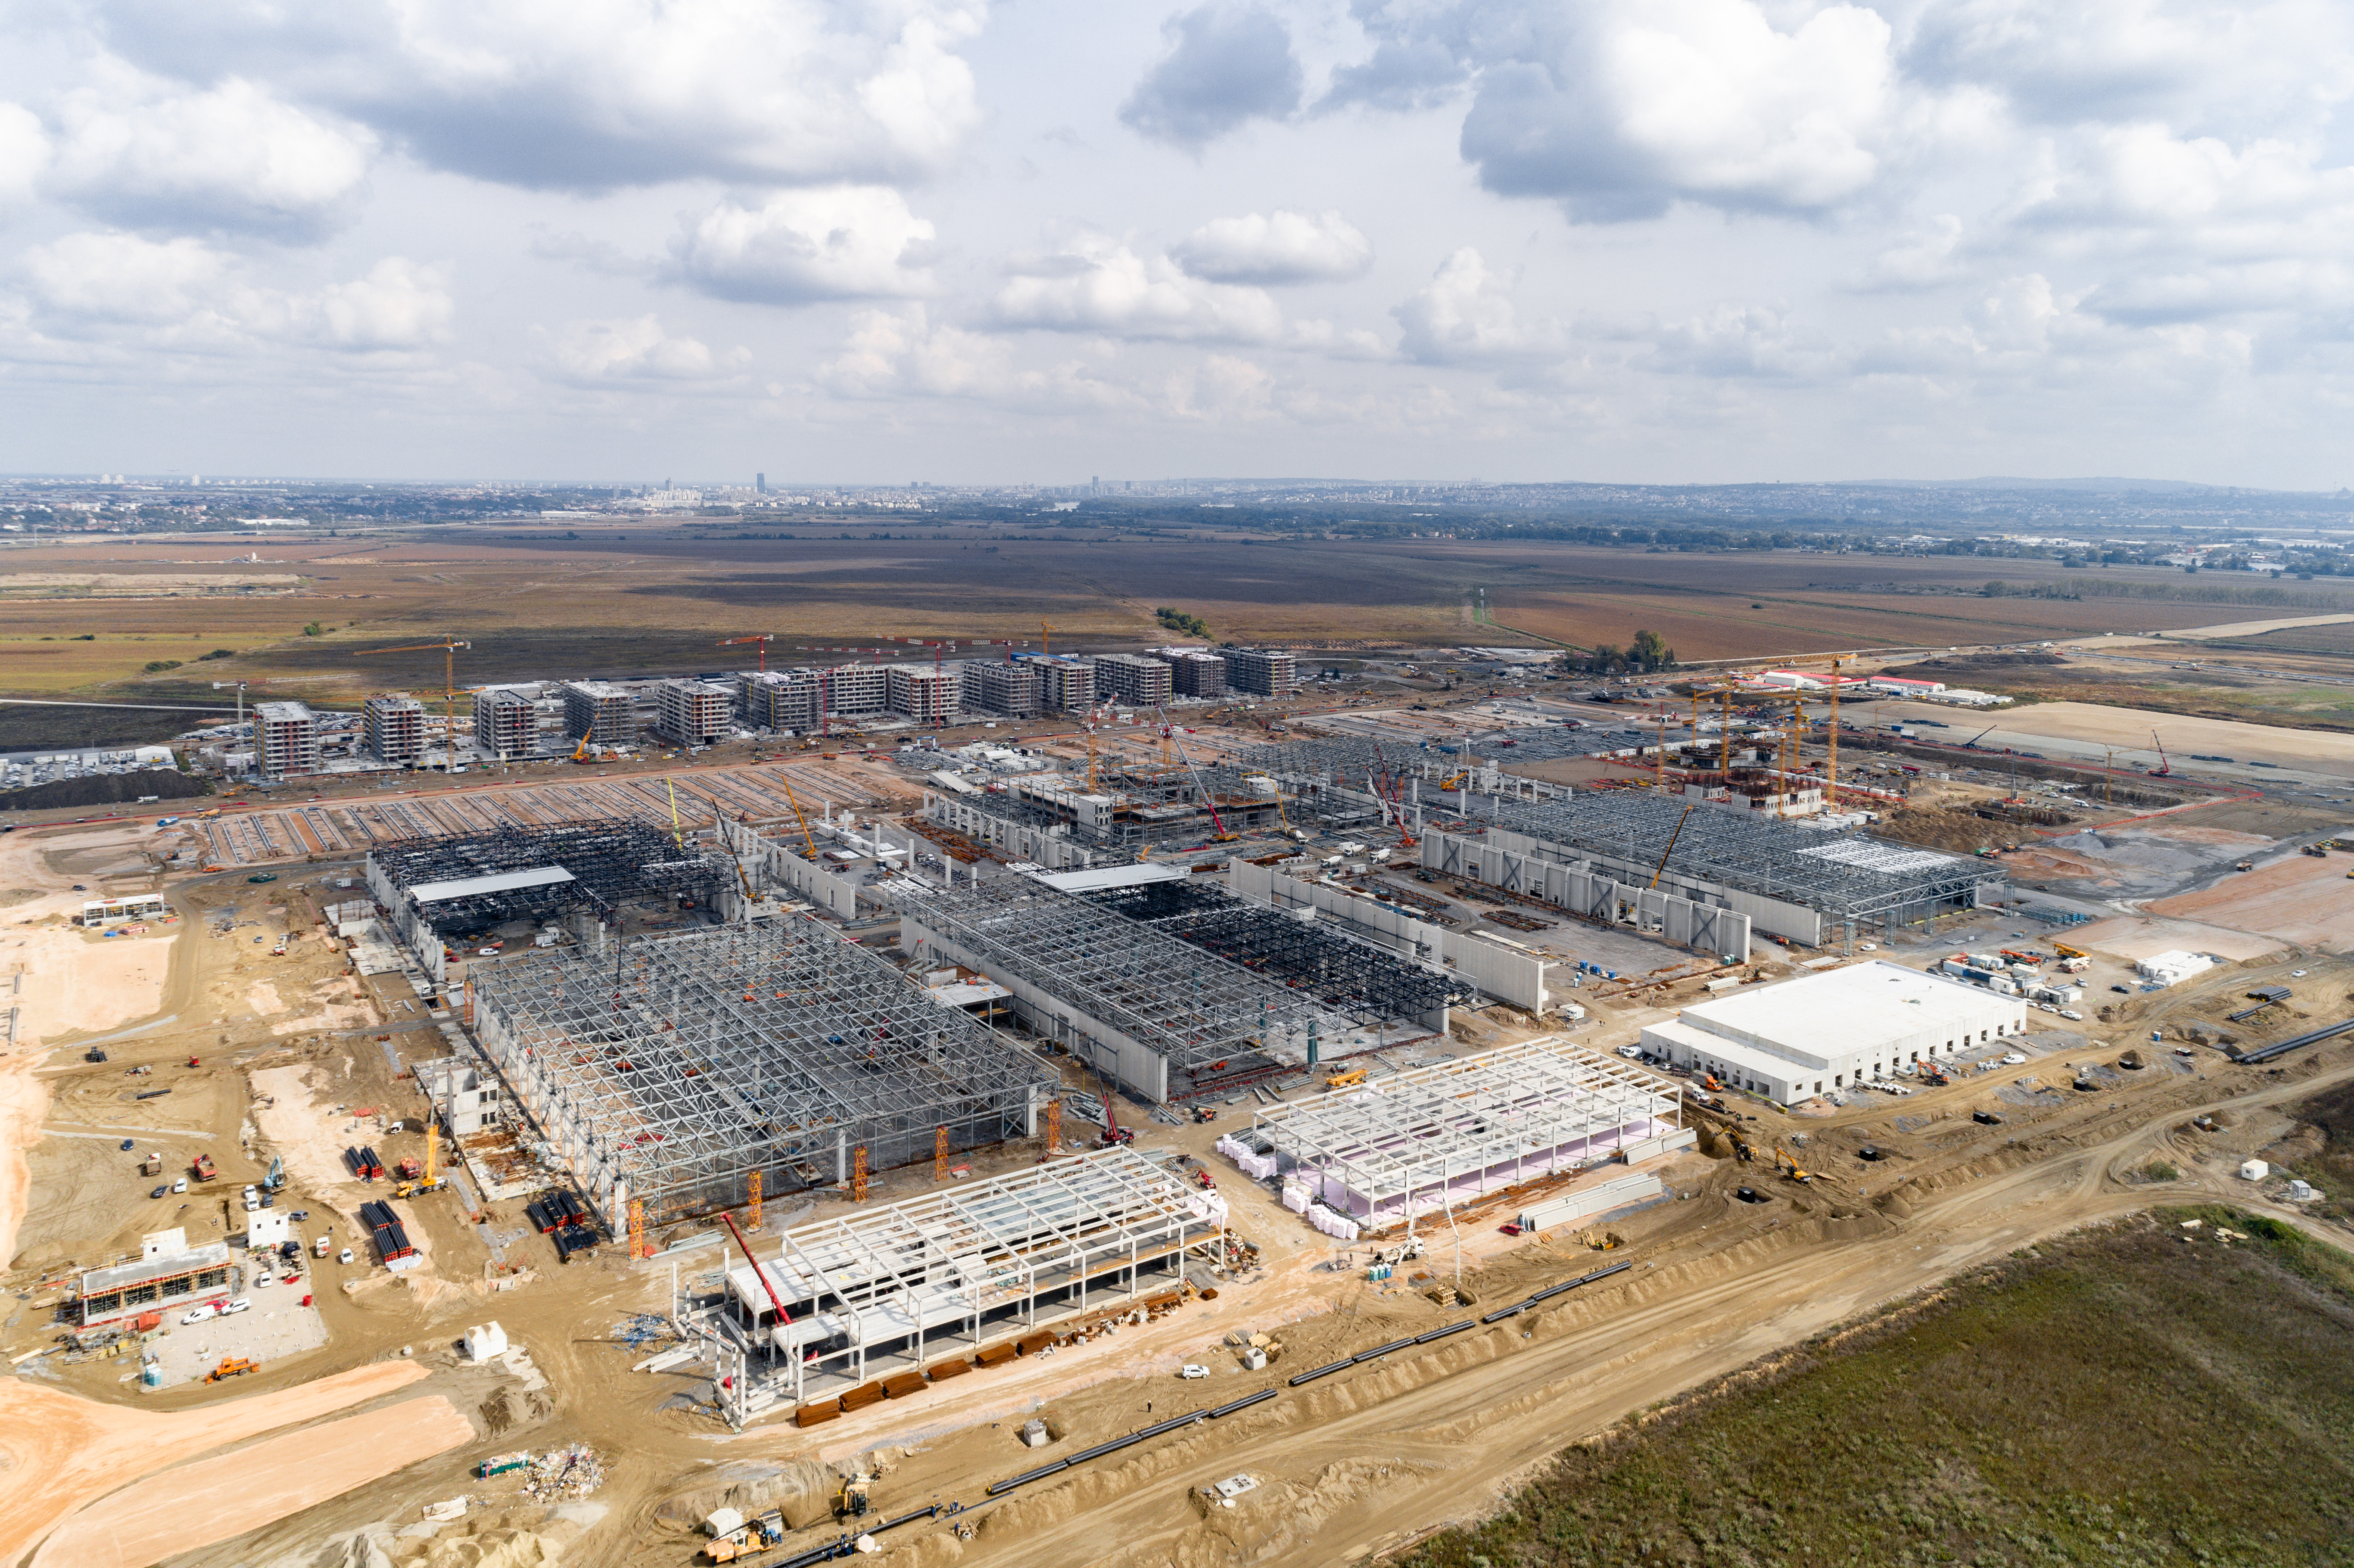
Aerial photo of the construction site of the EXPO 2027 complex – Photo: beobuild.rs

The EXPO 2027 complex itself is a vast construction site, comprising approximately 230,000 sqm of exhibition pavilions, multifunctional venues, congress and conference halls, as well as office and retail space. In addition, a residential complex with around 1,500 units is being built to house participating delegations. The exhibition will run for 93 days, from 15 May to 15 August 2027, featuring around 130 countries and hundreds of events spanning sports, science, culture, and innovation. Total investment could exceed EUR 2.5 billion, with EUR 1.5 billion allocated for the EXPO complex and a further EUR 1 billion for accompanying facilities and infrastructure. This project has been the key driver of growth in non-residential construction and is expected to sustain activity in the sector in the coming years.

The broader development zone around the EXPO 2027 complex extends far beyond the exhibition center itself. While the core site covers 80 hectares, total development area exceeds 200 hectares. It will include the new National Stadium complex, a center for aquatic sports, a theme park, recreation facilities, and hotels. The National Stadium alone is a EUR 600 million project, designed with 52,000 permanent seats and the capacity to expand by an additional 8,000. Construction began in early 2024 and, despite delays, it is expected to be completed in time for 2027. Other sporting and leisure facilities are also planned for delivery ahead of the event, though it remains uncertain whether all projects will meet the deadline.

Several other public and private developments across Belgrade are linked to the exhibition, including the reconstruction and expansion of museum facilities: a new Natural History Museum building, the relocation of the Nikola Tesla Museum, the renovation of the Aeronautical Museum, and the modernization of the City of Belgrade Museum, among others. The private sector is likewise preparing for the anticipated rise in visitors, with investments in accommodation accelerating. Notable projects under construction include new hotels under the Intercontinental and Ritz-Carlton brands, alongside numerous smaller ventures.

However, the high level of spending on the EXPO 2027 has placed considerable strain on the state budget. To maintain fiscal deficits at around 3% of GDP, funds have been reallocated from other public projects. This has been most evident in infrastructure development and civil engineering, where shifting priorities have led to significant delays on major planned projects. As a result, civil engineering output is contracting faster than expected in 2025, with negative implications for growth in 2026 as well. On the other hand, long-term economic benefits of hosting EXPO 2027 remain uncertain.

After the event concludes, the EXPO 2027 complex will be repurposed as the new Belgrade Fair Complex. The current fairgrounds in central Belgrade, built in the 1950s, are planned for redevelopment once operations move to the new site. This ensures that the EXPO facilities will continue to be used in the years ahead, supporting the economic rationale for the project. Moreover, new transport infrastructure, including a railway link to the city center, river dock facilities, and expanded commercial developments, should further enhance the attractiveness of the location for private investment.

Good news from Türkiye: permit data for rebuilt earthquake-damaged housing included in statistics

Written by Prof. Ali Türel, EECFA Türkiye

Rebuilding permits, previously excluded from TurkStat’s statistics, were published on 22 August this year. The addition of statistics on rebuilding damaged housing in earthquake-hit regions raised building permits and completions in Q2 2025.

Video by TOKI (Housing Development Administration): Construction projects implemented by TOKI in the earthquake zone in Türkiye.

This May and June saw high construction production in Türkiye

The Calendar Adjusted Index of Construction Production increased by a respective 20,4% and 24,9% in May 2025 and June 2025 compared to the same months of 2024, after declining in the previous three months. Building construction went up by slightly higher rates, 23,5% and 16,9%, while civil engineering grew less, by 9,9% and 16,7% in May and June 2025.

Construction also had high shares in the Turkish GDP. The Seasonal and Calendar-Adjusted Gross Domestic Product in the chain-linked volume index for construction in Q1 2025 expanded by 7.4% annually, while the national average GDP growth was 2,7%. The rise in construction within GDP began after the destructive earthquakes in February 2023. The rebuilding of approximately 870,000 independent units, including 650,000 dwelling units and infrastructure, started in the following months, and the growth rate of construction in GDP increased to 7,2% in 2023 and 9,3% in 2024.

In Q2 2025 we may expect a higher growth rate for construction than in the previous quarter since the completion of 250 thousand dwelling units has been reported until June 2025. Also, a total of 453 thousand urban and rural housing and workplaces will be handed over to legal beneficiaries by the end of 2025 (Source: Anatolian News Agency).

However, building start and completion statistics did not show the same trend in Q1 2025; the total floor area of construction and occupancy permits fell by 20% and 24,9%, respectively, compared to Q1 2024.

Rebuilding statistics in earthquake-hit regions added on 22 August 2025

Q2 2025 saw a sharp reversal of this trend with the addition of rebuilding statistics of damaged housing in earthquake-hit regions. We have been following the process of inclusion of the rebuilding statistics into TurkStat’s published statistics, and we are happy to see that it was published on 22 August 2025.

The delay of including rebuilding statistics can be linked to the effects of law 7471 which aims to speed up rebuilding damaged structures in earthquake-hit regions. The responsibility of the Ministry of Environment, Urbanization, and Climate Change in rebuilding damaged housing caused by natural disasters is further supported by this law. The Housing Development Administration (known as TOKI in Turkish), affiliated with that Ministry, handles the implementation and financing of rebuilding projects. The Ministry’s local branches have been issuing construction and occupancy permits in earthquake-affected regions as outlined in the same law. TurkStat collects and publishes building permit statistics issued by municipalities and transmitted online to them. Since the local branches of the Ministry were not part of this network, rebuilding permits were not included in TurkStat’s previously published statistics. The table is based on the revised statistics and there may still be further revisions in future publications if there is missing data in current rebuilding statistics.

Building permit
floor area,mln m2
Building permit
annual change,%
Occupancy permit
floor area,mln m2
Occupancy permit
annual change,%
2023197,5616,7118,80-15,6
2024180,27-8,7138,2116,4
Q1 202535,24-20,031, 25-24,9
Q2 202554,3661,827,2030,2
Rebuilding permits in earthquake-hit regions. TurkStat has revised the data by including permits of all authorized administrations to issue building certificates.

Less building construction activity without rebuilding works can be related to the high-interest rate policy to curb inflation, currently at a 43% level. Both producers and credit users have problems in production and purchasing produced goods without relying on bank credits. Lowering inflation and interest rates would lead to the stimulation of building construction.     

EECFA countries in the European Commission’s 2025 Macro Forecast

Written by Dóra Barát – ELTINGA, EECFA Research

This summer ELTINGA at EECFA Research has again looked at how the European Commission sees the EECFA countries. Here is what has changed in the prospects between Autumn 2024 and Spring 2025.

Compared to Autumn 2024, economic outlook has deteriorated in all countries covered, although the projected growth remains positive across the board. The most significant downward revisions have occurred in Romania, Bulgaria, and Hungary, while countries like Croatia, Slovenia, and Russia have seen more moderate adjustments. Growth expectations for both the EU and the Euro Area have also slightly declined, mirroring the broader cooling of optimism across the region.

Average GDP growth in 2025-2026 is projected to be positive in all examined countries, though to differing degrees. Serbia is expected to record the highest expansion at 3.5%, followed by Türkiye (3.15%) and Croatia (3.05%), while Russia (1.45%) is forecast to have the slowest growth in the region. Growth in Euroconstruct member Hungary is projected at 1.65%, falling between the regional average and the broader EU outlook. The remaining EECFA countries (Romania, Bulgaria, and Slovenia) are expected to grow between 1.8% and 2.2%. Despite downward revisions, all countries in the region are forecast to outperform the averages of the EU (1.3%) and the Euro Area (1.15%), continuing the trend of a stronger growth in Eastern and Southeast Europe.

The projected growth rate of gross fixed capital formation (GFCF) for 2025-2026 has weakened in nearly all countries since the Autumn 2024 forecast. Romania has witnessed a major downward revision with the expected growth dropping by just over 4 percentage points, while Hungary has also registered a significant cut of around 2.4 percentage points. Türkiye, Slovenia, and Bulgaria have experienced more moderate declines. In Croatia, the outlook remained unchanged at 3.75%, and Russia was the only country with a slight upward revision. Despite the general slowdown, Serbia is projected to post the strongest GFCF growth at 6.7%, followed by Croatia (3.75%) and Romania (2.95%), while most other countries are set to grow between 1.25% and 2.75%. The EU (1.95%) and Euro Area (1.75%) are to remain at the lower end of the spectrum.

Expectations for the growth rate of gross fixed capital formation into construction have also been revised downward in all countries where data is available. Romania has seen the steepest decline with its projected growth falling from 8.45% to 3.9%, though it still holds the highest rate among the observed countries. Hungary and Slovenia have experienced similar reductions, both dropping by more than 2.5 percentage points. Smaller adjustments have been recorded in Bulgaria and Croatia where the outlook for GFCF into construction growth remains relatively strong at 2.85% and 3.8%, respectively. In the broader European context, the EU and the Euro Area are projected to see only a respective modest growth of 1.9% and 1.6%, slightly below most national forecasts in the region.

The Commission’s view on construction investment is somewhat different from ours. Partly it is because we examine the sector from the bottom. For each segment we come up with an individual story and this is how the total construction market is formed. Our latest forecast is in the 2025 Summer EECFA Construction Forecast Reports. Sample report and order

We, in EECFA, are also less optimistic about the near future than half a year ago. The direction of the revision is mostly downward. In cases of Bulgaria, Croatia and Hungary we project moderate growth which is pretty close to the Commission’s expectations. In four countries, however, we do not think average real growth until 2026 could be positive.

EECFA 2025 Summer Construction Forecast

EECFA released its 2025 Summer construction forecast on 23 June. See a sample report and place your order on eecfa.com. To get discounts, you may contact us.

Southeast European construction markets up to 2027

According to Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian research institute, total construction output in Bulgaria is anticipated to grow by 3% on average for 2025-2027 with a stronger growth in the middle of the period when the absorption of operational programmes and the implementation of the Recovery and Resilience Plan are to gain momentum. According to the sectoral breakdown, residential construction is expected to be the subsector with the weakest performance, while non-residential construction and particularly civil engineering are predicted to see stronger growth figures. Against this backdrop, the country’s economy is set to register a slower-than-expected growth in 2025 and 2026. In parallel, it is awaited to benefit from the effects from the full Schengen area membership effective from the beginning of 2025 and from the euro adoption expected on 1 January 2026.

Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s Croatian members think that Croatia’s construction as a whole continues vibrant due to the combination of continuing transitioning-economy catch-up growth and large inflows of EU money. Both are beginning to diminish, however, and that will affect all construction segments, some more strongly and more quickly than others. In building construction several sectors have seen the end or are close to seeing the end of catch-up growth. Others, particularly those that benefit most from EU finance, are still going strong. Civil engineering continues to profit greatly from EU funding, and because of the poor initial condition of Croatia’s infrastructure after independence, much catch-up construction remains to be done. Certain government policies will have a great influence on specific building and civil engineering sectors. Those policies include the housing policies embodied in Croatia’s new National Housing Policy Plan until 2030, the new tax on real estate and the country’s renewable energy permitting and electrical grid hook-up fee rules.

‘Romania’s macroeconomic outlook remains positive, but more reserved as the political instability and fiscal uncertainty have done little to improve growth opportunities’ – says Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild. At the same time, he adds, the country has the largest government deficit in the EU, which will dampen public investment capabilities. All these will make it harder to finance public works and could negatively impact civil engineering. This is doubly worrying as this subsector countered the decline in other construction segments in 2024, and thus the outlook for total construction remains negative in 2025 and 2026 in real terms. Not all is gloom and doom, however. As inflation and interest rates come down, and employment indicators remain strong, private consumption could boost demand for residential and non-residential construction.

‘In 2025 Serbia’s construction is making new gains in building construction, while civil engineering has entered a period of consolidation after the strong expansion during 2023 and 2024′ – believes Dejan Krajinović, EECFA’s Serbian researcher at Beobuild. Building construction is supported by both public and private investments, boosted by the hosting of the EXPO 2027 in Belgrade. Non-residential construction is the main beneficiary of this event, particularly commercial, office and hotel segments, while residential construction is also keeping historically high volumes. Some delays are seen in civil engineering, but the overall performance is still strong with a long list of planned projects in all major subsegments. Domestic demand is still relatively strong, but economic growth and the level of investments are being muffled this year by uncertainties in the global markets, particularly the weak EU economy, international trade issues and the ongoing wars in Ukraine and the Middle East.

‘Total construction output in Slovenia is expected to decrease from the historic high of EUR 5,5 billion reached in 2023. In both 2024 and 2025, it could contract but remain above EUR 5 billion annually’ – as per the opinion of Dr. Aleš Pustovrh at Bogatin, EECFA’s Slovenian member institute. He predicts the sector to return to growth in 2026 and 2027, mostly on the back of a healthy growth in residential construction buoyed by decreasing mortgage rates. On the other hand, civil engineering is prognosticated to shrink significantly in 2024 and 2025 due to some large projects nearing completion, like the new railroad connecting Port Koper. Both non-residential and civil engineering depend to a large degree on public financing that was widely available in the post-Covid period but will become much less available in 2025-2027. Especially if the overall economic activity continues to slow down. This deceleration and more foreign labourers have also caused lower construction cost growth, but other challenges persist such as the additional bureaucratic burdens (changed permitting process, increase in tax, ongoing discussion on changes to short-term rental legislation, among others) and many external risks in the global economic and political environment. 

Eastern European construction markets up to 2027

‘In the forecast horizon, the construction sector of Russia will be under pressure from a range of macroeconomic factors, the main one being the high key rate, which will negatively affect the pace and volume of construction projects’ – according to Andrey Vakulenko at MACON, EECFA’s Russian research institute. The tight monetary policy and the reduced availability of mortgages will likely slow down housing construction, on the one hand. On the other, the high cost of project financing, the general cooling of the economy as well as reduced consumption and business activity will likely shrink the volume of investment in non-residential construction. However, these trends can partly be offset by high volumes of government financing of priority infrastructure and energy projects, which can support civil engineering and ensure near-zero growth in total construction market in 2025-2027.

Prof. Ali Türel, EECFA’s Turkish researcher says that Türkiye has been trying to control high inflation by raising the base rate and managing exchange rate increases through market instruments by the Central Bank and maintaining wage growth at zero or negative rates. This created financing difficulties for industries and businesses, reduced demand for basic consumer goods, and led to affordability problems for mortgage credits. Big declines in building starts and completions in Q1 2025 may also be related to these measures. Yet, the Central Bank’s inflation target for 2025 remains high at 24%. Positive real changes in housing prices relative to building construction costs encourage house building, while their negative real change compared to inflation may be the leading factor in the increase of home sales through equity financing when mortgage credits are not affordable for most households. Rebuilding the quake-damaged 870 thousand units requires about EUR 100 billion and these expenditures have been the primary factor of the large national deficits in recent years.

‘This year, in spite of the continuing war and the economic instability in the country, Ukraine’s construction industry shows signs of recovery and growth on the back of successful programs financing both the construction of new facilities and the reconstruction and restoration of infrastructure in eastern and southern regions’ – according to Prof. Sergii Zapototskyi at Uvecon, EECFA Ukraine. The World Bank estimates that reconstruction would require USD 486 billion. On the negative side for the sector are bureaucratic barriers in the urban planning legislation, shortage of workers caused by mobilization, shortage and high cost of building materials, and logistical difficulties. On the positive side for the sector is demand for housing and the need to restore damaged infrastructure. The near-term future of the industry depends on the level of security, the effectiveness of restoration programs and the volume of international investments.

Bulgaria’s Resilience and Recovery Plan – Save it or Lose it  

Written by Yasen Georgiev (EPI, EECFA Bulgaria)

Less than 25% of the funding for its Resilience and Recovery Plan has landed in Bulgaria so far. Last month, the new Bulgarian government, which took office this January, submitted a request to revise its Plan. Will all milestones and targets be achieved and will the country get all payments by the deadline of August 2026?

No reforms, no money

Do you remember the Resilience and Recovery Facility (RRF) the European Commission came up with to assist member states after the pandemic? Unlike traditional EU funds, this instrument in the form of national Resilience and Recovery Plans (RRPs) is meant to provide grants in exchange for specific reforms, making it a performance-based tool going hand in hand with time-bound milestones and targets (i.e. reforms). The completion of the latter is strictly tied to the disbursement of funds for public investments which literally means “no reforms, no money”.

For various reasons, in many EU member countries the implementation of the RRF is not going according to initial plans, and governments are currently submitting requests for revisions. They are to be reviewed and eventually approved by the European Commission. This is the case also with Bulgaria and its RRP that is financed with EUR 5.69bln in grants. As of mid-May 2025, though, the country has received less than 25% of the overall amount in the form of a first installment totaling EUR 1.36bln.

What is now at stake is the remaining EUR 4.32bln

The question is when this sum will be disbursed and whether the disbursement will be in full. The overall completion rate of the milestones and targets Bulgaria committed to in its RRP is at 38%, which stands for 122 finished reforms out of 321 in total.

To make things worse, the respective regulation at EU level says that all milestones and targets are to be achieved by 31 August 2026, and any payment under the RRF is be executed by 31 December 2026.

The new government is trying to speed up implementation and get full access to eligible funding

To address the accumulated delays (resulting also from a series of seven parliamentary elections in three years) and several underperforming parliaments that failed to adopt the respective legislative reforms, in April 2025 the new government submitted a request to the Commission to revise its RRP.

Bulgaria proposes to remove or modify several measures across the plan while cancelling or downsizing projects currently delayed. Since some of the proposed modifications concern outstanding issues under the second payment request, along with the modification request, Bulgaria also withdrew the payment request, with a view to resubmit it following the approval of the amended plan.

The biggest construction-related projects that are to drop out of the new RRP include a programme for the construction and reconstruction of water supply and sewerage systems (EUR 152mln), a project for heat and electricity co-generation from geothermal sources (EUR 123mln) and a pilot project for green hydrogen (EUR 33mln).

Other investments to see reduced funds are the construction of industrial parks and youth centres with an overall cut of EUR 15mln. While funding for all of these projects is to be potentially channeled from other EU programmes, there are projects that will receive more from the RRP than initially foreseen like the construction of the third metro line in Sofia with EUR 33mln in additional funding.

If proposed reforms and modified projects are approved in Brussels, the government expects to get the second and third RRF payment in the course of the year, while all remaining installments are to be disbursed by the deadline in 2026.

Needless to say, this seems like a very ambitious plan given the insufficient performance of the RRP in Bulgaria so far. This could also be seen in the official position of the government – the country may receive all payments by the deadline of August 2026 but will not have time to make all investments. This would mean that the projects underway at that time are either going to be downsized or put on hold until money from other sources is secured.

Segment-level construction forecast on Bulgaria can be found in the EECFA Construction Forecast Report. The new forecast will be out on 23 June. Orders and sample report: eecfa.com

BCG tanulmány: 2035-re megnő a kereslet az energiahatékony építőanyagokra

A Boston Consulting Group (BCG) idén februárban publikált egy tanulmányt a tavaly felülvizsgált EU-s EPBD irányelv apropójából, amelyben az energiahatékony anyagok és technológiák iránti jövőbeli keresletet modellezte. A tanulmány szerzői: Johannes Blauhuth, Lorenzo Fantini, Martin Feth, Jannik Leiendecker, és Alberto Pizcueta. Kőrösi Péter (ELTINGA) összefoglalója.

Klímasemleges új épületek az EU-ban 2030-tól

A klímavédelem célkeresztjébe került a legnagyobb energiafogyasztó Európában: az építőipar.  Európa szén-dioxid-kibocsátásának több mint egyharmadáért az épületek felelősek, ami összefügg azzal, hogy energiahatékonyságuk átlagosan igen alacsony. Emiatt az épületállomány dekarbonizációja középtávú uniós irány – már rövid távon is érzékelhető célkitűzésekkel.

Az Európai Unió célja a fosszilis tüzelőanyagok fokozatos kivezetése és a megújuló energiaforrások elterjedésének felgyorsítása, ezért tavaly májusban felülvizsgálták az épületek energiahatékonyságáról szóló irányelvet (Energy Performance of Buildings Directive – EPBD). Az új irányelv előírja, hogy a 2030-as évek elejére az épületállomány legrosszabbul teljesítő elemeit fel kell újítani, 2035-re pedig a lakóépületek energiafogyasztását 20–22%-kal kell csökkenteni. Továbbá 2028-tól minden új középületnek, 2030-tól pedig minden egyes új épületnek zéró kibocsátásúnak kell lennie.

A tagállamoknak 2026 májusáig kell átültetniük az irányelvet a nemzeti jogrendbe.

A BCG előrejelzése az energiahatékony építési technikák és anyagok iránti keresletre

Az új irányelv várhatóan már a következő negyedévekben hatással lesz az európai építőipar működésére. Bár a nemzeti szabályozás kidolgozása némi időt vehet igénybe, az első lépések már befolyásolhatják a befektetői döntéseket és a közbeszerzési szabályokat, különösen a középületek és az energetikai felújítások esetében.

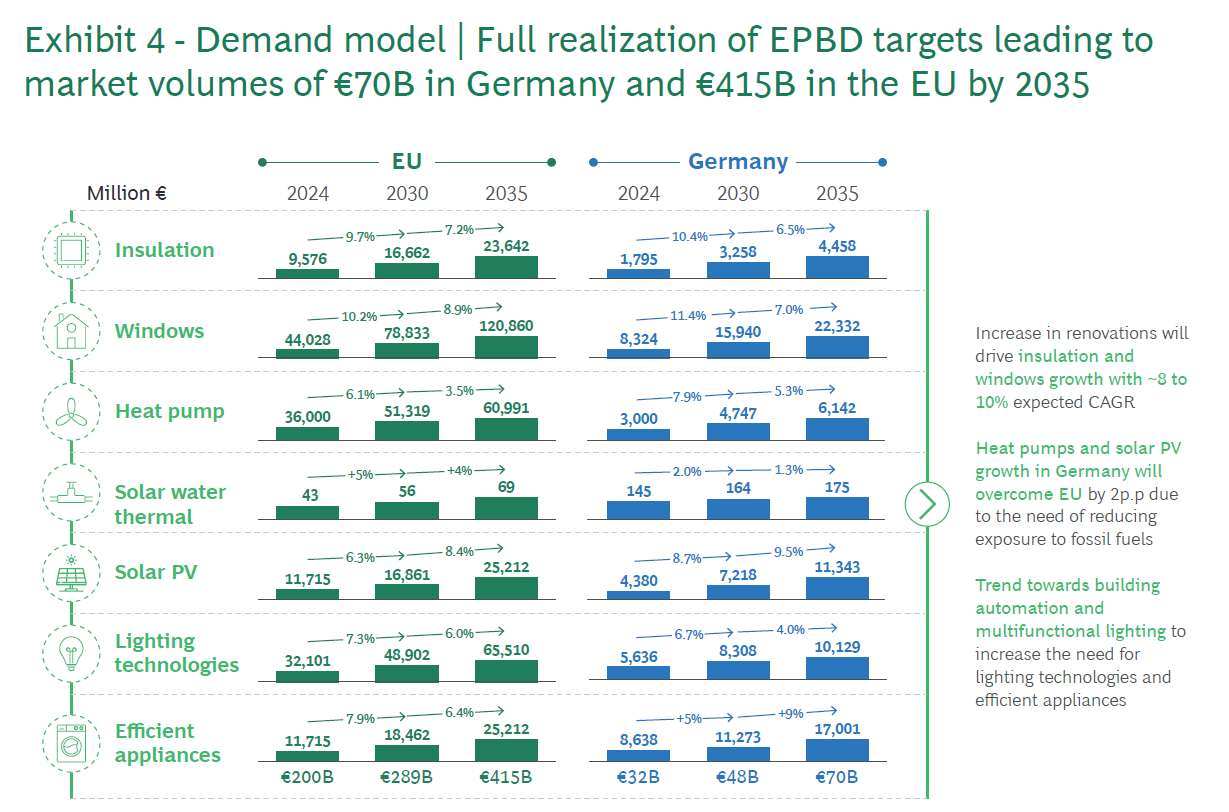
Ha az EU-s célok teljes mértékben teljesülnek, jelentős felújítási hullámra számíthatunk és a zöld építkezés is fellendülhet. A BCG előrejelzése szerint a modern szigetelőanyagok és a nagy hatékonyságú ablakok iránti kereslet évi körülbelül 10%-kal, míg a hőszivattyúk és napelemek iránti kereslet évi 6-8%-kal bővülhet.

A lenti ábra a keresletet modellezi az EPBD-célok teljes megvalósulása esetén, mely 2035-re 70 milliárd eurós piaci volument jelent Németországban és 415 milliárd eurós piaci volument az EU-ban.

Az EPBD célkitűzéseihez időben alkalmazkodó vállalatok előnyre tehetnek szert versenytársaikkal szemben az egyre szigorúbb energiaszabványok és a fenntartható építési trendek környezetében.

Forrás: Boston Consulting Group (BCG), White paper: The building sector and EPBD – Demand impications for energy-efficient materials and technologies, February 2025 by Johannes Blauhuth, Lorenzo Fantini, Martin Feth, Jannik Leiendecker, and Alberto Pizcueta.

Összefoglaló: Kőrösi Péter (ELTINGA)