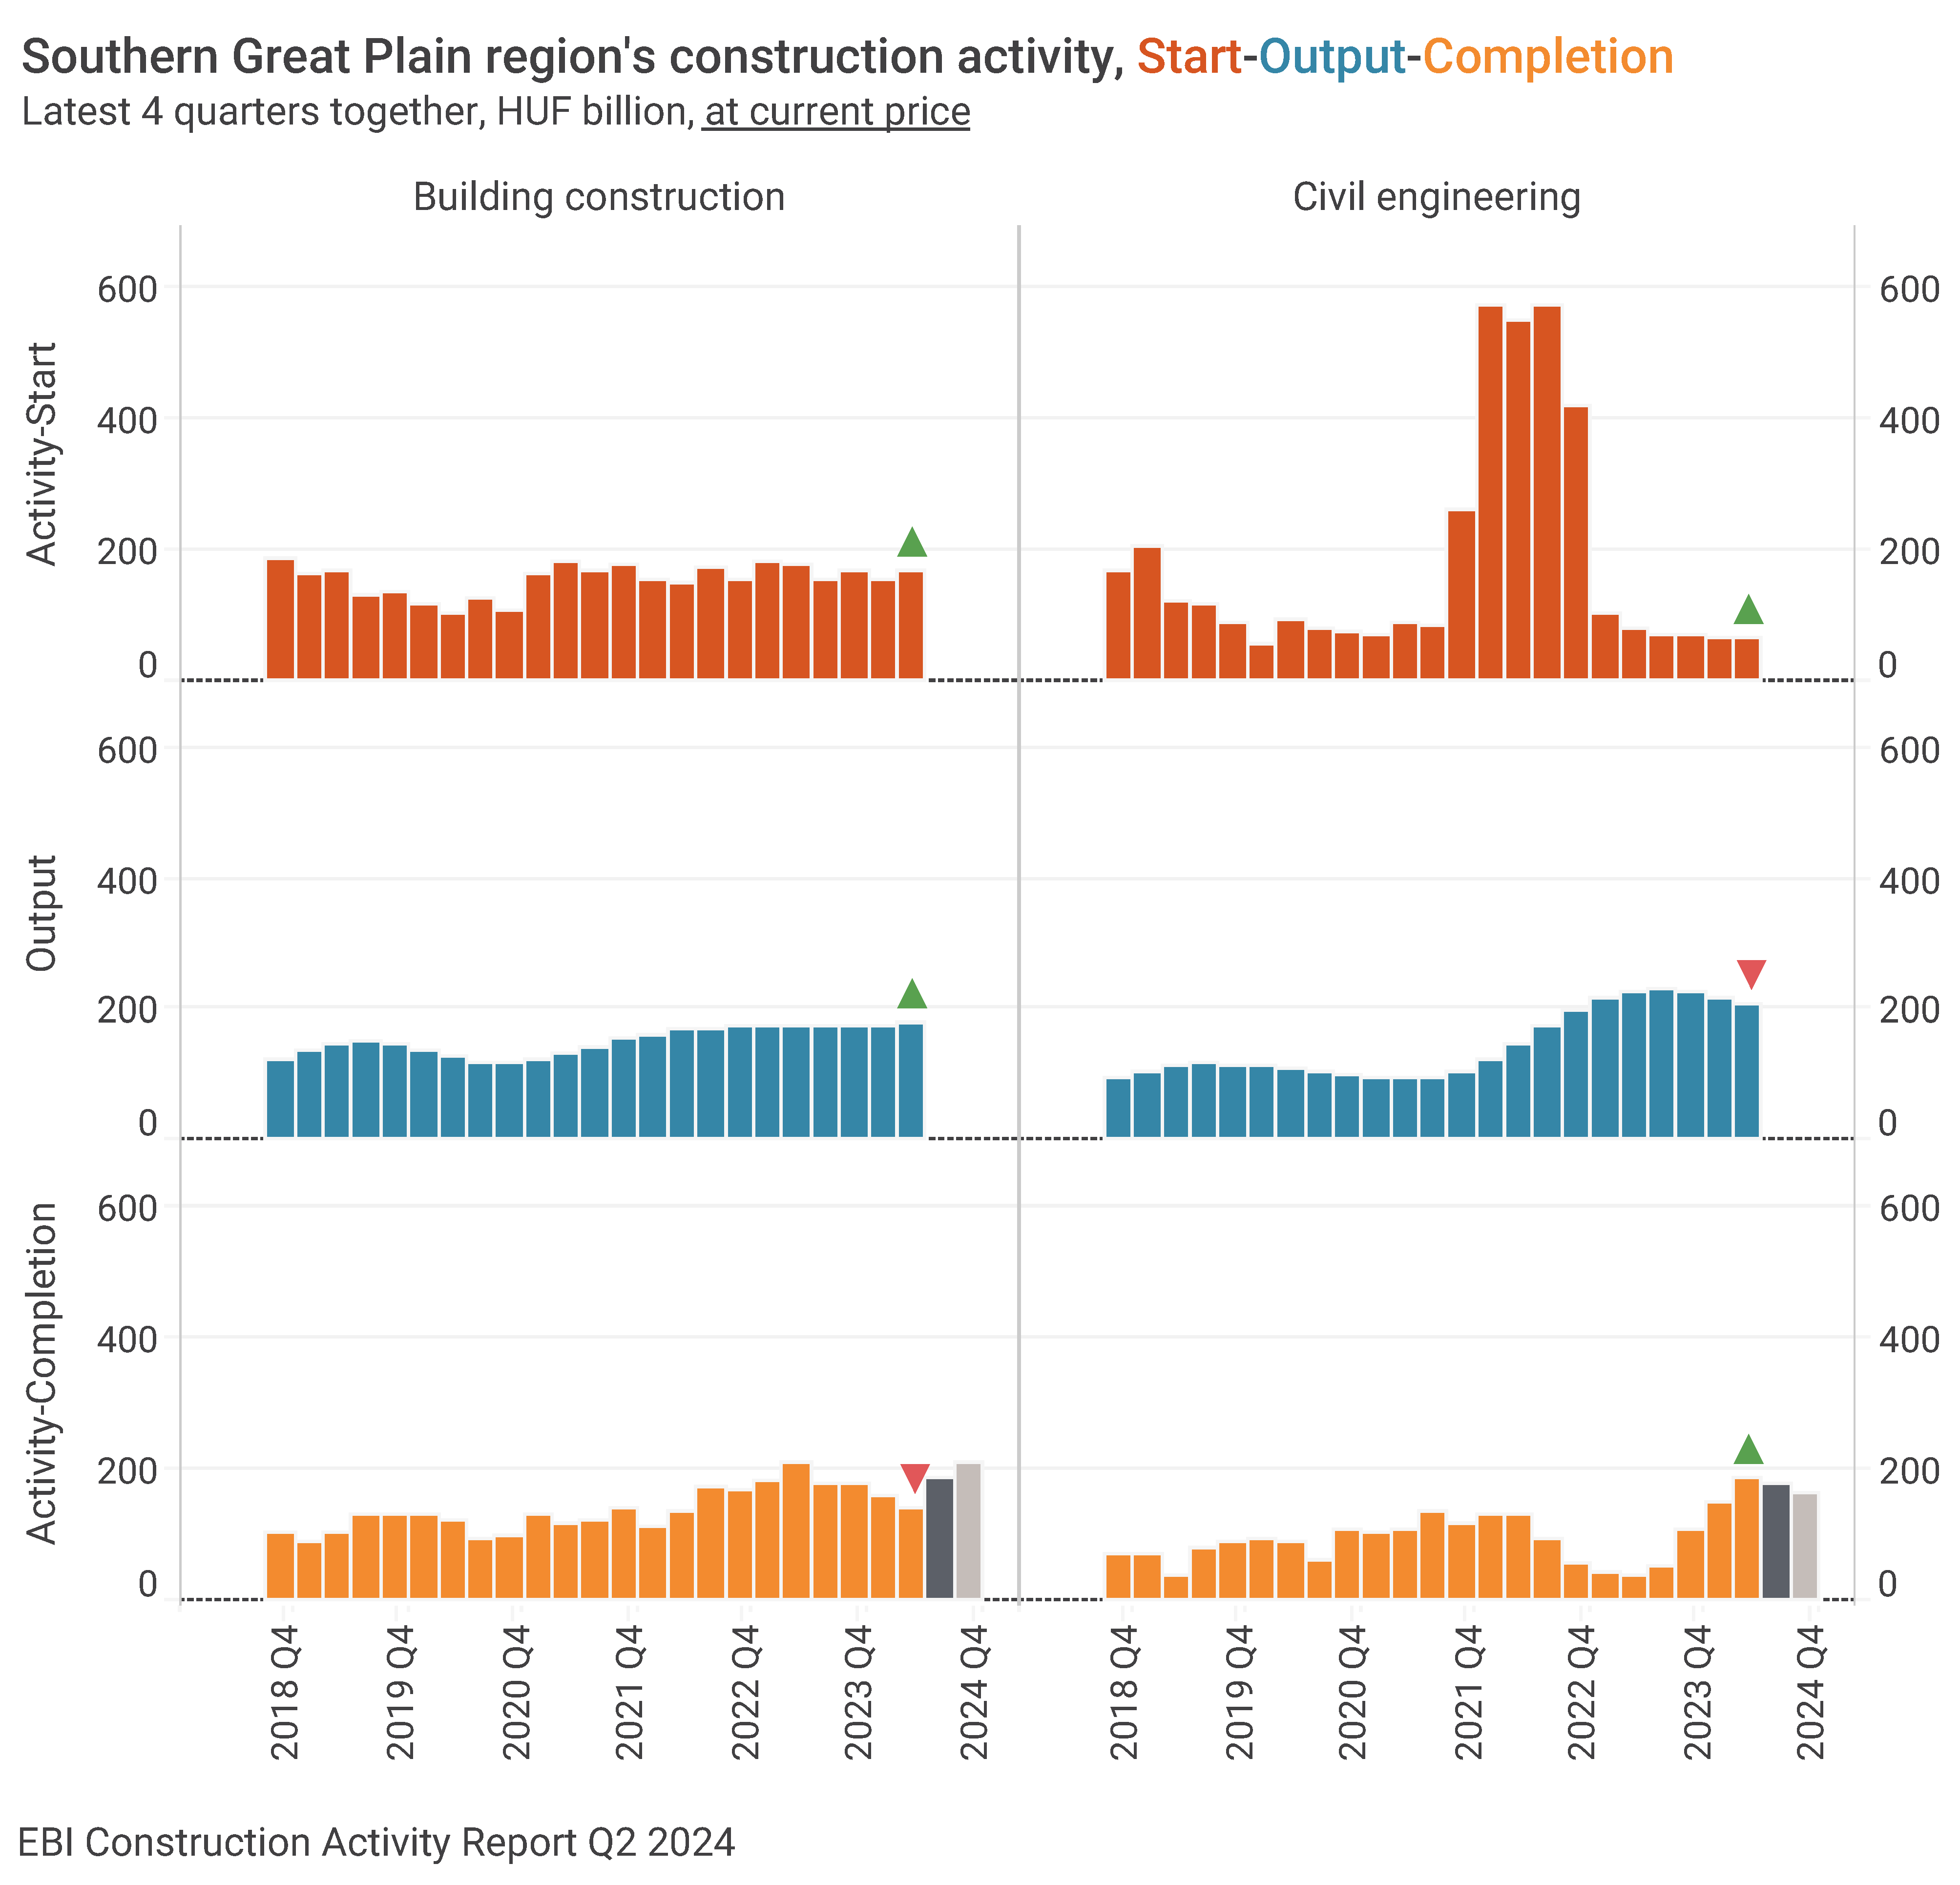
M1 motorway boosting Activity-Start in Hungarian construction

The latest EBI Construction Activity Report Hungary has found that it was mainly due to the ongoing M1 motorway expansion that the value of started construction projects rose significantly in the third quarter of this year. The value of projects entering construction in July-September 2025 exceeded HUF 1,000 billion at current price – the second highest level in the past ten years. Without this motorway expansion, accounting for around 60% of Activity-Start, the figures would have been much more modest, though.

Building Construction Activity-Start

In Q3 2025 the value of started building construction projects was HUF 400 billion, around the same value as between April and June. Thanks to the outstanding figures between January and March, the value of building construction projects entering construction phase exceeded HUF 1,500 billion, only 4 points short of the same period in 2023 and 2024. At constant price, Activity-Start between January and September of this year was the lowest in the past 9 years.

Activity-Start of EBI Construction Activity Report in multi-unit housing construction, although greatly sank, stayed at a high level, with the total value of projects started in Q3 2025 exceeding HUF 170 billion. The situation was the opposite in non-residential construction. The segment recovered somewhat between July and September from the previous quarter’s low point, but projects still entered construction at a low value: Activity-Start was around HUF 230 billion. Since 2017 non-residential construction projects haven’t started at a lower value than in the first 9 months of this year.

The largest non-residential projects entering construction in Q3 2025 included MCC’s talent centre in Miskolc, BYD’s electric bus assembly plant in Komárom, Panattoni Logistics Park Building A in Mosonmagyaróvár, IGPark automotive parts manufacturing hall in Nyíregyháza, Phase 2 of Weerts Ebes logistics centre, and MVM Neuron headquarters office building in the 3rd district of Budapest.

Civil engineering Activity-Start

Civil Engineering Activity-Start of EBI Construction Activity Report registered a surge in Q3 2025 due to M1 motorway expansion (M0-Concó rest area). Outside road construction, the value of construction projects started in other civil engineering segments was moderate. While total Civil Engineering Activity-Start exceeded HUF 760 billion, the value of non-road and railway projects started was only around HUF 50 billion in Q3. In addition to the two phases of M1 motorway expansion, only Phase 7 of the closure of the Gyöngyösoroszi ore mine could make it to the list of the biggest started civil engineering projects.

Budapest on top among regions

In the past four quarters, the highest value of construction projects in Hungary started in Budapest and its share in total Activity-Start was 28%. Central Transdanubia also had a large share of 23%. 39% of projects started in Western Hungary, 38% in Central Hungary, while Eastern Hungary’s share was 23%.

Still high multi-unit housing Activity-Start

Although Q3 2025 was the second consecutive year to see a significant drop in the value of started multi-unit housing construction works, Activity-Start stayed high, far exceeding the average of recent years. At current price, multi-unit housing construction works started at an over HUF 170 billion, the fourth highest value after the first two quarters of 2025 and the last quarter of 2024. Overall, the successful first 9 months of this year brought a huge jump in multi-unit housing Activity-Start at current price, but it was also outstanding at constant price, only surpassed by the same period in 2017 in the last 10 years.

Multi-unit housing construction is likely to remain strong. There was a high number of building permits issued in the first three quarters of this year, meaning plenty of projects to get started. In Q3 2025 permitting was boosted by the preferential loan program dubbed Otthon Start available since September which could continue to have a positive impact on the number of homes under construction.

In Q3 this year, multi-unit homes worth around HUF 80 billion were completed at current price, while in the first 9 months, multi-unit housing Activity-Completion was well over HUF 200 billion, only slightly lower than in the same period in 2023-2024.

Looking at the past 4 quarters, Budapest continued to have a major share in multi-unit constructions entering construction (73%). Central Hungary had a 76%, while Western Hungary and Eastern Hungary had a share of 12% each.

Still weak Activity-Start in industrial buildings and warehouses

Industrial buildings and warehouses thrived between 2022 and 2024 when construction works worth between HUF 700 billion and 1,000 billion started annually. For example, construction started on several BMW plants around Debrecen, on Mercedes-Benz projects in Kecskemét, and on several battery factories. This year has seen a decline so far and the value of projects started during three months in Q2-Q3 2025 has been the lowest since 2021. Overall, in the first 9 months of 2025, Activity-Start in industrial buildings and warehouses was around HUF 400 billion, 37% lower than in the same period of 2024, and 29%-39% lower than the 2022-2023 values. Trends are similar at constant price: the period of 2021-2023 was exceptionally good for industrial buildings and warehouses, while there was a strong decline in 2025. In the last 10 years, Activity-Start at constant price in the first 9 months has not been so low as now.

The biggest projects started between January and September 2025 were CTP’s logistics halls in Biatorbágy and Vecsés, HelloParks’ logistics hall in Fót and BYD’s projects in Szeged and Komárom. Construction of Phase 1 of Halms automotive parts manufacturing plant in Miskolc and Panattoni Logistics Park Building A in Mosonmagyaróvár also started.

Activity-Completion was relatively high in all three quarters of 2025 as several projects that started in 2022-2024 reached completion. The value of projects completed since the beginning of 2025 neared HUF 700 billion. For example, this year saw the completion of CATL warehouse and metalworking plant in Debrecen and its surroundings, two BMW factories, and the hangar complex of the Helicopter Base in Szolnok. And Activity-Completion may also remain high in the last quarter of this year.

Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

Q2 2025: drop in construction start in Hungary

On a quarterly level, the value of started construction projects in the second quarter of this year has been the second lowest since 2020 and the Activity-Start of EBI Construction Activity Report Hungary at current price did not reach HUF 470 billion. In the first half of the year, projects entering construction phase were worth around HUF 1,200 billion, far below the previous years and close to H1 2020 when the pandemic hit.

Building construction performed poorly in Q2 2025

In Q2 2025 the value of building construction starts fell below HUF 400 billion, barely reaching half of the Activity-Start of Q1. After 2020 it was only in Q3 2024 when the value of construction starts was at a similarly low level. The decline in building construction was even more pronounced at constant price: Activity-Start of EBI Construction Activity Report at constant price was last lower in Q1 2015 than in Q2 this year.

Such a poor performance in building construction occurred despite the extremely successful quarter in multi-unit housing construction. The Activity-Start for non-residential construction fell to a critically low level not seen since Q1 2015, below HUF 120 billion. At constant price, the decline is even more drastic, the value in Q2 2025 was less than half of the previous negative record.

The largest building construction projects during Q2 2025 were mostly multi-unit housing ones. Only one non-residential project made it to the list of the biggest projects, Phase 1 of Halms automotive parts manufacturing plant in Miskolc.

Better Civil Engineering Activity-Start, but still at a low level

Q2 2025 saw an improvement over Q1 in Civil Engineering Activity-Start of EBI Construction Activity Report, but projects started only at a value of around HUF 100 billion. In the road and railway construction segment, there was an increase in Q2 2025 against Q1 with projects entering construction phase on HUF 50 billion, a level not considered high.

The biggest civil engineering projects launched in Q2 2025 include the railway infrastructure of the Ivancsa industrial-innovation development area, the XIV/A water shaft in Tatabánya, and the development of the drinking water networks in Ács, Bábolna and Koppánymonostor.

The capital city has the highest share in total Activity-Start

Looking at construction projects launched in the past four quarters, Budapest had the highest value with a share of 34% in total Activity-Start. It still exceeds the 20%-30% typical of the period between 2021 and 2023.

In the previously leading Northern Great Plain, 16% of projects started. The share of Southern Transdanubia was 15%, and that of the Southern Great Plain was 11%. The lowest values ​​were registered in Northern Hungary and Western Transdanubia during the period, with a share of 4% each. In Central Transdanubia and the Pest region, a respective 8% of projects were launched.

Favourable trend continuing in multi-unit housing construction

Q2 2025 far exceeded the average of recent years in terms of the value of construction starts: multi-unit housing constructions started at HUF 250 billion at current price. This is an absolute record, the second highest value after Q1 2025 registered since 2014. Activity-Start of EBI Construction Activity Report in the segment exceeded HUF 200 billion for the third consecutive quarter, way more than the previous highest HUF 144 billion until H1 2024. The expansion was also significant compared to previous years, even when calculated at constant price.

The momentum fuelled so far by maturing government bonds and interest payments may continue this autumn with the launch of the Home Start Program (providing first-time home buyers with a fixed-rate loan of up to HUF 50 million at a 3% interest rate). Also, this autumn, projects financed by the Housing Capital Program this year (a government initiative to help the supply side) may also appear among sold homes. As a result of these, a pick-up in both demand and supply is expected for the rest of the year. In Budapest, the projects of the Housing Capital Program may be the source of a further high level of Activity-Start. In the countryside, more multi-unit housing projects may start due to the livelier demand thanks to the launch of the Home Start Program. In the capital city, the number of available new homes is already at one of the highest levels in recent years because of the previous significant construction starts. This, in addition to the new supply, may make developers more cautious with project launches as the end of the year approaches.

The value of completed multi-unit homes in Q2 2025 was around HUF 90 billion, a slight increase compared to Q1. Overall, Activity-Completion of multi-unit housing constructions slightly dropped in the first half of the year compared to the previous year, remaining roughly at the 2023 level.

Looking at the past four quarters, Budapest has had a massive share in multi-unit housing constructions entering construction phase (75%), while none of the other regions reached 10%. In Central Hungary 77% of such projects started and in Western Hungary 14%, while only 9% of the Activity-Start was registered in Eastern Hungary.

Hotels in focus: the year started off sluggishly for projects, but growth is visible

Hotel construction works boomed in 2019-2020 most, but projects also commenced in 2021 and 2023 at relatively high values. 2024 saw a slight decline, and this year also started rather sluggishly. The second quarter brought some expansion, though; between April and June 2025, the total value of construction starts in the segment was over HUF 20 billion, a major improvement compared to the previous, very weak quarter, and roughly the same as the median for the period between 2023 and 2025. At constant price, we also see that Activity-Start of EBI Construction Activity Report in Q2 2025 does not differ much from previous quarters but is far behind the high values between the end of 2019 and the beginning of 2021. The largest started hotel projects in H1 2025 included Phase 1 of Staybridge Suites Hotel in Budapest and the MCC Talent Development Center project in Miskolc.

Several hotel projects that were launched in previous years have now reached completion. In Q2 2025, Activity-Completion in the segment set a record, approaching HUF 90 billion at current price and exceeding HUF 160 billion at constant price. For example, the 4-star hotel next to the Balaton Park Circuit racetrack and Le Primore Hotel in Hévíz have been completed.

Also, many hotel projects are currently underway which are due for delivery next year, such as the renovation of the Grandhotel Galya in the countryside, and a number of hotels under construction or under renovation in Budapest: Sofitel Budapest Chain Bridge, hotel in Kígyó street, VP36 Boutique Hotel, Paulay Opera Hotel, Hotel Paulay (Puro), Moxy Budapest Downtown by Marriott, and Hilton Garden Inn. Hotel Gellért in the capital city is also undergoing renovation and may be completed in 2027. Klotild Palace St. Regis Hotel and K36 Hotel and Student Hostel are also nearing completion and could open this year.

Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

EECFA 2025 Summer Construction Forecast

EECFA released its 2025 Summer construction forecast on 23 June. See a sample report and place your order on eecfa.com. To get discounts, you may contact us.

Southeast European construction markets up to 2027

According to Yasen Georgiev at Economic Policy Institute (EPI), EECFA’s Bulgarian research institute, total construction output in Bulgaria is anticipated to grow by 3% on average for 2025-2027 with a stronger growth in the middle of the period when the absorption of operational programmes and the implementation of the Recovery and Resilience Plan are to gain momentum. According to the sectoral breakdown, residential construction is expected to be the subsector with the weakest performance, while non-residential construction and particularly civil engineering are predicted to see stronger growth figures. Against this backdrop, the country’s economy is set to register a slower-than-expected growth in 2025 and 2026. In parallel, it is awaited to benefit from the effects from the full Schengen area membership effective from the beginning of 2025 and from the euro adoption expected on 1 January 2026.

Michael Glazer (SEE Regional Advisors) and Tatjana Halapija (Nada Projekt), EECFA’s Croatian members think that Croatia’s construction as a whole continues vibrant due to the combination of continuing transitioning-economy catch-up growth and large inflows of EU money. Both are beginning to diminish, however, and that will affect all construction segments, some more strongly and more quickly than others. In building construction several sectors have seen the end or are close to seeing the end of catch-up growth. Others, particularly those that benefit most from EU finance, are still going strong. Civil engineering continues to profit greatly from EU funding, and because of the poor initial condition of Croatia’s infrastructure after independence, much catch-up construction remains to be done. Certain government policies will have a great influence on specific building and civil engineering sectors. Those policies include the housing policies embodied in Croatia’s new National Housing Policy Plan until 2030, the new tax on real estate and the country’s renewable energy permitting and electrical grid hook-up fee rules.

‘Romania’s macroeconomic outlook remains positive, but more reserved as the political instability and fiscal uncertainty have done little to improve growth opportunities’ – says Dr. Sebastian Sipos-Gug, EECFA’s Romanian researcher at Ebuild. At the same time, he adds, the country has the largest government deficit in the EU, which will dampen public investment capabilities. All these will make it harder to finance public works and could negatively impact civil engineering. This is doubly worrying as this subsector countered the decline in other construction segments in 2024, and thus the outlook for total construction remains negative in 2025 and 2026 in real terms. Not all is gloom and doom, however. As inflation and interest rates come down, and employment indicators remain strong, private consumption could boost demand for residential and non-residential construction.

‘In 2025 Serbia’s construction is making new gains in building construction, while civil engineering has entered a period of consolidation after the strong expansion during 2023 and 2024′ – believes Dejan Krajinović, EECFA’s Serbian researcher at Beobuild. Building construction is supported by both public and private investments, boosted by the hosting of the EXPO 2027 in Belgrade. Non-residential construction is the main beneficiary of this event, particularly commercial, office and hotel segments, while residential construction is also keeping historically high volumes. Some delays are seen in civil engineering, but the overall performance is still strong with a long list of planned projects in all major subsegments. Domestic demand is still relatively strong, but economic growth and the level of investments are being muffled this year by uncertainties in the global markets, particularly the weak EU economy, international trade issues and the ongoing wars in Ukraine and the Middle East.

‘Total construction output in Slovenia is expected to decrease from the historic high of EUR 5,5 billion reached in 2023. In both 2024 and 2025, it could contract but remain above EUR 5 billion annually’ – as per the opinion of Dr. Aleš Pustovrh at Bogatin, EECFA’s Slovenian member institute. He predicts the sector to return to growth in 2026 and 2027, mostly on the back of a healthy growth in residential construction buoyed by decreasing mortgage rates. On the other hand, civil engineering is prognosticated to shrink significantly in 2024 and 2025 due to some large projects nearing completion, like the new railroad connecting Port Koper. Both non-residential and civil engineering depend to a large degree on public financing that was widely available in the post-Covid period but will become much less available in 2025-2027. Especially if the overall economic activity continues to slow down. This deceleration and more foreign labourers have also caused lower construction cost growth, but other challenges persist such as the additional bureaucratic burdens (changed permitting process, increase in tax, ongoing discussion on changes to short-term rental legislation, among others) and many external risks in the global economic and political environment. 

Eastern European construction markets up to 2027

‘In the forecast horizon, the construction sector of Russia will be under pressure from a range of macroeconomic factors, the main one being the high key rate, which will negatively affect the pace and volume of construction projects’ – according to Andrey Vakulenko at MACON, EECFA’s Russian research institute. The tight monetary policy and the reduced availability of mortgages will likely slow down housing construction, on the one hand. On the other, the high cost of project financing, the general cooling of the economy as well as reduced consumption and business activity will likely shrink the volume of investment in non-residential construction. However, these trends can partly be offset by high volumes of government financing of priority infrastructure and energy projects, which can support civil engineering and ensure near-zero growth in total construction market in 2025-2027.

Prof. Ali Türel, EECFA’s Turkish researcher says that Türkiye has been trying to control high inflation by raising the base rate and managing exchange rate increases through market instruments by the Central Bank and maintaining wage growth at zero or negative rates. This created financing difficulties for industries and businesses, reduced demand for basic consumer goods, and led to affordability problems for mortgage credits. Big declines in building starts and completions in Q1 2025 may also be related to these measures. Yet, the Central Bank’s inflation target for 2025 remains high at 24%. Positive real changes in housing prices relative to building construction costs encourage house building, while their negative real change compared to inflation may be the leading factor in the increase of home sales through equity financing when mortgage credits are not affordable for most households. Rebuilding the quake-damaged 870 thousand units requires about EUR 100 billion and these expenditures have been the primary factor of the large national deficits in recent years.

‘This year, in spite of the continuing war and the economic instability in the country, Ukraine’s construction industry shows signs of recovery and growth on the back of successful programs financing both the construction of new facilities and the reconstruction and restoration of infrastructure in eastern and southern regions’ – according to Prof. Sergii Zapototskyi at Uvecon, EECFA Ukraine. The World Bank estimates that reconstruction would require USD 486 billion. On the negative side for the sector are bureaucratic barriers in the urban planning legislation, shortage of workers caused by mobilization, shortage and high cost of building materials, and logistical difficulties. On the positive side for the sector is demand for housing and the need to restore damaged infrastructure. The near-term future of the industry depends on the level of security, the effectiveness of restoration programs and the volume of international investments.

Q1 2025 sees weak Activity-Start in Hungarian construction

2025 started off weak in Hungarian construction despite the much higher Activity-Start at the end of 2024 fuelled by launched major projects then. In Q1 2025 the value of started construction works greatly dropped compared to both the previous quarter and the same period of the previous year. The Activity-Start of EBI Construction Activity Report at current price was around HUF 570 billion in Q1 2025; the second lowest quarterly value since July 2020. At constant price, and if adjusted with price changes, it has been the second worst three-month Activity-Start since 2015.

Value of started building construction works fuelled by multi-unit residential projects

Building construction has slightly improved compared to the previous two weaker quarters: the value of started works was well over HUF 500 billion, 18% up from Q4 2024. The improvement, which was also evident at constant price compared to H2 2024, was attributable to the surge in multi-unit residential works. At the same time, Non-Residential Activity-Start continued to see the low levels of the last two quarters of 2024. In the first three months of this year, non-residential construction works of slightly more than HUF 240 billion started, the lowest quarterly figure since 2017. At constant price, no building construction works have started in such a low quarterly value in the past 10 years.

Among biggest building projects launched in Q1 2025 were mainly logistics buildings: CTP logistics halls in Vecsés (Phase 2) and Biatorbágy, and HelloParks logistics hall in Fót. Construction also began on Phase 2 of Building A of H2Offices in Budapest, and the Hungerit poultry processing plant in Szentes.

Critically low value of started civil engineering projects

Civil Engineering Activity-Start was extremely low in Q1 2025 with started construction works worth only HUF 31 billion. This has by no means been the lowest value recorded in the subsector since 2014, both at current and constant prices. Activity-Start in road and railways and in non-road and non-railways amounted to around HUF 16 billion, respectively. Sadly, not a single civil engineering project made it into the largest projects entering construction phase in the quarter.

Regional comparison: Budapest on the lead

According to EBI Construction Activity Report, Budapest had the highest value of construction projects started in Hungary in the last four quarters. And although its share in total Activity-Start slightly dropped, it still stood at 32%, exceeding the 20%-30% typical in the period between 2021 and 2023.

In Northern Great Plain, the region that previously was on the lead, 14% of projects started in Q1 2025. The share of Southern Transdanubia was 16%, while that of Southern Great Plain 11%. Western Transdanubia and Northern Hungary registered the lowest value at 5%, respectively. In Central Transdanubia, 7% of projects started, whereas in the Pest region, 10%.

Multi-unit residential projects shooting up

The latest EBI Construction Activity Report Hungary has found that 2025 started off greatly in the multi-unit residential segment as in the first three months the value of construction starts was almost HUF 300 billion at current price. It has been a record since 2014 and exceeds the previous quarter’s highest value (HUF 209 billion). Even at constant price, the growth in Activity-Start is a 39% rise over the previous quarter.

This increased activity comes as no surprise: the last quarter of last year already witnessed recovery with developers responding to growing demand and preparing for increased interest at the beginning of this year.

The market has confirmed these expectations, and as per ELTINGA’s Housing Market Report, the latest two quarters saw a record in Budapest in the number of sold new multi-unit dwellings. Although a major part of demand came from investors, the question is how long this can last. Developers might become more cautious with project starts towards the end of the year as demand might decrease following interest payments and maturing government bonds.

When it comes to completions, the value of completed multi-unit residential projects in Q1 2025 was around HUF 76 billion, a drop compared to both the previous quarter and the same period last year. At constant price, Activity-Completion in Q1 2025 has been the third worst value since 2019.

Regionally, looking at the past four quarters, Budapest accounted for 70% of multi-unit projects entering construction, while Central Hungary recorded slightly more than 72% of the value of such projects. Eastern Hungary had a 13%, while Western Hungary had a 16% share in Activity-Start.

Better Q1 2025 in industrial buildings and warehouses than in the construction industry as a whole

In Q1 2025 the total value of construction starts of industrial buildings and warehouseswithover HUF 150 billion was slightly higher than in the previous two quarters. True, if we look at the period between 2022 and H1 2024, it was the second lowest value. Last year, in addition to automotive industry projects, several food industry projects started such as Pick’s plant in Szeged, Master Good-Sága plant in Sárvár, or Félegyházi Bakery plant and warehouse in Kiskunfélegyháza.

In the first quarter of this year, as previously mentioned, the largest projects entering construction phase included several logistics projects such as CTP’s logistics halls in Biatorbágy and Vecsés, and HelloParks’ project in Fót. Besides, the construction of several plants began: Unilever’s deodorant factory in Nyírbátor, Phase 2 of Scheider Electric’s Duna Smart Power Systems smart factory in Dunavecse, or Kométa’s packaging plant in Kaposvár.

As for completions in the segment, industrial buildings and warehouses were completed at a value of HUF 250 billion in the first quarter of this year – the third highest value since 2014. Biggest completed industrial projects include CATL warehouse and metalworking plant in Debrecen and HelloParks AN1 logistics hall in Alsónémedi. And we expect to see further major completions this year.

Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

Bucharest’s drop in residential permit and completion

Written by Dr. Sebastian Sipos-Gug – Ebuild srl, EECFA Romania

Reading the recent blog post regarding permit and completion data one can see that the trend for residential permits in Romania seems to have taken a downturn since 2021, and this naturally raises the questions: What has happened? Has the market peaked or is it just a temporary setback?

The supply-side story

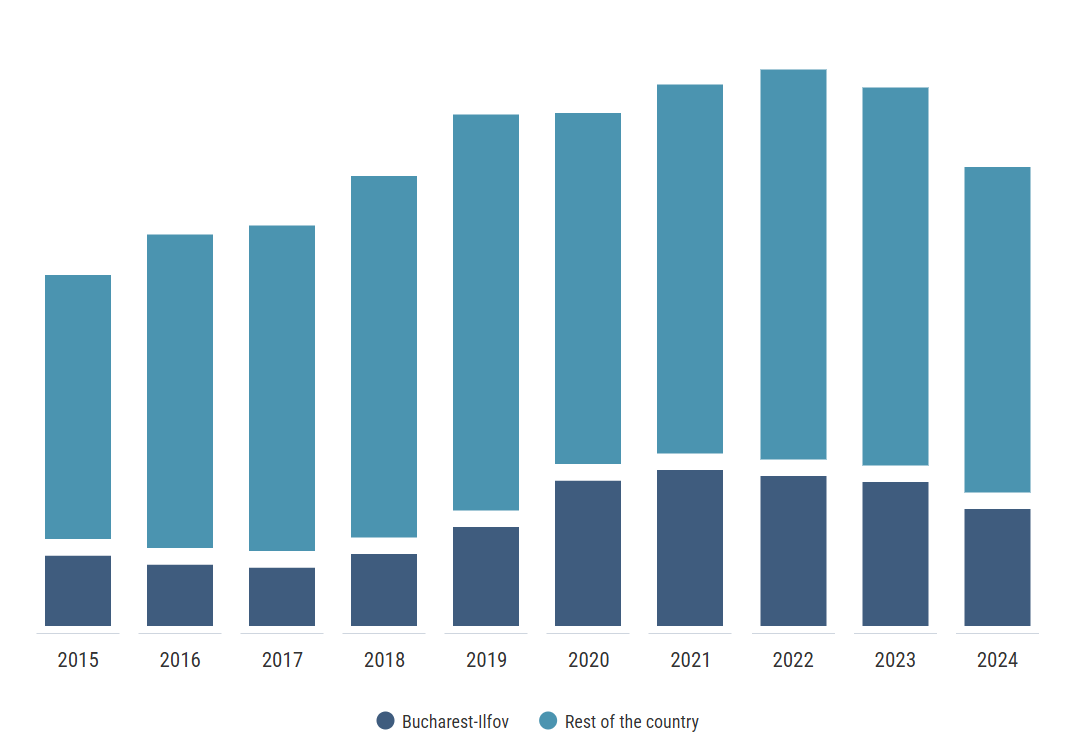
In order to attempt answering these questions, Dr. Sebastian Sipos-Gug, EECFA’s researcher on Romania, started by looking at permit data for a longer period and split by regions. The slowdown in 2023 and 2024 was present in most regions, but none of them was hit as hard as Bucharest where the useful area in residential permits nearly halved in 2024 compared to the peak of 2022. Thus, whatever effect led to the drop in permits, it disproportionately affected Bucharest.  While it remains by far the most active region, the drop is oversized when adjusted for its share of the market.

In case of Bucharest, a non-trivial amount of this effect could be explained by the gridlock in the urban planning area, with permits for all types of construction hindered by the cancellation in 2022 of the existing zoning plans which have yet to be replaced by newer versions. This makes it more difficult to gain permits for new developments, and could be, at least partly responsible, for the observed shrinkage in residential permits in the last two years.  

Figure 1: Useful area in residential permits, 2015-2024, Bucharest-Ilfov chart presented outside the map due to relative market size (Source: own calculations based on NSI data)

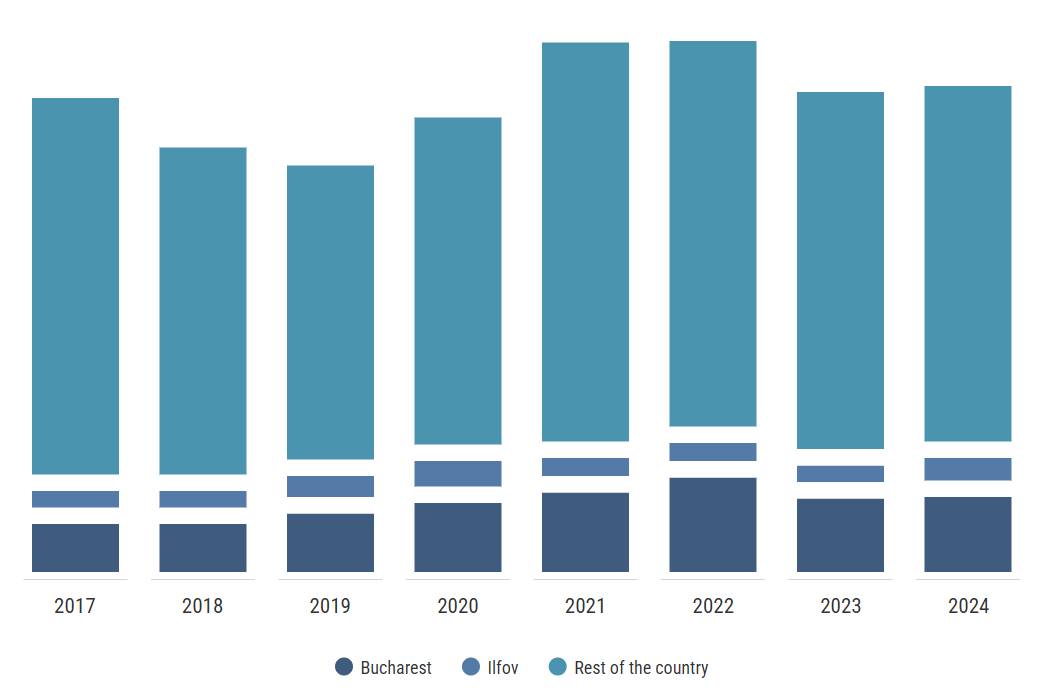
The next logical step seemed to be looking at other indicators such as completions and seeing what happened there. Indeed, they have also been on the decline with the number of completed homes country-wide in 2024 being comparable to that of 2018. Again, Bucharest-Ilfov saw a much larger drop in 2024 over the 2021 figures, standing at –33% compared to –12% in the rest of the country. 

Figure 2: Home completions between 2015-2024 (Source: own calculations based on NSI data)

The decline is quite apparent in the supply of new housing overall, but that the situation is much more dire in Bucharest.

The demand-side story

Could the decrease in supply be a response to lower demand? After all, if developers have difficulties selling stock, they are unlikely to start new projects.

Looking at the number of transactions, they indeed declined overall in 2024 compared to the peak of 2021, but the effect was much smaller with just around 10% fewer properties being sold in the whole country, while in the Bucharest-Ilfov region there was barely any change (-0.3%).

At the same time, prices of homes continued growing, but this time Bucharest (+20%) lagged behind the country (+27%), meaning that the price gap between the capital and the rest of the country is slowly closing.

Figure 3: Number of real estate transactions between 2017 and 2024 (Source: own calculations based on ANCPI data)

However, when comparing the growth in home prices to that of the rise in construction costs, the situation looks more dire. As of 2024, residential construction costs grew 41% over the 2021 level, far outpacing the increase in prices. This was partly due to increased materials costs (+32%), but also due to much higher labor costs (+60%) for construction workers. Since in January 2025 tax breaks for construction workers were eliminated and the minimum wage for them grew, it’s unlikely for the situation to improve in the short term, potentially discouraging developers from new investments until prices reach a place where they offset the costs and offer similar margins as before.

What does this mean for housing affordability?

This topic was touched upon last year, in another blogpost, with the conclusion that it is useful to look at affordability from two standpoints: cash buyers and mortgage takers, since increased interest rates can negate the effects of wage growth.

Taking a regional split into account this time, it’s noticeable, and perhaps slightly surprising that homes are more affordable in Bucharest as the wage gap between it and the country average is higher than the residential prices gap.

This took a turn, however, in 2024 as home affordability in Bucharest started to drop, while the national average remained more or less the same. If the previously mentioned issues that limit permitting are not resolved, we can expect this trend to continue in the future as well since a limited supply will mean higher prices.

Another factor that could limit future supply, at a national level, is developer funding. It used to be the case that developers would focus on presales and use very high downpayments in the project phase (up to 90% in some cases) to fund the construction work, without requiring a bank loan.

Since a high-profile scandal regarding a large developer brought this issue into the limelight, confidence in this type of arrangement has declined and buyers are less likely to accept paying high downpayments before construction has even started. Concurrently, there is a bill underway aiming to limit downpayments for unfinished buildings to 10%. Should developers resort to banking loans for their projects, it would make the market more stable but more expensive for them, leading to either lower margins, or higher prices.

Figure 4: Home affordability for cash buyers: sqm in an average 2-room apartment one could afford with average monthly net wage (Source: own calculations based on data from NSI and imobiliare.ro)

When it comes to home affordability for those using a mortgage loan, things are not looking better than they did last year. Inflation has proved to be stickier than expected, and the Central Bank is lowering reference interest rates slowly, meaning mortgages will continue to be relatively expensive in the near future.

While the higher wages in the capital again prove to be an advantage, making homes slightly more affordable than for the average Romanian, this indicator was also on the decline in 2024 for Bucharest, and stable for the rest, shrinking the gap between the two.

Figure 5: Home affordability for mortgage buyers: size of the home (in sqm) one could afford to buy with a mortgage loan, assuming a 25% downpayment, a 30-year term and a debt-to-income ratio of 40% of the average monthly net wage (Source: own calculations based on data from NBR, NSI and imobiliare.ro).

In the context of high energy costs, in 2021 construction costs increased. Since then, the situation has not improved dramatically, and it’s unlikely to change in the near future as inflation and high wage growth will keep an upwards pressure on them in 2025 as well.

Bucharest is doubly feeling the pain when it comes to new residential development. Adding to high construction costs, there are issues with urban zoning and permits approvals. The supply constraints mean higher prices, leading to slightly declining home affordability, especially for those relying on mortgages.

Figure 6: Construction costs for residential buildings (Source: own calculations based on data from NSI)

EECFA 2024 Winter Construction Forecast

EECFA released its 2024 Winter construction forecast on 16 December. Check out a sample report and purchase any of the 8 reports or the package of 8 reports at eecfa.com. For discounts, contact us.

Southeast European construction markets

Total construction output in Bulgaria is forecasted to grow by an average of 3.3% in 2024-2026, which is slightly above real GDP growth projections for the same period. The subsector breakdown shows that residential construction is expected to lose momentum, but this is likely to be compensated by a more dynamic performance of non-residential construction and civil engineering. In parallel, general economic activity in Bulgaria in the forecast period is to be influenced by the effects from the full membership in the Schengen area from 2025 onward and the prospects for the country to introduce the euro on 1 January 2026.

Croatian building construction presents a varied picture across subsectors, with anticipated output growth ranging from significantly positive to somewhat negative. Civil engineering is more uniformly positive, but certain sectors show the effects of the completion and commencement of large projects. Both building and civil engineering output growth will be strongly influenced by new government laws and regulations, the consequences of which, while likely to be large, are difficult to predict for both the short and medium terms. These include the new National Housing Policy Plan until 2030, the new tax on real estate and measures to balance the playing field between different types of tourism accommodations.

Despite the rise in investment, Romania will likely continue to see a stifled growth in construction in real terms due to costs remaining high. Stubborn inflation and the slightly disappointing macroeconomic performance combined with increased wages and still high interest rates create a less appealing environment for investors in building construction. On the bright side, high income and importsare indicative of strong demand for consumption and could translate to demand for construction. While infrastructure did well, the current political turmoil and uncertainty could hobble performance going forwards. Even assuming deficit remains high but stable, as the EC expects, it would continue to raise public debt and make financing further projects more politically difficult. As some downside factors could improve by then, construction growth is forecasted to return to positive in 2026.

Serbia’s construction is likely to have closed another strong year led by civil engineering, but non-residential also entered a new growth cycle with positive outlook boosted by public investments and the hosting of the EXPO 2027 in Belgrade. The construction of commercial, office and hotel buildings are all set to grow in the coming period, followed by education and health. Residential construction is already on historically high levels with a relatively stable performance. In civil engineering, road and railway construction continues unabated, breaking new record volumes on the way, but other segments also have an impressive project pipeline. The economy is set to expand by 4% in 2024 and 2025 on the back of strong consumption and high investment, so construction outputs may sustain formidable levels up to 2026.

Slovenia’s construction sector is expected to maintain post-pandemic levels with annual output consistently exceeding EUR 5 billion up to 2026 against the EUR 3 billion pre-pandemic. Public financing has been a key driver with national budget expenditure up from EUR 10 billion in 2019 to over EUR 15 billion in 2024, though there will be spending limits in 2025-2026. Civil engineering in the forecast period will be supported by major infrastructure projects. Residential construction is set to drop slightly first in 2024 before rebounding by 2026 driven by lower mortgage rates. Non-residential construction is forecast to grow steadily but remain dependant on the availability of public financing. Other challenges remain such as labour shortages, permit backlogs and high costs, but construction cost growth is set to stabilize at under 3% annually.

Eastern European construction markets

In 2024, the Russian construction industry fared better than previously expected driven by the high pace of project implementation and the massive budget support in civil engineering and non-residential construction. It could even offset the negative impacts of the decline in housing construction caused by the end of the mass preferential mortgage program. However, this positive momentum is expected to gradually fade owing to the tight monetary policy of the Central Bank and several other internal and external factors that are slowing down the economy in general and the construction industry in particular. In 2025-2026, the record budget expenditures planned within the framework of new national projects and other measures of state financing will likely maintain construction market volumes in Russia in the positive territory, but with minimal growth.

In Türkiye, increased interest rates and the Central Bank’s policy to reduce the depreciation of the national currency to curb inflation has not yet produced the intended outcomes. And high interest rates are blamed for shrinking industrial output and decelerated trade growth. The interest rate and the Central Bank’s policies had two major effects on the construction sector: big negative real rates of change in construction costs and housing prices. Housing sales are growing as real prices drop and rely on equity financing since mortgage loans have become unaffordable at high interest rates. Building permits in most segments decreased in Q3 2024, while completions had a positive trend. The government’s legal obligation to rebuild the earthquake-damaged 350 thousand buildings with 870 thousand independent units has been the main factor in huge budget deficits that impede the Government from providing sufficient funds for civil engineering projects.

As a consequence of the war ongoing for over 1000 days, Ukraine’s construction market is facing economic difficulties, limited resources, huge losses in buildings, hike in building material prices, lack of skilled workers and limited access to financing, topped with the unpredictability of government decisions and the instability of property rights. The destroyed homes of more than 1.5 million families create a huge demand. Non-residential construction also focuses on the restoration of destroyed buildings and the construction of new ones in safer central and western regions. Civil engineering is also boosted by the renovation of bridges, roads, railways, pipelines, communication and power lines. The ‘Unified portfolio of public investment projects’ recently approved by the government includes 750 big reconstruction projects on roughly UAH 2.36 trillion, while the state budget also has UAH 256.1 billion for public projects in 2025. First, the EUR 50 billion under the EU’s Ukraine Facility are to be used. Financing is also planned through international financial organizations and foreign governments. The priority is energy, transport, utility and public buildings such as schools.

Value of started projects in Hungary between January and September 2024 almost 17% down y-o-y

According to the Q3 2024 EBI Construction Activity Report Hungary, after Q2 brought a decline in the value of started construction projects, in Q3 a further decrease followed. Since 2016, the Activity-Start of less than HUF 360bln between July and September has been a new negative record, even at current price. These weak numbers were not even offset by the better Q1 and Activity-Start accounted for slightly more than HUF 1800bln. The value of projects entering construction between January and September 2024 was nearly 17% lower than in the same period of 2023.

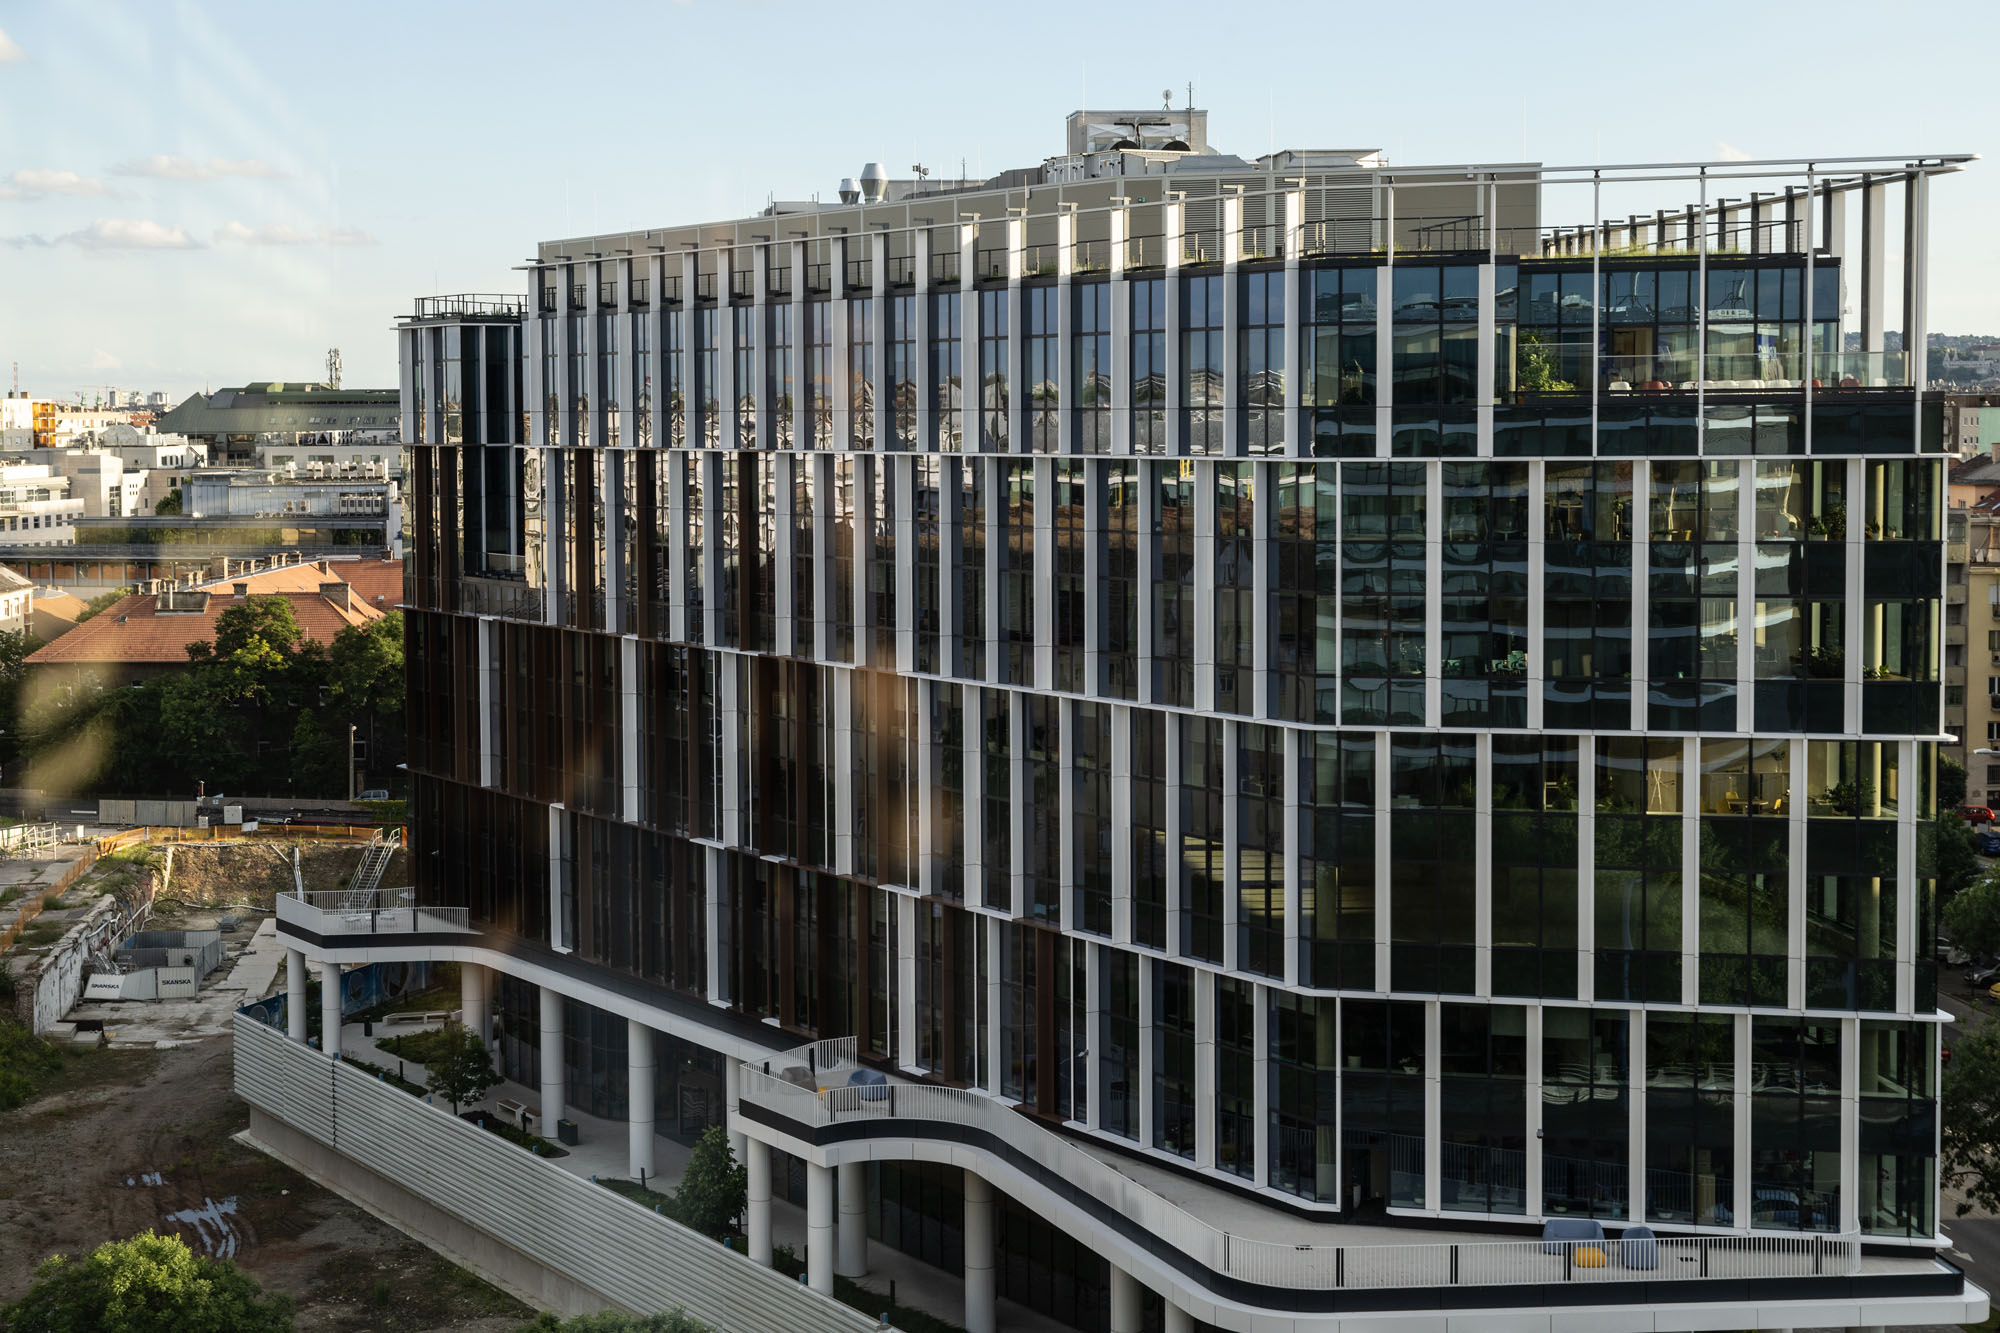
Photo by Hajnalka Hurta

Shrinking Building Construction Activity-Start

Q3 saw a continued decline in Building Construction Activity-Start with only HUF 310bln worth of started works. Except for the pandemic year of 2020, only 2017 and earlier years saw lower quarterly numbers. Looking at the first 9 months of this year, the value of started construction works was slightly less than HUF 1360bln, 15%-22% lower than in the same period of 2021-2023. At constant price, the drop was even more considerable: since 2014 there has not been a lower Activity-Start in the first three quarters than this year.

Multi-unit housing constructions posted a slight decrease in Activity-Start in Q3, but non-residential projects registered a larger drop with only HUF 200bln worth of projects entering construction phase between July and September. In the first 9 months, the Activity-Start of non-residential constructions was around HUF 1000bln, 21%-27% lower at current price than in the same period of 2021-2023. At constant price, the last time the number for the first three quarters was lower than this year’s was in 2014.

The largest construction projects launched between July and September 2024 included Lidl’s logistics center in Kiskunfélegyháza, HelloParks Páty PT5 logistics hall, Pick’s production plant in Szeged, Intretech’s plant in Kapuvár, Rheinmetall’s hydrogen and e-mobility parts production plant in Szeged and IGPark’s logistics hall in Debrecen. The construction of the hotel in Kígyó street in Budapest also started. Out of the 10 biggest projects in the quarter, 5 were multi-unit residential buildings or dormitories.

Civil engineering Activity-Start hits rock bottom

There was a further decline in civil engineering after Q2, Activity-Start in Q3 was only less than HUF 50bln – a new negative record of the last 8 years. But in terms of Activity-Start in the first 9 months, the 2024 result is not much better either. The value of construction works started in the first three quarters at current price has not been lower than this year since 2016, while at constant price it was the negative peak of the last 10 years.

Compared to the same period in 2021 and 2023, Activity-Start between January and September this year was 22%-24% lower, while it was only a little more than a third of the exceptionally high 2022.

Within civil engineering, only a negligible railway construction project started in Q3, and the value of road construction projects was also very low. In the first three quarters, road and railway construction accounted for roughly 45% in Activity-Start, their value slightly exceeding HUF 200bln.

Due to the rather low civil engineering activity, hardly any civil engineering project could get into the list of biggest projects. Only the wastewater projects in Dejtár agglomeration and the Rétság agglomeration are worth mentioning.

Budapest leads still

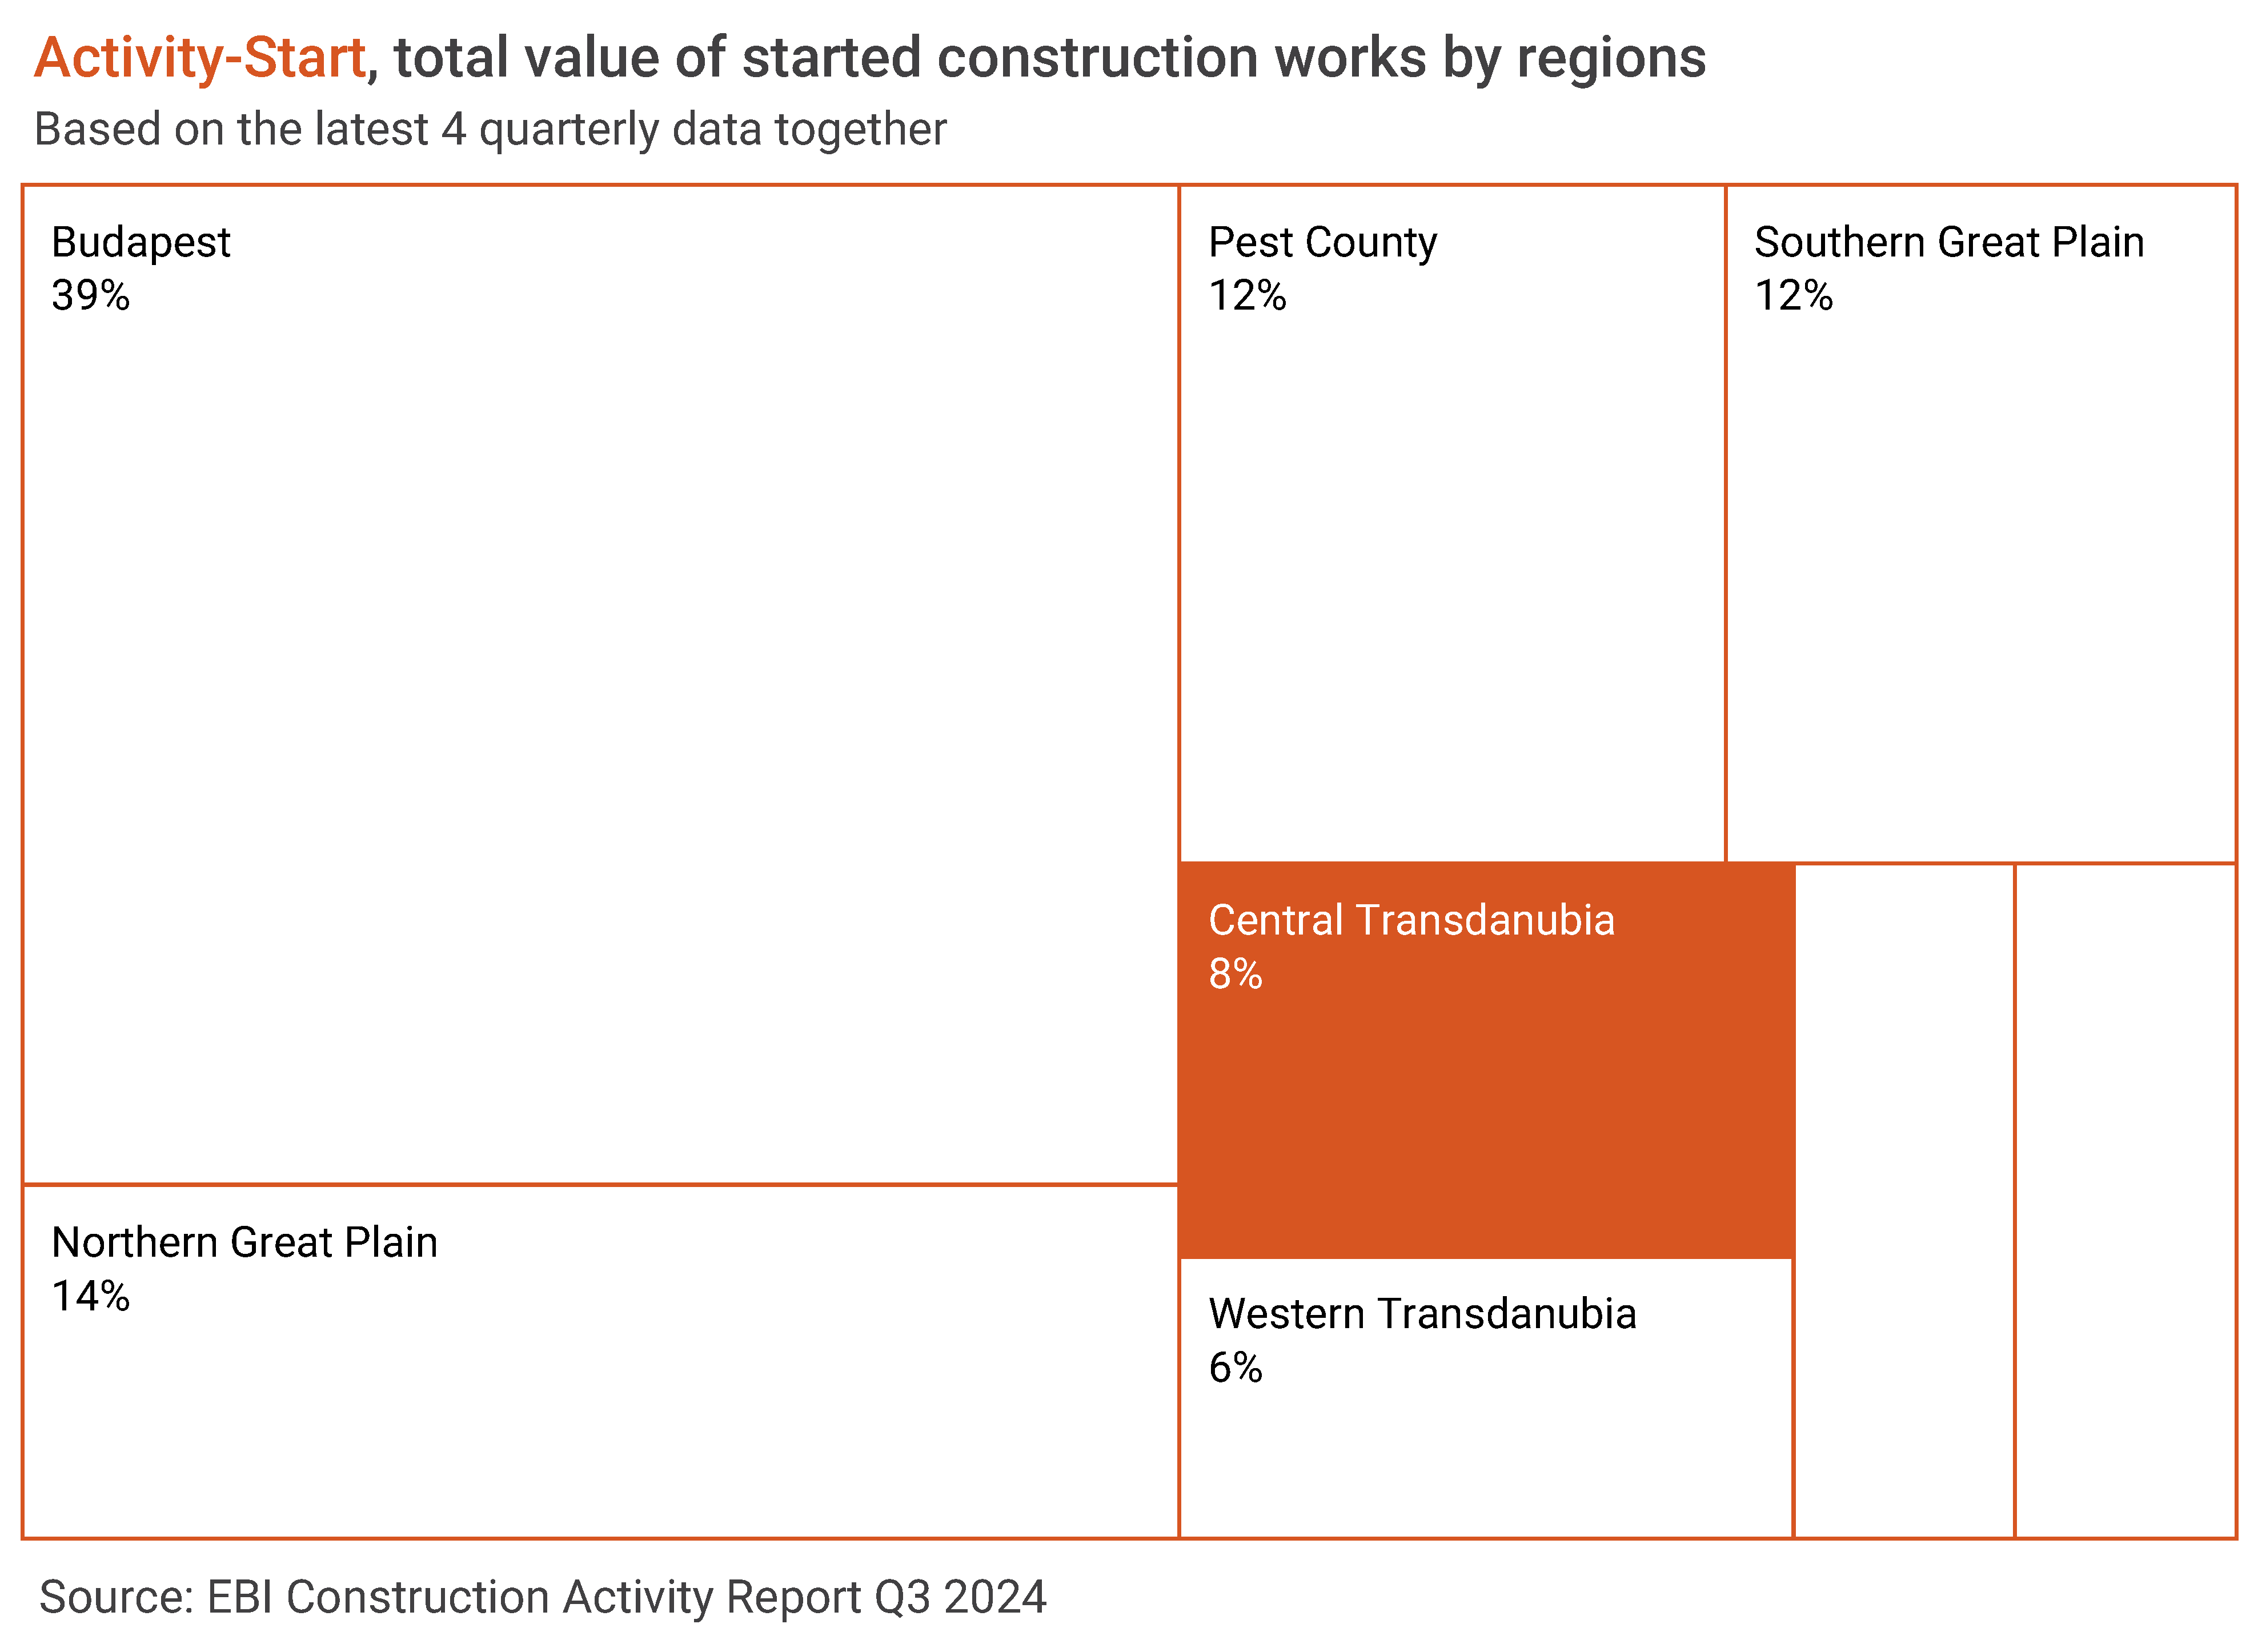
Looking at the last 4 quarters, 39% of all started construction works were in Budapest. The second largest Activity-Start was characterized by the Northern Great Plain (14%), followed by the Southern Great Plain and Pest County (12%). Northern Hungary and Southern Transdanubia recorded the lowest value of started construction works with their respective share of around 5%.

Multi-unit construction works are keeping up

Even though somewhat fewer multi-unit housing constructions started in Q3 than in Q2, Activity-Start significantly exceeded Q1. Construction works started in the segment on slightly more than HUF 100bln. Looking at the first 9 months of the year, there was an overall higher Activity-Start at current price than in the same period of 2019-2023. The value of projects entering construction was roughly the same as in the same period of 2022. At constant price, the Activity-Start for the first 9 months of this year outstripped the first three quarters of 2023; yet it was the second lowest since 2016.

This suggests that developers are still cautious with project starts even though this year’s demand for new homes increased compared to last year’s. Based on housing market trends, supply is expected to grow. A strengthening demand and rising prices may encourage more investors to start projects, and thus Activity-Start in multi-unit construction works may also increase in the future.

In Q3 the value of completed multi-unit housing buildings continued to drop, barely surpassing HUF 60bln. At the same time, in the first 9 months, approximately HUF 265bln worth of such buildings were completed, a slight rise over the same period last year. For the time being, a larger volume of homes is expected to reach completion in the last quarter, however, due to project delays, some may only be completed next year.

The biggest share of multi-unit residential constructions still started in Budapest. Based on the data of the last 4 quarters, the share of the capital city was around 60%. Eastern Hungary accounted for 14% of the Activity-Start, while Western Hungary for 24.5%, up from the previous quarters.

Central Transdanubia

Activity-Start in Central Transdanubia was roughly HUF 40bln in all three quarters this year. Thus, in the first 9 months, construction projects started at a total of HUF 123bln, a major drop compared to the same period of previous years. In the first 3 quarters of 2023, Activity-Start in the region was almost HUF 200bln, while in the first 3 quarters of 2022, it reached around HUF 300bln.

After the weaker Q1, Activity-Start for building constructions in Central Transdanubia in Q2-Q3 was roughly at last year’s levels. Thus, overall, the value of projects entering construction was around HUF 100bln in the first 9 months of this year, lower than in the corresponding period in 2023, and particularly lower than in the same period of 2021-2022.

The outstanding building construction Activity of 2021-2022 was boosted by the start of several big-league projects in 2021 (SK On’s battery factory in Iváncsa, Alba Aréna multifunctional hall in Székesfehérvár) and in 2022 (Kovács Katalin National Kayak-Canoe Sports Academy, the renovation of the church buildings in the castle quarter of Veszprém).

Projects entering construction phase between January and September 2024 in the region included the Huayou Cobalt-Bamo cathode factory in Ács and Phase 3 of Campus Lane Condo in Székesfehérvár.

In the first 9 months of 2024, hardly any civil engineering projects started in Central Transdanubia and the value of started works only reached a bit more than HUF 20bln. Among major civil engineering projects this year only Phase 1 of the dam between Mária-Valéria Bridge and Prímás island ramp can be mentioned. Last year bigger-value civil engineering projects started in the region in Q3 and Q4, for example, several water utility or wastewater projects, and the Biatorbágy-Szárliget railway line.

Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

Q2 registers historically low quarterly Activity-Start in Hungarian construction, but H1 is not so bad

As per the latest EBI Construction Activity Report Hungary, in the second quarter this year started construction works barely exceeded HUF 400 billion – the lowest quarterly Activity-Start even at current prices since 2016. But due to the exceptional Q1 value, H1 2024 overall did not show a massive decline (only -11%) over H1 2023. Compared to 2021, however, the drop was 18%, and against the exceptionally good H1 2022, the decline was a whopping 45%. And at constant prices, Activity-Start was the negative record of the past 9 years.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). For more details on how to obtain the full report, please contact us.

Lowest quarterly value of started building construction works since 2020

As per EBI Construction Activity Report Hungary, Q1 2024 saw a high Activity-Start but was followed by Q2 that recorded a decline in buildings as well. The value of started building construction works did not reach HUF 360 billion – the lowest quarterly figure since 2020. Overall, the subsector was characterized by a weaker Activity-Start even in the first half of the year: compared to H1 2023, the value of started construction works dropped by 11.8%, while over the same period of 2022 and 2021, at current prices, the decline was almost 30% and 21.5%, respectively. At constant prices, only H1 2014 was weaker than H1 2024.

Most of the decline occurred owing to the more moderate non-residential project starts. The decrease in multi-unit residential buildings was much smaller and the value of started construction works was roughly at the level of Q1. In non-residential buildings, Activity-Start was slightly higher than HUF 260 billion between April and June this year (a drop of almost 43% over Q1) but was also much lower than in the same period of the previous 3 years. Looking at individual quarters between 2021 and 2023, this year’s Q2 was the second lowest at current prices, and at constant prices, it was the lowest value since 2013. Due to the weaker Q2, Activity-Start in H1 2024 was also lower than in the same period of the previous 3 years at current prices. At constant prices, it was only H1 2014 that saw a lower value.

Biggest-league building construction projects launched in Q2 this year comprised the construction of MBH Bank HQ in Budapest, Phase I of BYD electric car factory in Szeged, and Huayou Cobalt-Bamo cathode factory in Ács. The construction of Moxy Budapest Downtown (hotel) and that of several multi-unit residential buildings also began.

The value of civil engineering project starts hit rock bottom in Q2

The stellar numbers in Q1 were followed by a massive decline in Civil Engineering Activity-Start of EBI Construction Activity Report Hungary between April and June this year. Q2 brought minimal civil engineering project starts, and the value of started works did not reach HUF 70 billion – the lowest quarterly value since 2016. However, comparing the first half of the year with previous years, 2024 is not exceptionally bad. The value of Activity-Start was 10.5% and 9% less than in the same period of 2023 and 2021, and it even exceeded that of 2020. There was a major drop only compared to the outstanding figures between January and June 2022. Within civil engineering, in H1 2024 road and railway construction works accounted for around 45% of Activity-Start and their value did not go up to HUF 200 billion.

It is very telling about the rock-bottom level of Civil Engineering Activity-Start that in the period between April and June this year no civil engineering project could make it to the top 10 biggest started construction projects.

Most construction works continued to start in the capital city

Looking at the past 4 quarters, the largest share of construction works again started in Budapest. The capital city’s share in the nationwide Activity-Start even surpassed 40%. Northern Great Plain had the second largest share, but its 13% was a great drop compared to the 20%-30% of the previous quarters. Pest County came third with 12%, while the smallest share of projects started in Southern Transdanubia with only 5% of launched construction projects in the last 4 quarters.

Practically no change in the value of started multi-unit residential projects

The latest EBI Construction Activity Report Hungary has found that after Q1 2024, in Q2 the value of multi-unit residential construction works started during 3 months was almost unchanged with a total of slightly more than HUF 90 billion. In the first half of this year, Activity-Start in the segment was less than HUF 200 billion, roughly corresponding to the level of the same period in 2021. At constant prices, although in H1 2024 the Activity-Start of multi-unit residential construction exceeded the one in H1 2023, it fell short of the one registered in the January-June period of previous years. It was only in H1 2015 when it was lower. Nevertheless, compared to other construction segments, multi-unit performed much better in Q2: the 10 largest-scale projects entering construction phase included several multi-unit ones, even with just over 100 flats.

The value of completed multi-unit residential construction works shrank in Q2 against Q1, but it stayed high, outstripping HUF 200 billion in H1 2024, making it the strongest first half year recently. Activity-Completion in H1 2024 was almost 42% higher than in the same period of 2023 and even surpassed the record H1 2020 by more than 22%. Further on, Activity-Completion may continue to be high, and, based on expected completion dates, this year may break a new record.

During the last 4 quarters, the largest share of multi-unit residential construction works continued to start in Budapest whose share also grew compared to the previous quarter with two-thirds of Activity-Start. Eastern Hungary’s share was 15.5%, while in Western Hungary 16.6% of such works began.

Southern Great Plain saw some growth in half-yearly Activity-Start

Southern Great Plain also saw some expansion in construction during the first half of this year, even though Q2 brought a decrease after Q1 – as per the latest EBI Construction Activity Report Hungary. Activity-Start here amounted to HUF 126 billion between January and June 2024. Building construction projects contributed most to the Activity-Start of this region: the value of started construction works in H1 2024 was HUF 110 billion – the level of H1 2023. But it was also true for regional building constructions that the higher Q1 values pushed up the half-yearly ones and Q2 brought a more moderate Activity-Start. Within buildings, multi-unit residential buildings represented a minimal level in the region, as in previous years, only 6% of such projects nationwide started here in the first half of the year.

Among the biggest non-residential projects entering construction phase in H1 2024 in the region were Benepack’s packaging materials factory in Makó, Mercedes-Benz battery assembly plant in Kecskemét, and Phase I of BYD electric car factory in Szeged. These projects were also considered large in terms of works started in recent years: in value, between 2021 and 2024 they ranked second, third and fifth, respectively.

Hardly any civil engineering project began in Southern Great Plain this year. Activity-Start in civil engineering in H1 2024 was less than HUF 16 billion – one of the lowest half-yearly results in recent years. Civil engineering works in the region reached an outstanding value in late 2021 and in early 2022 that saw the construction start of the Békéscsaba-Lőkösháza railway line, the Soroksár-Kelebia section of the Budapest-Belgrade railway line, and the Kecskemét-Szentkirály section of M44 expressway whose total value was hundreds of billions of Hungarian Forints and whose construction is still ongoing.

Article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

EECFA 2024 Summer Construction Forecast

EECFA, our construction forecasting cooperation in Eastern European countries, released its 2024 Summer construction forecast on 25 June. View a sample report and buy any of the 8 reports or the package at eecfa.com. For discounts, contact us.

The expansion phase was over in 2023 in SEE as a whole, but the current contraction is not foreseen to last as long as the latest one after 2008. By 2026 this region could return to around its previous peak. The EE region as a whole is expanding, and we are still optimistic all the way on the horizon.

A closer look reveals that only Romania, the largest market, is behind the overall setback of the SEE region. Here the previous peak is not expected to be reached soon. Elsewhere in the region further expansion is our current view. Serbia’s trajectory is a bit different, but the market could stay at a high level despite the drop next year. Recovery in Türkiye is forecast to be so strong that it could well counterbalance a shrinking Russia. Ukraine is coming back from a very low level, hence the relatively good growth figures.

Southeast European construction outlook up to 2026

Bulgaria’s economy is set to grow by almost 2% in 2024 and 3% in 2025, while the country is heading to a eurozone membership, most likely in 2026. In parallel, construction output is forecasted to decline year on year in 2024-2026 due to expected drop in residential construction and heterogeneous, yet positive performance of the non-residential one. Civil engineering bears a potential for an accelerated growth if EU funds’ absorption bounces back and public investments in infrastructure speed up. 

Croatian civil engineering is moving into even higher gear now, especially with the recent update to the TEN-T Network, which greatly benefited Croatia. Accordingly, output in most civil engineering sectors will rise. Building output presents a more mixed picture, with some sectors having reached or come close to peak output, while others are thriving.

The outlook for Romania’s construction sector remains negative this year. Inflation is shrinking, but more slowly than desired, keeping interest rates relatively high for longer and impacting financing costs. Also, the switch between the EU programming periods, combined with still high construction costs and an election year, will mean lower efficiency in starting and implementing long-term projects. Because the macroeconomic outlook is good and if the other issues are resolved, by 2026 construction might start growing again.

Serbia is expecting to see more stabilization in the construction sector this year, with both building construction and civil engineering estimated to stay in the black. The latter is very close to recording a consecutive double-digit growth in 2024. The economy is picking up, interest rates are slowly receding, so there is confidence that construction can sustain high output levels. Demand stays relatively strong, while stable prices are to keep investments high this year.

Slovenian construction is forecasted to surpass its record 2023 output this year and continue its growth trajectory into 2025, exceeding EUR 6 billion for the first time. Major civil engineering projects will likely drive this growth, bolstered by flood reconstruction efforts. Public investment in housing is planned but is contingent on future public funding availability that will also impact non-residential construction. The industry faces workforce shortages, but increased immigration and declining construction costs are expected to mitigate these issues, supporting further growth.

Eastern European construction markets of EECFA up to 2026

In Russia, the increase in people’s solvency, the restoration of business activity and dynamic economic development ensured growth in construction output last year, but recovery trends are slowing down owing to both external restrictions and internal negative factors. The residential and civil engineering construction subsectors remain key for the industry, but their dynamics depend on the level of government participation and the volume of allocated budget funds. Even though negative trend is forecasted for the residential subsector in the coming years, the drop in overall construction output in 2024-2026 is not predicted to be significant as the market will be supported by the construction of export infrastructure projects.

Türkiye’s economy has been greatly affected by last year’s earthquakes that caused great human and material casualties, requiring the rebuilding of destroyed homes, workplaces, and infrastructure. The government’s costly obligations coincide with a return to conventional economic policies that require austerity. Massive reconstruction spendings have caused huge budget deficits and civil engineering is worst affected by this. Increased interest rates have created affordability problems for bank loans, mostly mortgage ones, so home purchases rely mostly on equity financing and serve as a hedge against inflation. Home permits in Q1 2024 rose due to permits issued in earthquake-hit regions. This, and the private sector’s returning appetite in most commercial building segments, aligns with the expected high GDP growth.

Ukraine is making great progress in overcoming the consequences of the full-scale invasion, showing economic growth. The issue of reconstruction is acute, though. The main problems in the market are rising prices and shortage of building materials, growing costs of logistics and a shortage of skilled labour. In energy the immediate restoration of energy generation facilities is required to provide stable electricity. State and international programs for the restoration and construction of housing will likely contribute to the revival of the construction market. In the coming years, the future of the market, more than ever, will depend on three things: results on the battlefield; Ukraine’s subjectivity in the international arena; and the ability to protect its interests against Russian diplomacy. 

Hungarian construction industry kicked off well in 2024

The value of construction works launched in three months rose in Q1 2024, Activity-Start hasn’t been so high in the last six quarters. EBI Construction Activity Report Hungary Q1 2024 measured the total value of started construction works at HUF 807bln. Looking at the period between 2018 and 2023, there were very only five quarters when Activity-Start surpassed this number. At constant prices, Q1 2024 was also considered good when looking at the period since June 2022. Nevertheless, when compared to the period between 2018 and H1 2022, it fell into the lower range.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). For more details on how to obtain the full report, please contact us.

Building construction failed to improve in Q1 2024

Building construction could not regain senses in early 2024: Activity-Start was at the level of the last quarter of 2023. The value of started construction works was slightly more than HUF 400bln, almost the same as between October and December last year, but 17%-26% lower than in the first quarters of previous years. At constant prices there was a decline in the value of started building projects: last time Activity-Start was lower was in Q4 2015.

The Activity-Start indicator of non-residential buildings slightly grew in the first three months of 2024 compared to Q4 2023, thus exceeding HUF 350bln. Yet, examining individual quarters between 2021 and 2023, Q1 2024 was the second lowest. At constant price, the last time Activity-Start was lower than in Q1 2024 was in 2015. In case of housing construction, 2024 started better than 2023, but the value of started construction works continued to drop after Q4 2023.

Biggest building projects launched in the first three months this year mainly included logistics and industrial buildings, like the construction of Mercedes-Benz battery integrating plant (Kecskemét), Weerts Ebes logistics hall (Ebes), Benepack packaging materials factory (Makó), Phase I of Evoring electric car parts factory (Jászfényszaru), building C of VGP Park logistics center (Győr), and the storage hall and HQ of Rossmann (Üllő). Large office projects such as Zugló-Városközpont Office7 and several multi-unit residential projects also started, as well as the construction of Hilton Garden Inn Hotel (mixed-use) and the development of Hungaroring Paddock.

Civil engineering getting back to life

After several weak quarters, civil engineering seems to have improved and Activity-Start in Q1 2024 was nearly HUF 400bln, an increase of roughly 70% against Q1 2023. The improvement was visible in non-road and non-railway constructions and in road and railway ones alike. The former saw a 180% growth over the first quarter of last year, but Activity-Start was more than 50% higher than in the last quarter (which was also stronger). The value of non-road and non-railway projects at current price was last higher in Q1 2017 than in Q1 2024, but even at constant price, it has been the fourth highest Activity-Start since 2020.

In road and railway constructions, the recovery was mainly due to the Ferencváros-Kelenföld railway line 1 project, considered to be the highest-value work started in Q1 2024 in the entire construction sector. The Southern Industrial Park in Nyíregyháza and the flood protection facility in Esztergom were also among the biggest started civil engineering projects.

Budapest took the lead again

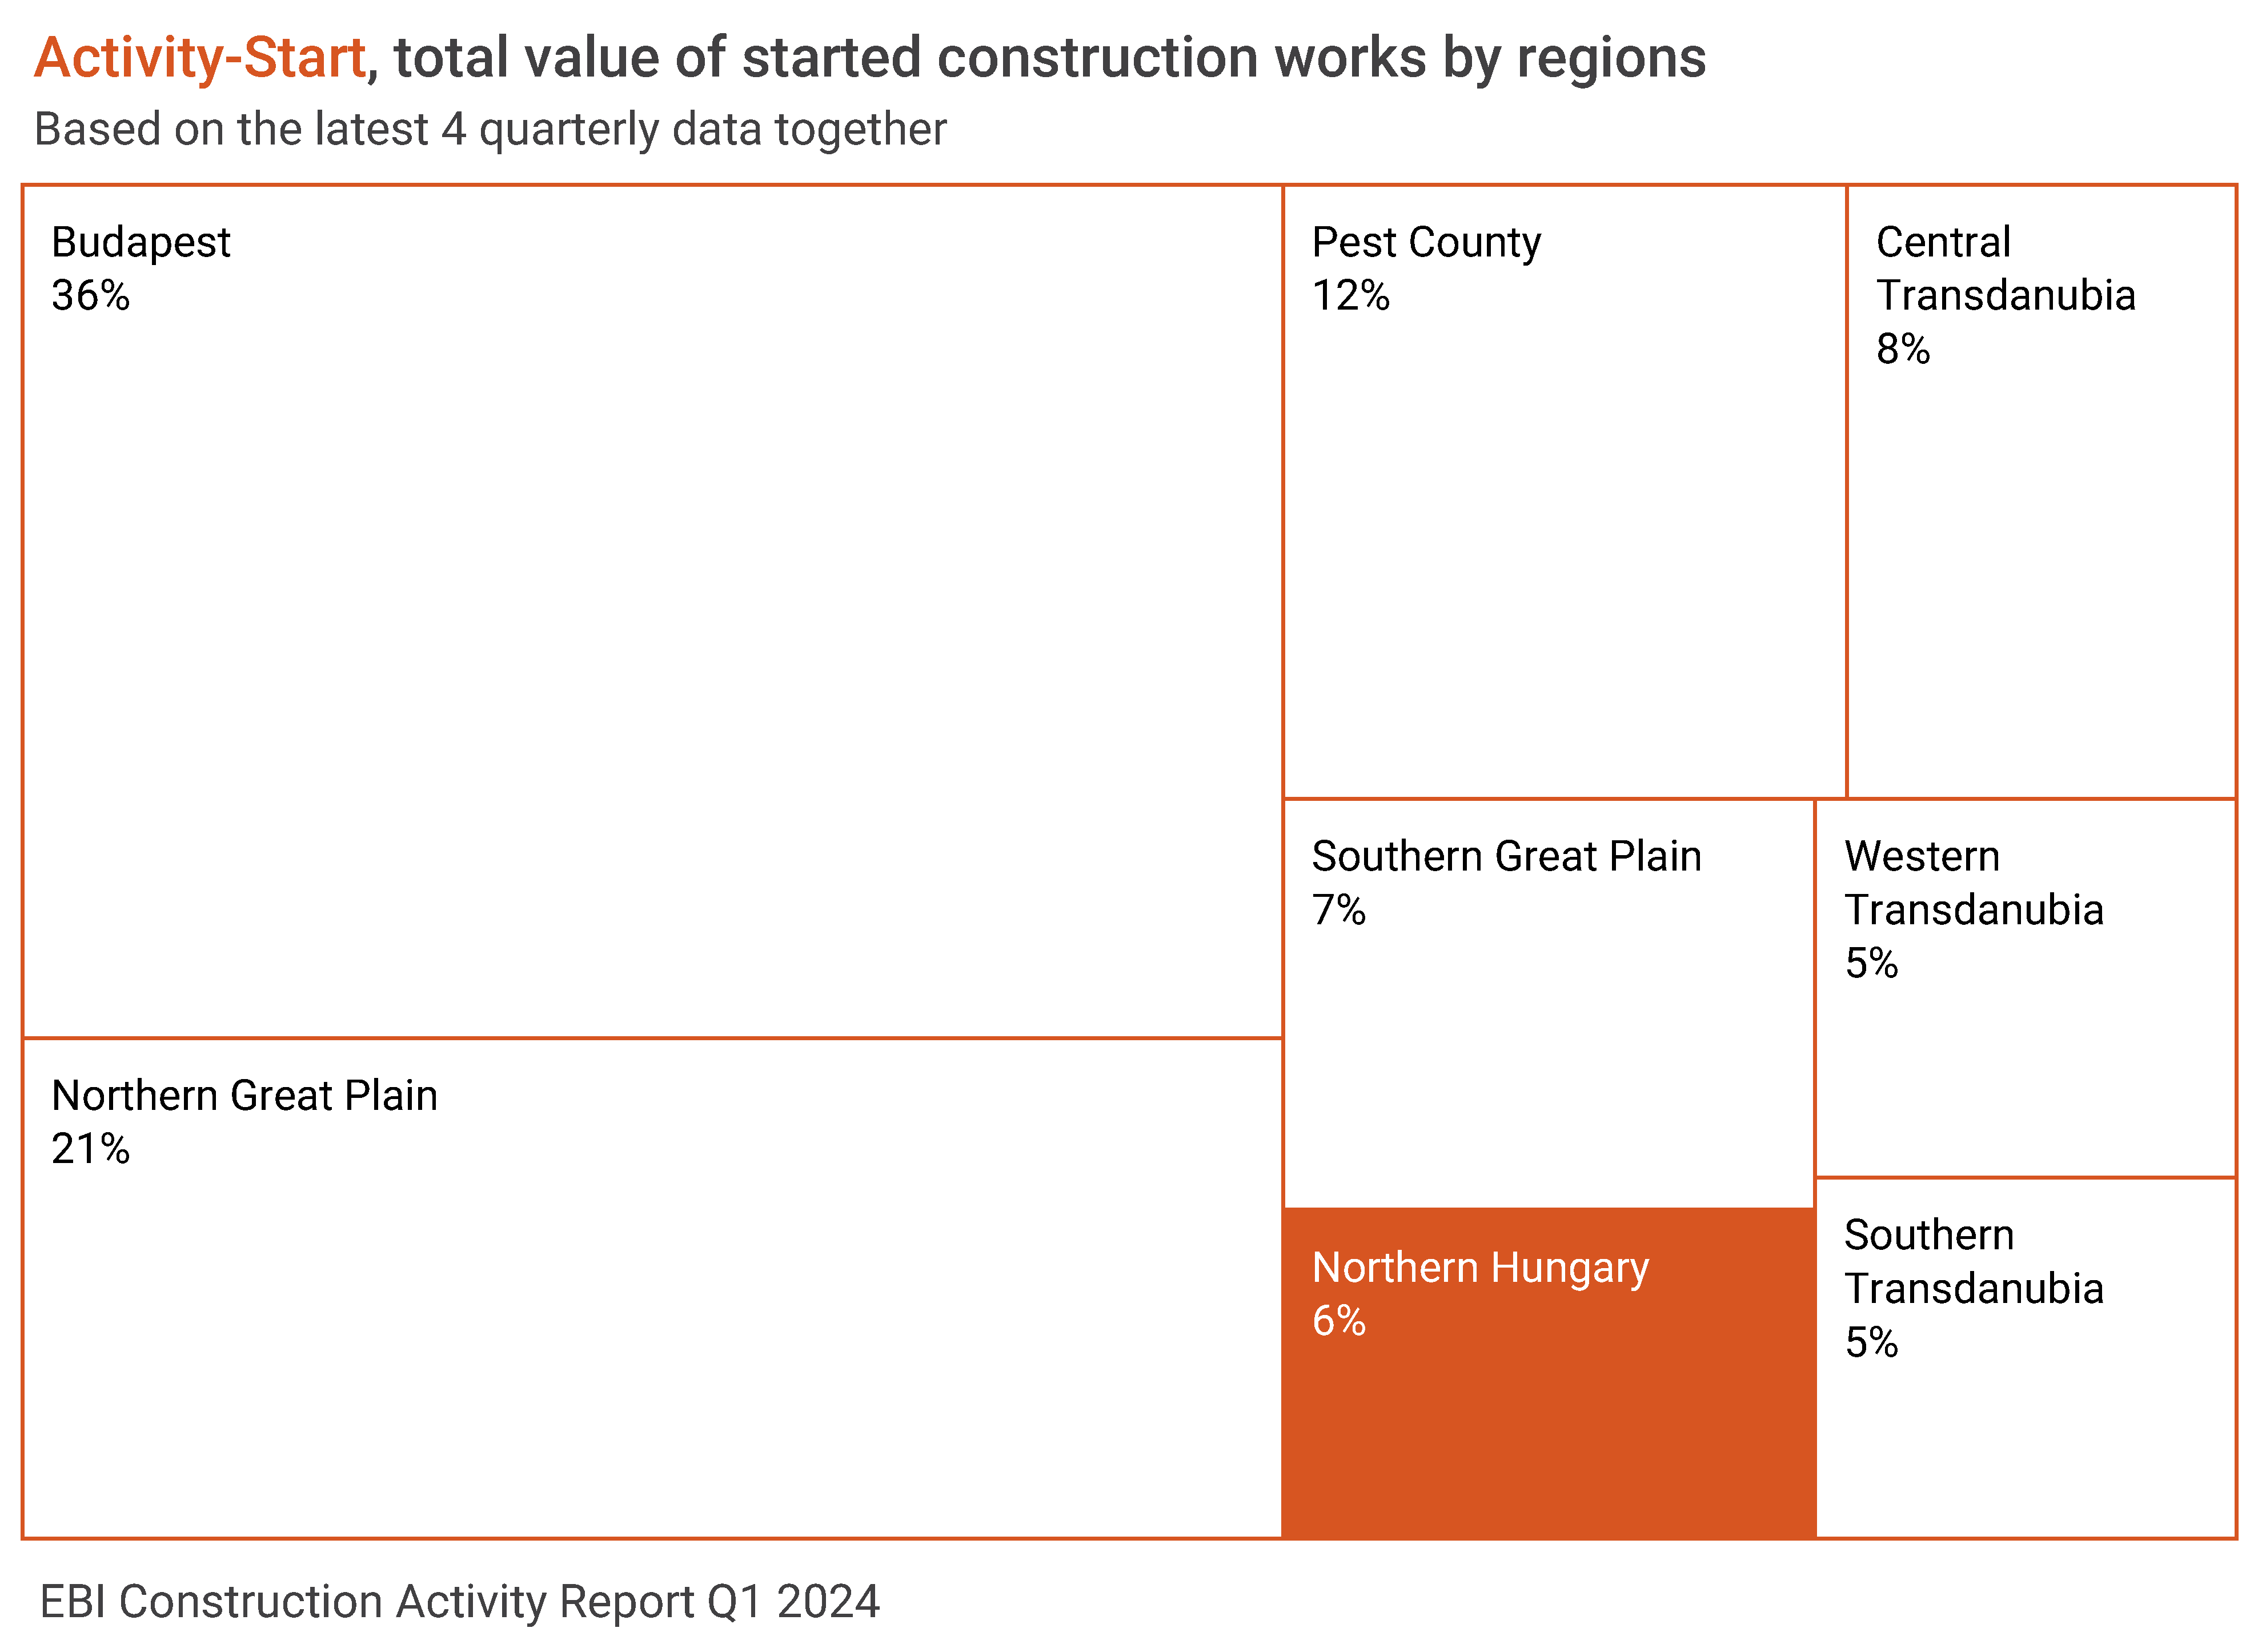
Looking at the construction works started in the last four quarters, the highest value ones were in Budapest whose share in total Activity-Start was 36% (the 20%-30% in the last quarters). Northern Great Plain, the leader in previous periods, slipped back to the second place (21% of works started here). Southern Transdanubia had the lowest Activity-Start (its share barely exceeded 5%), Western Transdanubia had a share of 5%, while Northern Hungary had 6%.

Multi-unit residential building still stumbling

Although this year started better than the last one in multi-unit residential construction, the value of such started projects dropped further and was lower than in the last two quarters of 2023. Starting from Q2 2016, the segment registered the fourth lowest Activity-Start in Q1 2024 at current price. Looking at constant price, the value of works started in early 2024 has been the third lowest since 2016.

Yet the market outlook improved compared to the previous year. Mortgage rates sank greatly by end 2023 and continued to do so in 2024, while the economic outlook also became better. The rosier environment has lured buyers back to the residential market with the revival already noticeable in the first quarter of this year, both in the secondary and primary markets. Good news: the reduced VAT rate for new homes has been extended, so instead of end 2024, building permits can be obtained by end 2026 and homes can be sold at 5% VAT until 2030.

Many multi-unit residential projects were completed in the first three months of this year with their value exceeding HUF 120bln, the highest quarterly Activity-Completion since 2021. Many units are expected to be completed this year, too, however, in the long run, the value of completions is set to decrease due to previously shrinking construction works.

Looking at the past four quarters, Budapest accounted for 63% of multi-unit residential projects entering construction phase, and slightly more than 64% of the value of such projects was concentrated in Central Hungary. Eastern Hungary accounted for 14.8% of the Activity-Start, while Western Transdanubia’s share was 20.9%.

Northern Hungary in focus

Although the year started well in the construction industry nationally, it is not true to Northern Hungary where the total value of started construction works did not reach HUF 22bln. It was the lowest quarterly amount in 2018-2023.

In Northern Hungary, both building construction and civil engineering shrank in the first quarter of this year. Building Construction Activity-Start was one of the lowest in the quarters of recent years with the drop clearly attributed to non-residential buildings. Although the value of the started multi-unit residential constructions grew at the beginning of 2024, the region still has a very low willingness to build such buildings (its share in the national multi-unit residential Activity-Start was less than 3% in the last 4 quarters). Low activity in multi-unit residential works is well illustrated by the fact that, despite the improvement, no project made it into the largest construction projects in the region in Q1 2024.

Among non-residential buildings, the biggest regional projects launched between January and March 2024 include Phase II of Horváth Rudolf logistics centre in Hatvan. In recent years the largest ones comprised the logistics hall of Robert Bosch Power Tool MC301 in Miskolc (starting in 2023), the manufacturing plant of GKN Automotive in Felsőzsolca (starting in 2022), Chervon manufacturing plant and the reconstruction of Diósgyőr Castle in Miskolc (starting in 2021).

In early 2024 Civil engineering Activity-Start in Northern Hungary continued to drop. Looking at the period of 2018-2023, the total value of construction works started in Q1 2024 was the third lowest: Activity-Start did not reach HUF 4bln. In Q1 civil engineering projects were not even among the largest started ones. The value of civil engineering projects started in the region was higher in Q2 2023, in Q2 2022 and in Q3 2021 when such projects entered construction phase as the Szentdomonkos-Borsodnádasd section of main road 25, the Sajószentpéter-Berente bypass 260, and the Gesztely-Szerencs section of main road 37. The peak so far in regional civil engineering Activity-Start was Q2 2019 when the construction of sections A, B and C of M30 expressway began.

Article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)