Last quarter of 2024 registers great rise in started constructions in Hungary

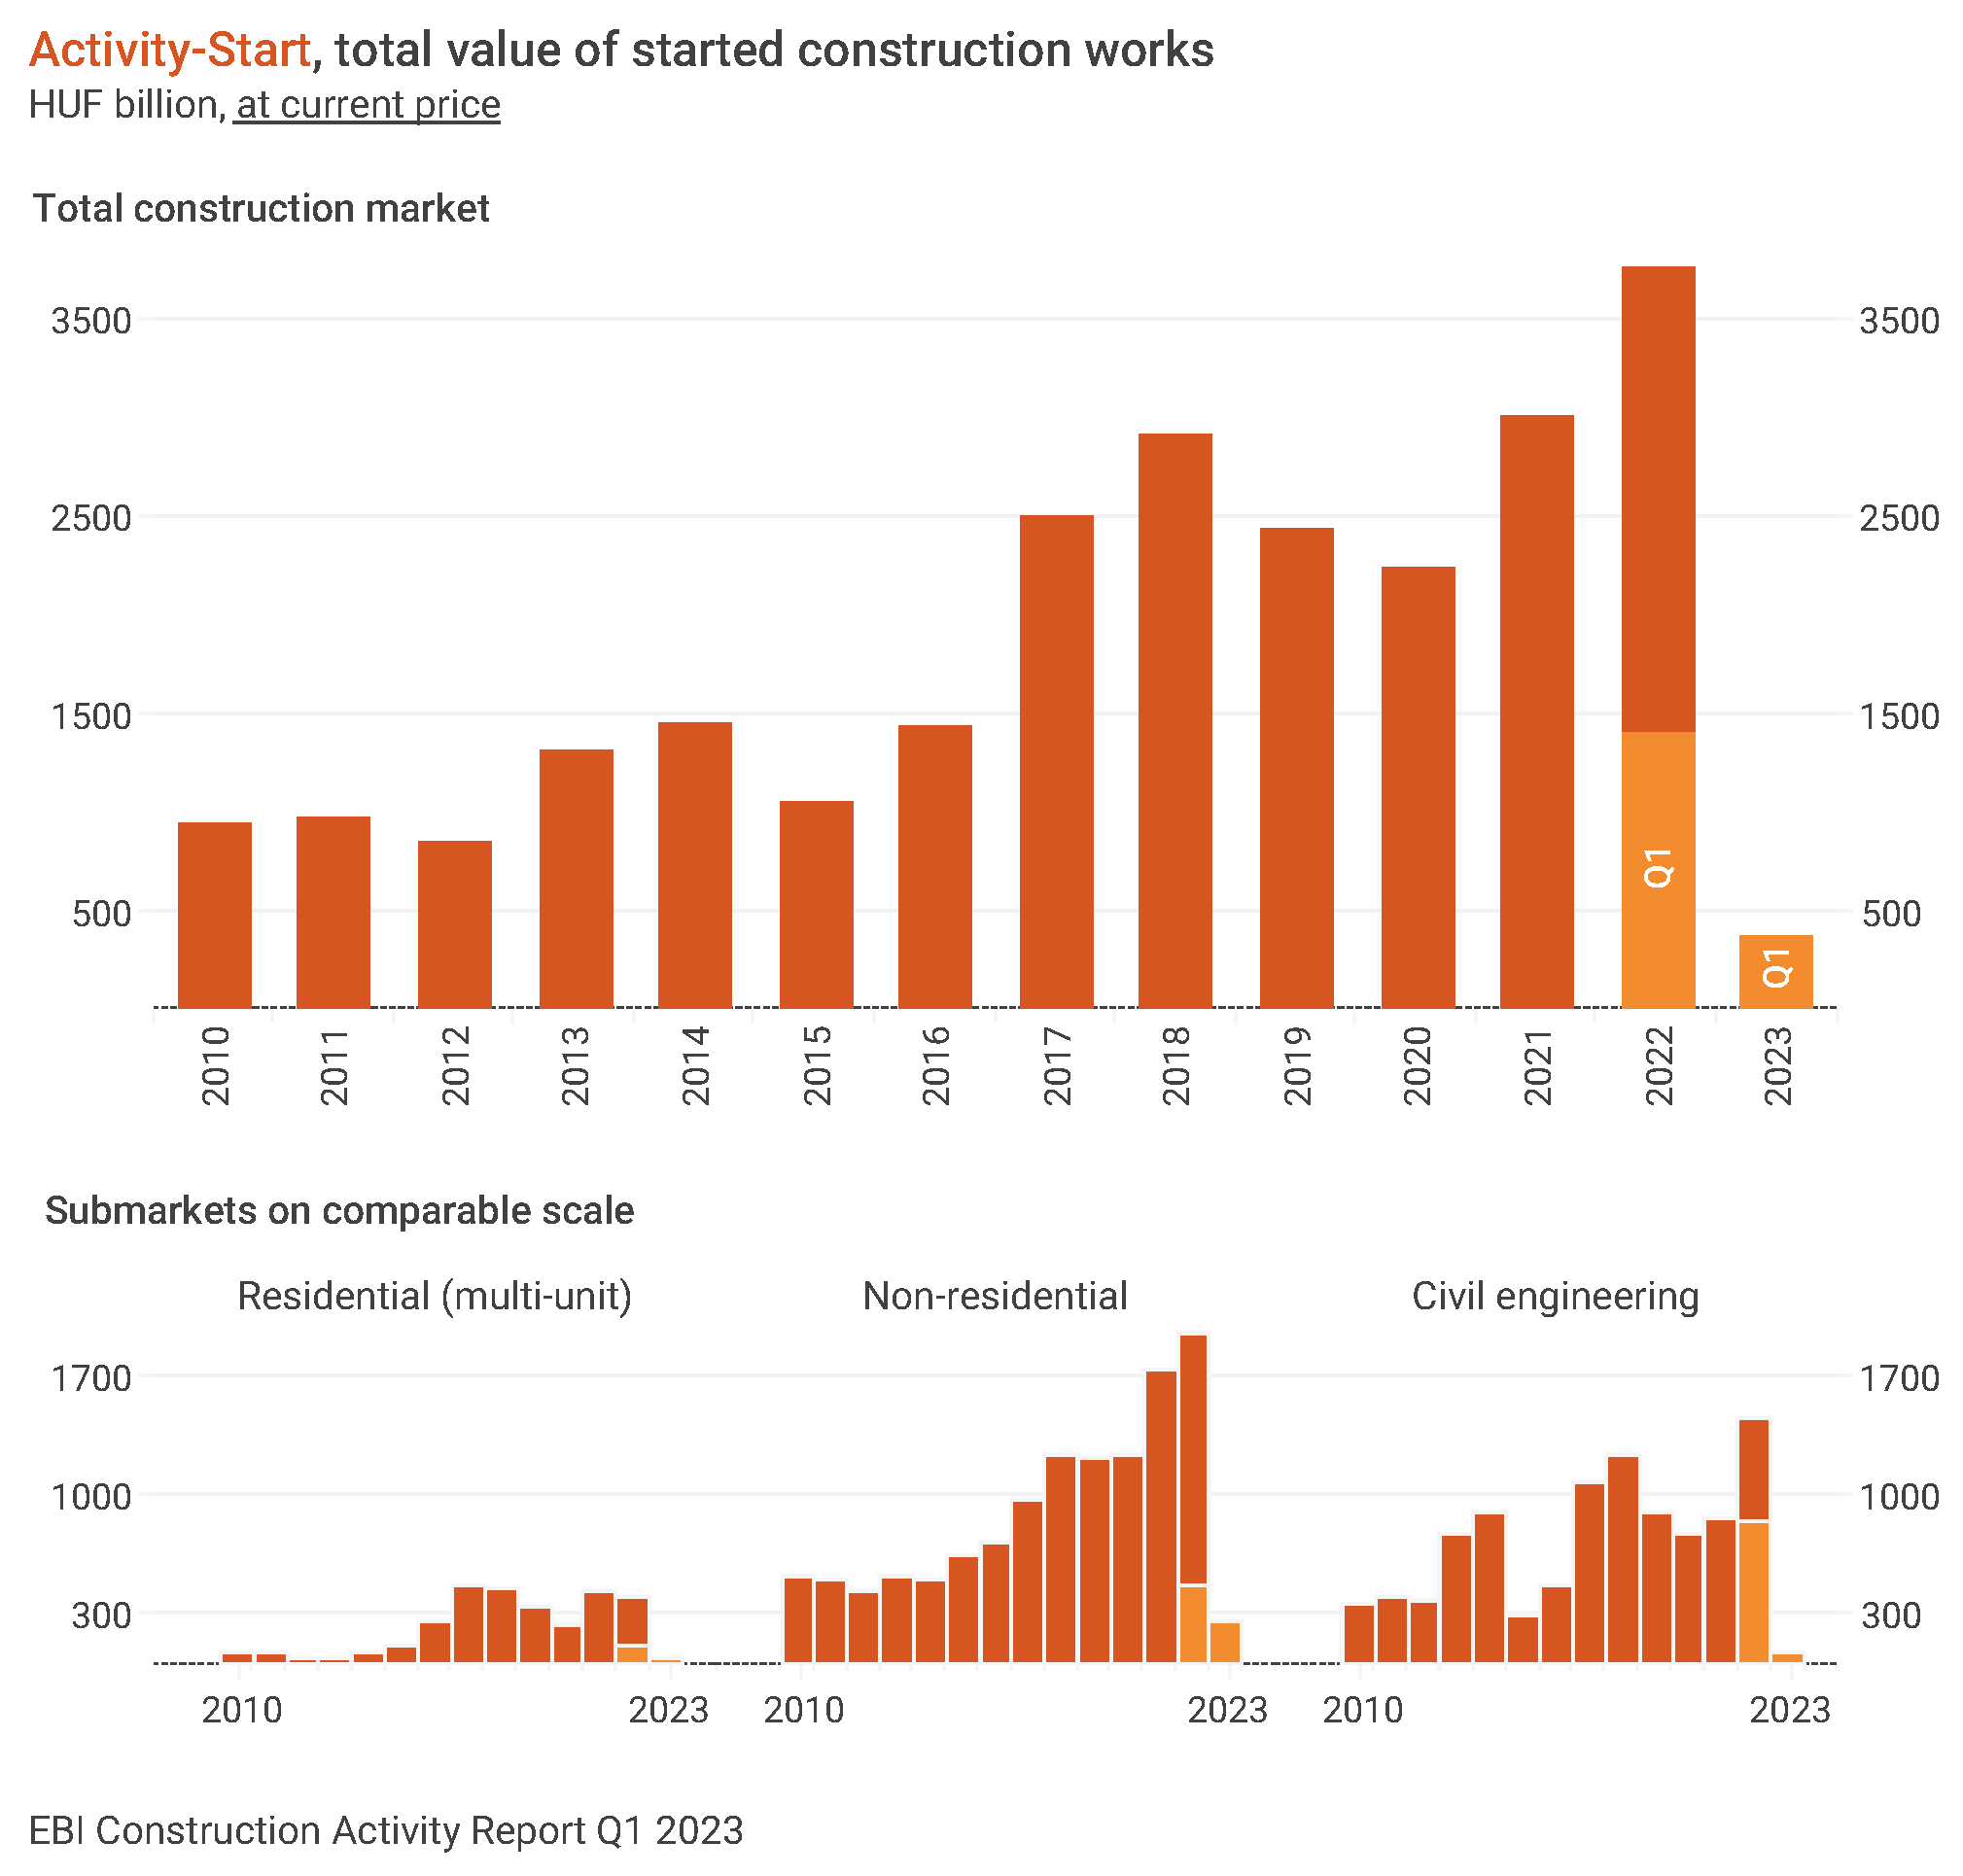
The Activity-Start of the latest EBI Construction Activity Report surpassed HUF 830 billion, a value considered to be exceptionally high. It should be added though, that these outstanding numbers were mostly thanks to the start of the construction works of the Mohács Danube Bridge project.

Despite the weaker Q2 and Q3, thanks to the good Q4, in the whole 2024 started construction works totalled about HUF 2800 billion, almost the same level as in 2023. Yet, it was a significant lag compared to the 2021-2022 figures, and at constant price it was still the lowest Activity-Start of recent years. Last time we saw a lower value of construction start than the 2024 level was in 2016.

Multi-unit residential projects boosting building construction

Building construction projects worth a total of around HUF 500 billion were launched between October and December last year. For the whole of 2024, the value of building projects entering construction phase was nearly HUF 2000 billion. Yet, last year’s Activity-Start fell short of the yearly figures for 2021-2023; the difference compared to 2023 was 5.9%, while compared to 2022 and 2021 it was 15% and 13%, respectively. At constant price, the last time a value lower than in 2024 was recorded was in 2015.

The reason for the better Building Construction Activity-Start in Q4 was clearly the multi-unit residential segment that posted a record growth over previous quarters. Activity-Start in the non-residential segment was low in Q4, though, almost the same as in Q3 (just over HUF 200 billion), still a very modest level compared to the quarterly figures of previous years. At constant price, Non-residential Activity-Start has not been as low in the past 11 years as in Q4 2024. Looking at the whole of 2024, construction works started here on slightly more than HUF 1,300 billion at current price, the lowest value since 2021. At constant price, the last time Non-residential Activity-Start was lower than last year was in 2014.

The biggest building construction projects that started in Q1 2024 included many multi-unit residential ones such as several phases of Kincsem by Bayer, the next phases of Park West and City Pearl. Also, the highest-value projects comprised the start of construction of several industrial and logistics buildings (Waberer’s logistics centre in Ecser, Phoenix Pharma logistics warehouse and office in Győr, the production facility of Félegyházi Bakery in Kiskunfélegyháza, Fémalk’s industrial plant in Dunavarsány and Phase 4 of Hankook tire factory in Rácalmás).

Civil engineering posted a good last quarter last year

In Q4 2024 civil engineering works worth more than HUF 330 billion started, approaching the exceptionally high value registered in Q1. Thus, overall, the level of Civil Engineering Activity-Start of EBI Construction Activity Report in 2024 exceeded HUF 800 billion, more than the 2023 figure and nearing the 2021 value. True, almost the entire Q4 Civil Engineering Activity-Start was due to the start of the Mohács Danube Bridge project.

Around half of the Activity-Start in Q4 2024 was related to road and railway projects with their level roughly being the same as in Q1. The situation was similar in case of non-road and non-railway construction works. The weak numbers in the middle of the year were followed by a larger number of construction starts in the last three months of the year. Yet, looking at the whole of 2024, projects worth less than HUF 400 billion entered construction in roads and railways, not even reaching the level recorded in 2023. At constant price, the last time Activity-Start was lower than last year was in 2015.

Most projects started in Central Hungary

Looking at the past 4 quarters, roughly half of the projects started in Central Hungary. Within, nearly 40% of the works started in Budapest. Eastern Hungary had a 23%, while Western Hungary had a 26% share in Activity-Start. Among the regions, thanks to the Mohács Danube Bridge project, the share of Southern Transdanubia spiked (14% after the previous 5%). The share of Northern Great Plain dropped; it was only 9% against the previous double-digit rates.

Multi-unit housing construction has picked up

In Q4 2024 multi-unit housing construction works practically exploded. The value of started works reached nearly HUF 300 billion, almost doubling the previous record of Activity-Start of EBI Construction Activity Report. Thanks to the outstanding last three months, 2024 was ultimately a record year with the value of started multi-unit construction works surpassing HUF 600 billion. It outnumbered the Activity-Start of 2023 by 66% and represented a growth of about 45% at current price over 2021 and 2022. At constant price, the value of multi-unit construction starts in 2024 was higher than in 2023 and 2022, roughly the same as in 2019 and 2021.

The acceleration in multi-unit housing constructions in Q4 2024 comes as no surprise. Developers may have responded to the pick-up in demand already noticeable last year, plus, they may have prepared for an even greater increase in demand this year – in line with market expectations. Subsidies in 2025 (maturing government bonds and interest payments, private pension fund savings that can only be used for housing purposes this year) may considerably spur the willingness to buy a home this year.

As for completions in the multi-unit segment, construction works of about HUF 400 billion were completed in 2024, exceeding the Activity-Completion indicator of EBI Construction Activity Report of the previous three years. Last year’s multi-unit residential completions were the second highest value registered after 2020.

Regionally, most multi-unit residential projects still started in Budapest, accounting for more than 70% of the value of construction starts in 2024, compared to the previous figure of under 60%. However, Eastern and Western Hungary posted a major decrease and had shares of 10% and 18%, respectively.

Weak H2 2024 in the value of started office construction projects

Activity-Start in office constructions fell sharply between July and December last year with works worth less than HUF 20 billion. Although H1 2024 managed to reach the figures of H1 2022 and H1 2023, overall, there was a large drop in 2024. The value of Activity-Start of EBI Construction Activity Report did not reach HUF 130 billion in 2024. This was a 24% decline compared to 2022, while a 68% and 66% lag behind the outstandingly successful years of 2023 and 2021. After 2015, even at current price, only in 2020 did office projects start in a lower value than last year. At constant price, the office market had not registered such a low Activity-Start as in 2024 in the past 11 years.

The start of MBH Bankholding HQ and the central office next to Rossmann warehouse was the two office construction projects with the biggest value last year. The decline in market-based office projects has not started now. Rather, in recent years, state orders have been able to enable growth in the segment. For instance, the fact that the overhaul of the former Ministry of Finance building in the Buda Castle, the historic reconstruction of the Hungarian National Bank HQ and Phases 1-3 of the reconstruction of the former Palace of Archduke Joseph all started at the same time in 2021 boosted Activity-Start that year. Or, in 2023, the start of renovation works on the Ministry of Agriculture building and on the Palace of Justice building, as well as the start of construction of the BudaPart and Zugló City Centre offices all contributed to high Activity-Start that year. A large part of these will also house state agencies and companies.

When it comes to office completions in 2024, the Activity-Completion indicator was nearing HUF 300 billion, the highest value ever measured in the market. For example, the Hungarian National Bank HQ and the reconstruction of the Ministry of Finance building both reached completion. 2025 may be another record-breaking year in terms of office completions as several office buildings in BudaPart and Zugló City Centre may also be completed.

Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)
Value of started projects in Hungary between January and September 2024 almost 17% down y-o-y

According to the Q3 2024 EBI Construction Activity Report Hungary, after Q2 brought a decline in the value of started construction projects, in Q3 a further decrease followed. Since 2016, the Activity-Start of less than HUF 360bln between July and September has been a new negative record, even at current price. These weak numbers were not even offset by the better Q1 and Activity-Start accounted for slightly more than HUF 1800bln. The value of projects entering construction between January and September 2024 was nearly 17% lower than in the same period of 2023.

Photo by Hajnalka Hurta

Shrinking Building Construction Activity-Start

Q3 saw a continued decline in Building Construction Activity-Start with only HUF 310bln worth of started works. Except for the pandemic year of 2020, only 2017 and earlier years saw lower quarterly numbers. Looking at the first 9 months of this year, the value of started construction works was slightly less than HUF 1360bln, 15%-22% lower than in the same period of 2021-2023. At constant price, the drop was even more considerable: since 2014 there has not been a lower Activity-Start in the first three quarters than this year.

Multi-unit housing constructions posted a slight decrease in Activity-Start in Q3, but non-residential projects registered a larger drop with only HUF 200bln worth of projects entering construction phase between July and September. In the first 9 months, the Activity-Start of non-residential constructions was around HUF 1000bln, 21%-27% lower at current price than in the same period of 2021-2023. At constant price, the last time the number for the first three quarters was lower than this year’s was in 2014.

The largest construction projects launched between July and September 2024 included Lidl’s logistics center in Kiskunfélegyháza, HelloParks Páty PT5 logistics hall, Pick’s production plant in Szeged, Intretech’s plant in Kapuvár, Rheinmetall’s hydrogen and e-mobility parts production plant in Szeged and IGPark’s logistics hall in Debrecen. The construction of the hotel in Kígyó street in Budapest also started. Out of the 10 biggest projects in the quarter, 5 were multi-unit residential buildings or dormitories.

Civil engineering Activity-Start hits rock bottom

There was a further decline in civil engineering after Q2, Activity-Start in Q3 was only less than HUF 50bln – a new negative record of the last 8 years. But in terms of Activity-Start in the first 9 months, the 2024 result is not much better either. The value of construction works started in the first three quarters at current price has not been lower than this year since 2016, while at constant price it was the negative peak of the last 10 years.

Compared to the same period in 2021 and 2023, Activity-Start between January and September this year was 22%-24% lower, while it was only a little more than a third of the exceptionally high 2022.

Within civil engineering, only a negligible railway construction project started in Q3, and the value of road construction projects was also very low. In the first three quarters, road and railway construction accounted for roughly 45% in Activity-Start, their value slightly exceeding HUF 200bln.

Due to the rather low civil engineering activity, hardly any civil engineering project could get into the list of biggest projects. Only the wastewater projects in Dejtár agglomeration and the Rétság agglomeration are worth mentioning.

Budapest leads still

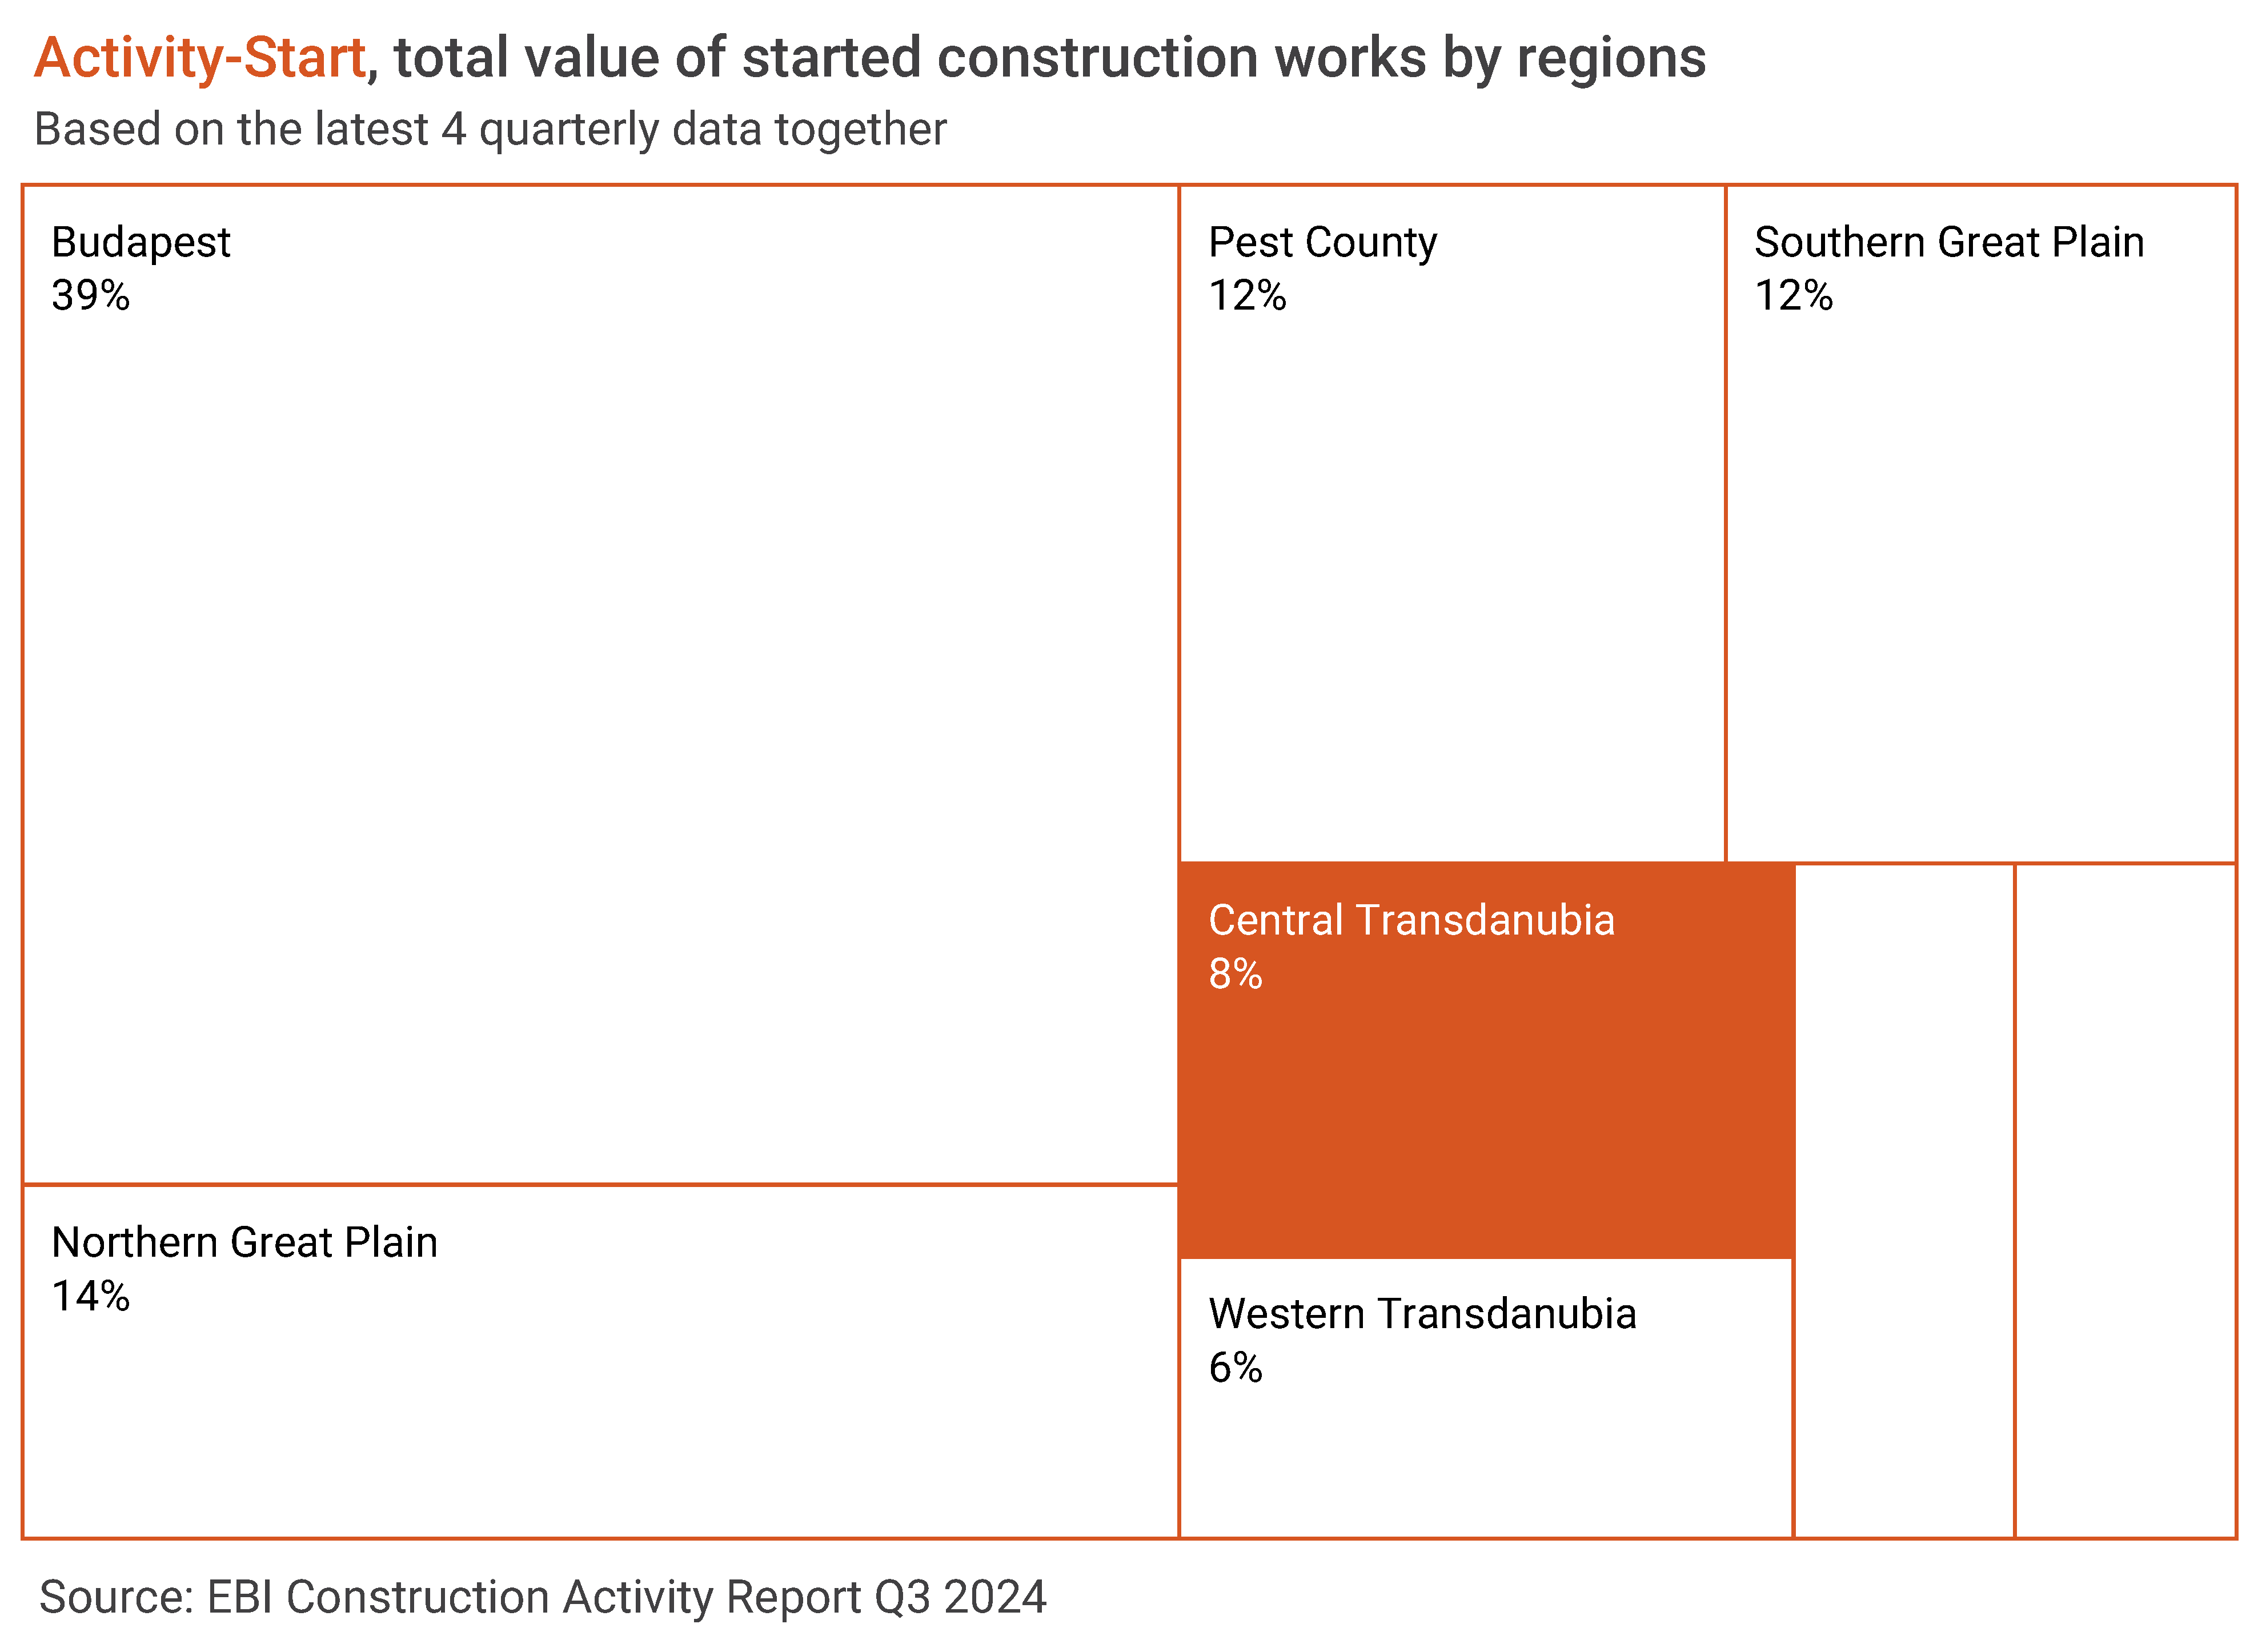
Looking at the last 4 quarters, 39% of all started construction works were in Budapest. The second largest Activity-Start was characterized by the Northern Great Plain (14%), followed by the Southern Great Plain and Pest County (12%). Northern Hungary and Southern Transdanubia recorded the lowest value of started construction works with their respective share of around 5%.

Multi-unit construction works are keeping up

Even though somewhat fewer multi-unit housing constructions started in Q3 than in Q2, Activity-Start significantly exceeded Q1. Construction works started in the segment on slightly more than HUF 100bln. Looking at the first 9 months of the year, there was an overall higher Activity-Start at current price than in the same period of 2019-2023. The value of projects entering construction was roughly the same as in the same period of 2022. At constant price, the Activity-Start for the first 9 months of this year outstripped the first three quarters of 2023; yet it was the second lowest since 2016.

This suggests that developers are still cautious with project starts even though this year’s demand for new homes increased compared to last year’s. Based on housing market trends, supply is expected to grow. A strengthening demand and rising prices may encourage more investors to start projects, and thus Activity-Start in multi-unit construction works may also increase in the future.

In Q3 the value of completed multi-unit housing buildings continued to drop, barely surpassing HUF 60bln. At the same time, in the first 9 months, approximately HUF 265bln worth of such buildings were completed, a slight rise over the same period last year. For the time being, a larger volume of homes is expected to reach completion in the last quarter, however, due to project delays, some may only be completed next year.

The biggest share of multi-unit residential constructions still started in Budapest. Based on the data of the last 4 quarters, the share of the capital city was around 60%. Eastern Hungary accounted for 14% of the Activity-Start, while Western Hungary for 24.5%, up from the previous quarters.

Central Transdanubia

Activity-Start in Central Transdanubia was roughly HUF 40bln in all three quarters this year. Thus, in the first 9 months, construction projects started at a total of HUF 123bln, a major drop compared to the same period of previous years. In the first 3 quarters of 2023, Activity-Start in the region was almost HUF 200bln, while in the first 3 quarters of 2022, it reached around HUF 300bln.

After the weaker Q1, Activity-Start for building constructions in Central Transdanubia in Q2-Q3 was roughly at last year’s levels. Thus, overall, the value of projects entering construction was around HUF 100bln in the first 9 months of this year, lower than in the corresponding period in 2023, and particularly lower than in the same period of 2021-2022.

The outstanding building construction Activity of 2021-2022 was boosted by the start of several big-league projects in 2021 (SK On’s battery factory in Iváncsa, Alba Aréna multifunctional hall in Székesfehérvár) and in 2022 (Kovács Katalin National Kayak-Canoe Sports Academy, the renovation of the church buildings in the castle quarter of Veszprém).

Projects entering construction phase between January and September 2024 in the region included the Huayou Cobalt-Bamo cathode factory in Ács and Phase 3 of Campus Lane Condo in Székesfehérvár.

In the first 9 months of 2024, hardly any civil engineering projects started in Central Transdanubia and the value of started works only reached a bit more than HUF 20bln. Among major civil engineering projects this year only Phase 1 of the dam between Mária-Valéria Bridge and Prímás island ramp can be mentioned. Last year bigger-value civil engineering projects started in the region in Q3 and Q4, for example, several water utility or wastewater projects, and the Biatorbágy-Szárliget railway line.

Original article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

Q2 registers historically low quarterly Activity-Start in Hungarian construction, but H1 is not so bad

As per the latest EBI Construction Activity Report Hungary, in the second quarter this year started construction works barely exceeded HUF 400 billion – the lowest quarterly Activity-Start even at current prices since 2016. But due to the exceptional Q1 value, H1 2024 overall did not show a massive decline (only -11%) over H1 2023. Compared to 2021, however, the drop was 18%, and against the exceptionally good H1 2022, the decline was a whopping 45%. And at constant prices, Activity-Start was the negative record of the past 9 years.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). For more details on how to obtain the full report, please contact us.

Lowest quarterly value of started building construction works since 2020

As per EBI Construction Activity Report Hungary, Q1 2024 saw a high Activity-Start but was followed by Q2 that recorded a decline in buildings as well. The value of started building construction works did not reach HUF 360 billion – the lowest quarterly figure since 2020. Overall, the subsector was characterized by a weaker Activity-Start even in the first half of the year: compared to H1 2023, the value of started construction works dropped by 11.8%, while over the same period of 2022 and 2021, at current prices, the decline was almost 30% and 21.5%, respectively. At constant prices, only H1 2014 was weaker than H1 2024.

Most of the decline occurred owing to the more moderate non-residential project starts. The decrease in multi-unit residential buildings was much smaller and the value of started construction works was roughly at the level of Q1. In non-residential buildings, Activity-Start was slightly higher than HUF 260 billion between April and June this year (a drop of almost 43% over Q1) but was also much lower than in the same period of the previous 3 years. Looking at individual quarters between 2021 and 2023, this year’s Q2 was the second lowest at current prices, and at constant prices, it was the lowest value since 2013. Due to the weaker Q2, Activity-Start in H1 2024 was also lower than in the same period of the previous 3 years at current prices. At constant prices, it was only H1 2014 that saw a lower value.

Biggest-league building construction projects launched in Q2 this year comprised the construction of MBH Bank HQ in Budapest, Phase I of BYD electric car factory in Szeged, and Huayou Cobalt-Bamo cathode factory in Ács. The construction of Moxy Budapest Downtown (hotel) and that of several multi-unit residential buildings also began.

The value of civil engineering project starts hit rock bottom in Q2

The stellar numbers in Q1 were followed by a massive decline in Civil Engineering Activity-Start of EBI Construction Activity Report Hungary between April and June this year. Q2 brought minimal civil engineering project starts, and the value of started works did not reach HUF 70 billion – the lowest quarterly value since 2016. However, comparing the first half of the year with previous years, 2024 is not exceptionally bad. The value of Activity-Start was 10.5% and 9% less than in the same period of 2023 and 2021, and it even exceeded that of 2020. There was a major drop only compared to the outstanding figures between January and June 2022. Within civil engineering, in H1 2024 road and railway construction works accounted for around 45% of Activity-Start and their value did not go up to HUF 200 billion.

It is very telling about the rock-bottom level of Civil Engineering Activity-Start that in the period between April and June this year no civil engineering project could make it to the top 10 biggest started construction projects.

Most construction works continued to start in the capital city

Looking at the past 4 quarters, the largest share of construction works again started in Budapest. The capital city’s share in the nationwide Activity-Start even surpassed 40%. Northern Great Plain had the second largest share, but its 13% was a great drop compared to the 20%-30% of the previous quarters. Pest County came third with 12%, while the smallest share of projects started in Southern Transdanubia with only 5% of launched construction projects in the last 4 quarters.

Practically no change in the value of started multi-unit residential projects

The latest EBI Construction Activity Report Hungary has found that after Q1 2024, in Q2 the value of multi-unit residential construction works started during 3 months was almost unchanged with a total of slightly more than HUF 90 billion. In the first half of this year, Activity-Start in the segment was less than HUF 200 billion, roughly corresponding to the level of the same period in 2021. At constant prices, although in H1 2024 the Activity-Start of multi-unit residential construction exceeded the one in H1 2023, it fell short of the one registered in the January-June period of previous years. It was only in H1 2015 when it was lower. Nevertheless, compared to other construction segments, multi-unit performed much better in Q2: the 10 largest-scale projects entering construction phase included several multi-unit ones, even with just over 100 flats.

The value of completed multi-unit residential construction works shrank in Q2 against Q1, but it stayed high, outstripping HUF 200 billion in H1 2024, making it the strongest first half year recently. Activity-Completion in H1 2024 was almost 42% higher than in the same period of 2023 and even surpassed the record H1 2020 by more than 22%. Further on, Activity-Completion may continue to be high, and, based on expected completion dates, this year may break a new record.

During the last 4 quarters, the largest share of multi-unit residential construction works continued to start in Budapest whose share also grew compared to the previous quarter with two-thirds of Activity-Start. Eastern Hungary’s share was 15.5%, while in Western Hungary 16.6% of such works began.

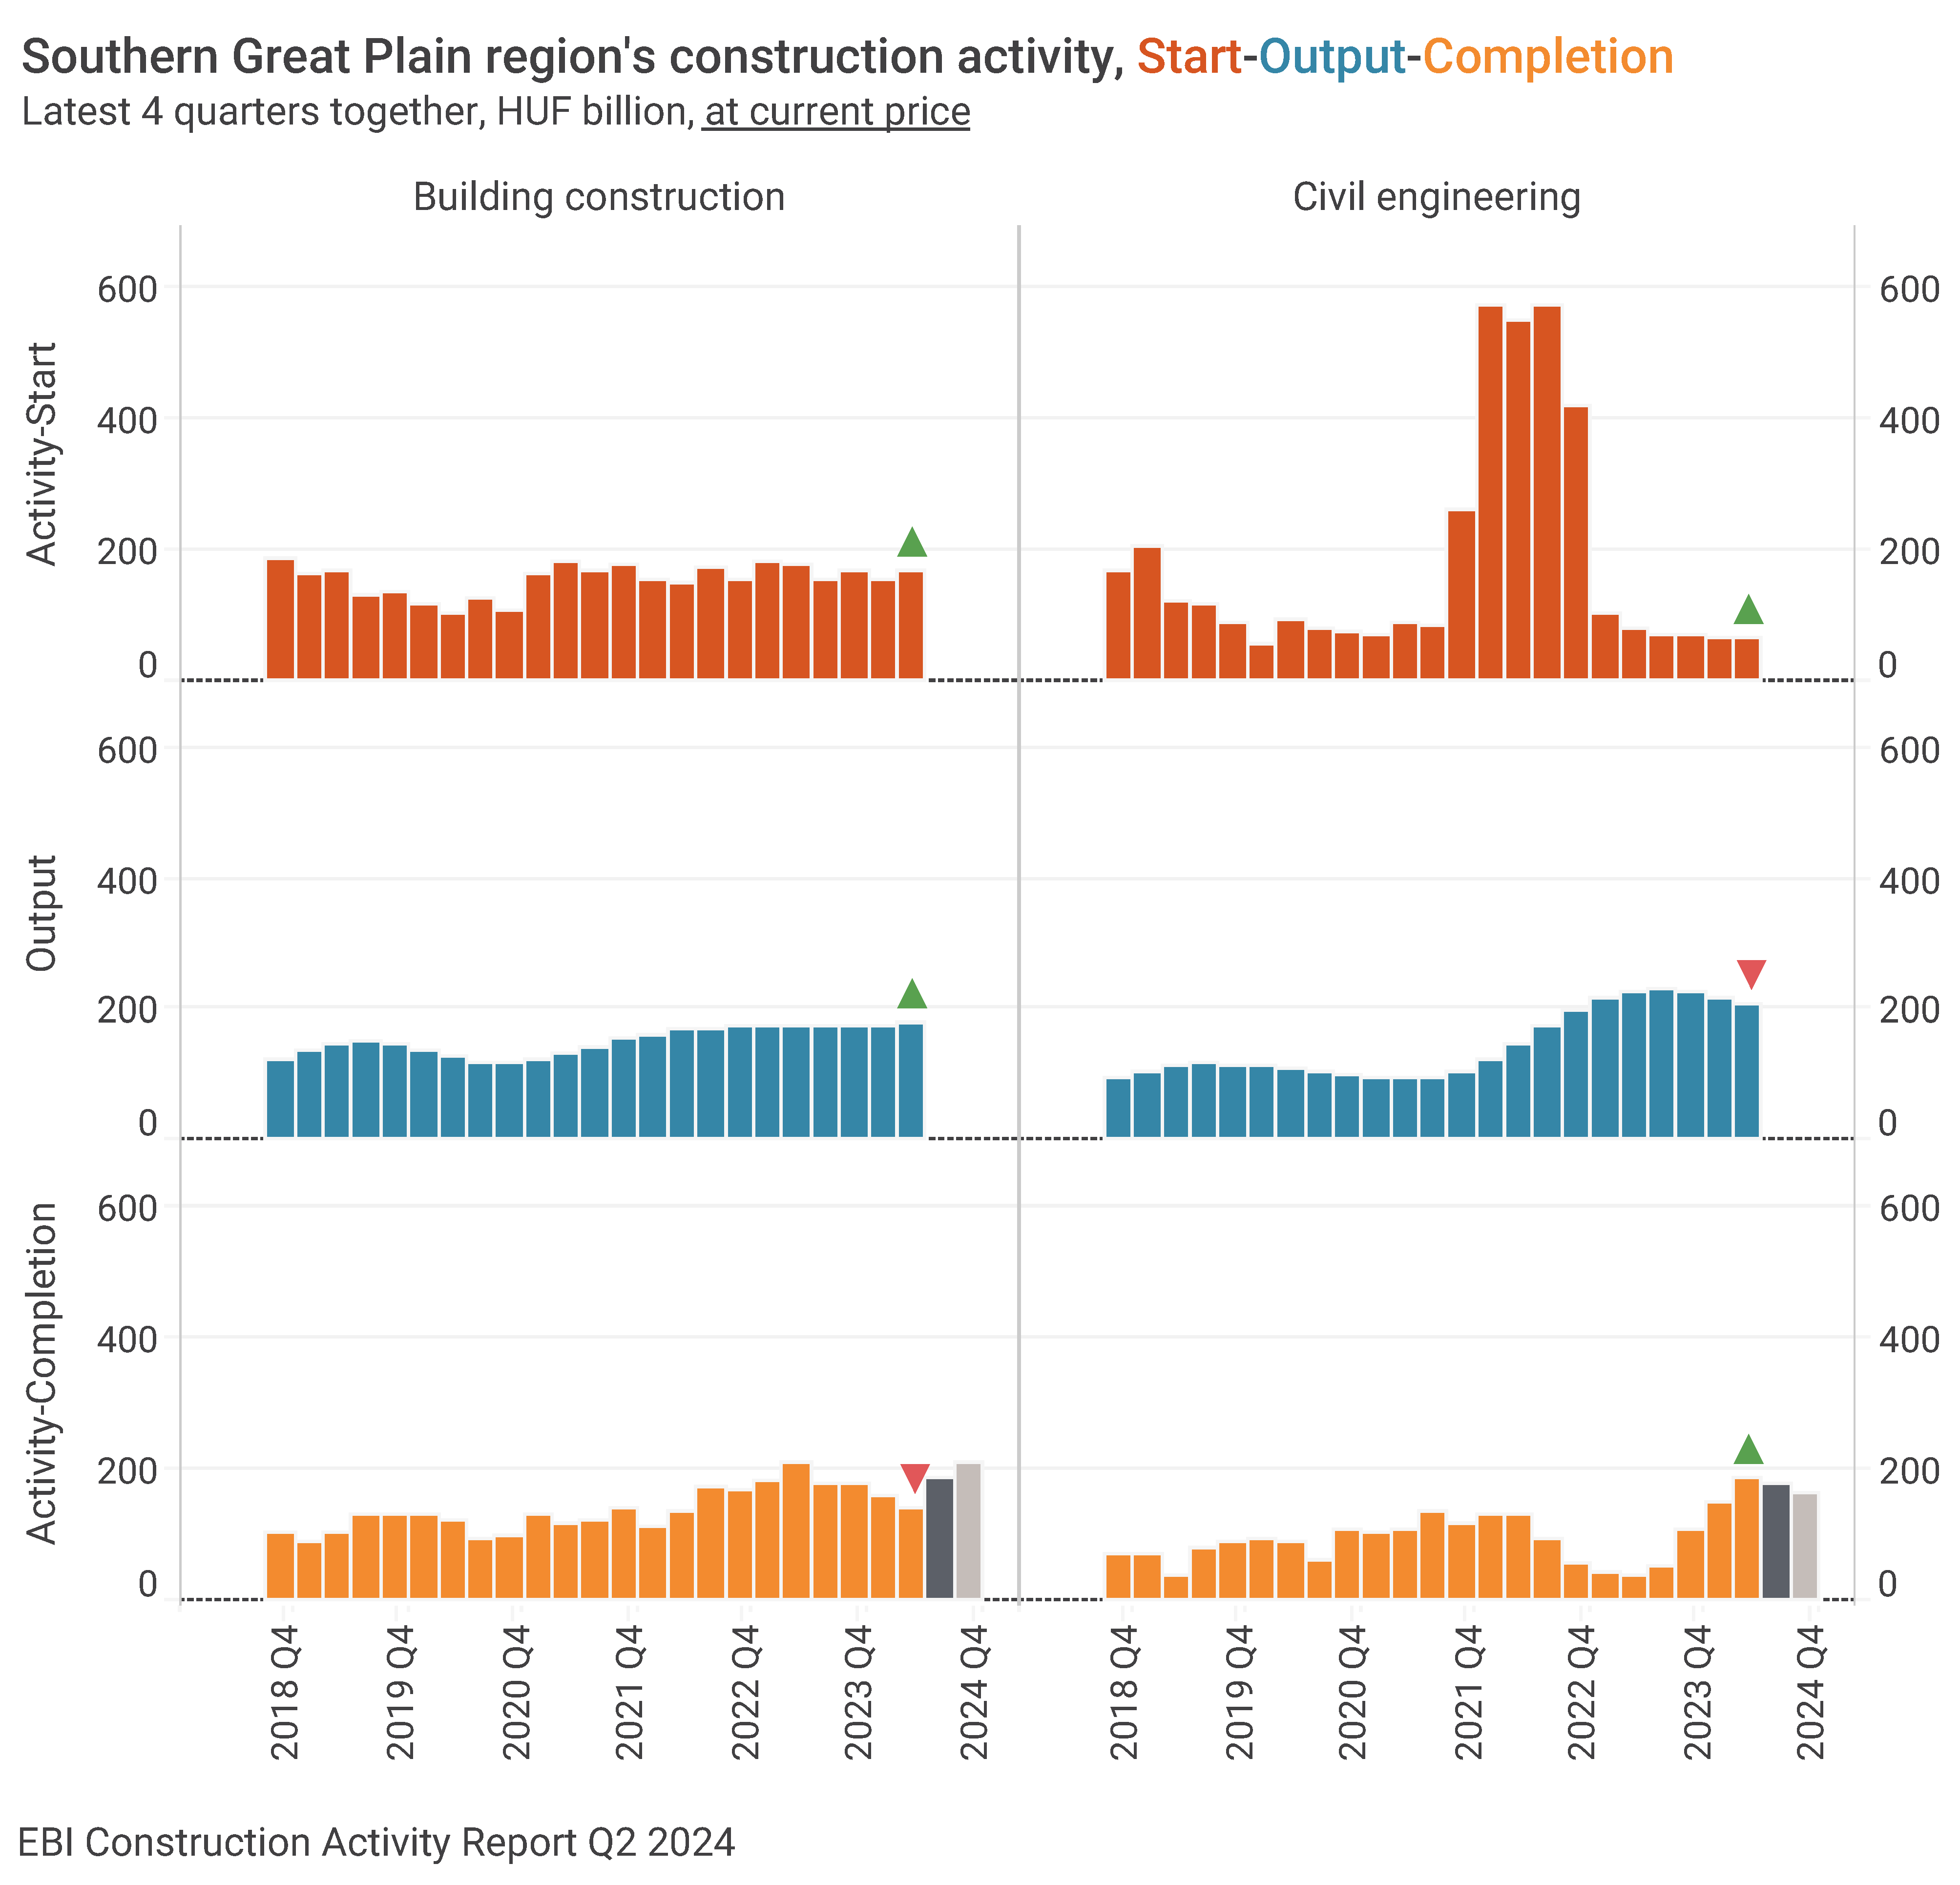
Southern Great Plain saw some growth in half-yearly Activity-Start

Southern Great Plain also saw some expansion in construction during the first half of this year, even though Q2 brought a decrease after Q1 – as per the latest EBI Construction Activity Report Hungary. Activity-Start here amounted to HUF 126 billion between January and June 2024. Building construction projects contributed most to the Activity-Start of this region: the value of started construction works in H1 2024 was HUF 110 billion – the level of H1 2023. But it was also true for regional building constructions that the higher Q1 values pushed up the half-yearly ones and Q2 brought a more moderate Activity-Start. Within buildings, multi-unit residential buildings represented a minimal level in the region, as in previous years, only 6% of such projects nationwide started here in the first half of the year.

Among the biggest non-residential projects entering construction phase in H1 2024 in the region were Benepack’s packaging materials factory in Makó, Mercedes-Benz battery assembly plant in Kecskemét, and Phase I of BYD electric car factory in Szeged. These projects were also considered large in terms of works started in recent years: in value, between 2021 and 2024 they ranked second, third and fifth, respectively.

Hardly any civil engineering project began in Southern Great Plain this year. Activity-Start in civil engineering in H1 2024 was less than HUF 16 billion – one of the lowest half-yearly results in recent years. Civil engineering works in the region reached an outstanding value in late 2021 and in early 2022 that saw the construction start of the Békéscsaba-Lőkösháza railway line, the Soroksár-Kelebia section of the Budapest-Belgrade railway line, and the Kecskemét-Szentkirály section of M44 expressway whose total value was hundreds of billions of Hungarian Forints and whose construction is still ongoing.

Article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)
Hungarian construction industry kicked off well in 2024

The value of construction works launched in three months rose in Q1 2024, Activity-Start hasn’t been so high in the last six quarters. EBI Construction Activity Report Hungary Q1 2024 measured the total value of started construction works at HUF 807bln. Looking at the period between 2018 and 2023, there were very only five quarters when Activity-Start surpassed this number. At constant prices, Q1 2024 was also considered good when looking at the period since June 2022. Nevertheless, when compared to the period between 2018 and H1 2022, it fell into the lower range.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Eltinga, Buildecon (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). For more details on how to obtain the full report, please contact us.

Building construction failed to improve in Q1 2024

Building construction could not regain senses in early 2024: Activity-Start was at the level of the last quarter of 2023. The value of started construction works was slightly more than HUF 400bln, almost the same as between October and December last year, but 17%-26% lower than in the first quarters of previous years. At constant prices there was a decline in the value of started building projects: last time Activity-Start was lower was in Q4 2015.

The Activity-Start indicator of non-residential buildings slightly grew in the first three months of 2024 compared to Q4 2023, thus exceeding HUF 350bln. Yet, examining individual quarters between 2021 and 2023, Q1 2024 was the second lowest. At constant price, the last time Activity-Start was lower than in Q1 2024 was in 2015. In case of housing construction, 2024 started better than 2023, but the value of started construction works continued to drop after Q4 2023.

Biggest building projects launched in the first three months this year mainly included logistics and industrial buildings, like the construction of Mercedes-Benz battery integrating plant (Kecskemét), Weerts Ebes logistics hall (Ebes), Benepack packaging materials factory (Makó), Phase I of Evoring electric car parts factory (Jászfényszaru), building C of VGP Park logistics center (Győr), and the storage hall and HQ of Rossmann (Üllő). Large office projects such as Zugló-Városközpont Office7 and several multi-unit residential projects also started, as well as the construction of Hilton Garden Inn Hotel (mixed-use) and the development of Hungaroring Paddock.

Civil engineering getting back to life

After several weak quarters, civil engineering seems to have improved and Activity-Start in Q1 2024 was nearly HUF 400bln, an increase of roughly 70% against Q1 2023. The improvement was visible in non-road and non-railway constructions and in road and railway ones alike. The former saw a 180% growth over the first quarter of last year, but Activity-Start was more than 50% higher than in the last quarter (which was also stronger). The value of non-road and non-railway projects at current price was last higher in Q1 2017 than in Q1 2024, but even at constant price, it has been the fourth highest Activity-Start since 2020.

In road and railway constructions, the recovery was mainly due to the Ferencváros-Kelenföld railway line 1 project, considered to be the highest-value work started in Q1 2024 in the entire construction sector. The Southern Industrial Park in Nyíregyháza and the flood protection facility in Esztergom were also among the biggest started civil engineering projects.

Budapest took the lead again

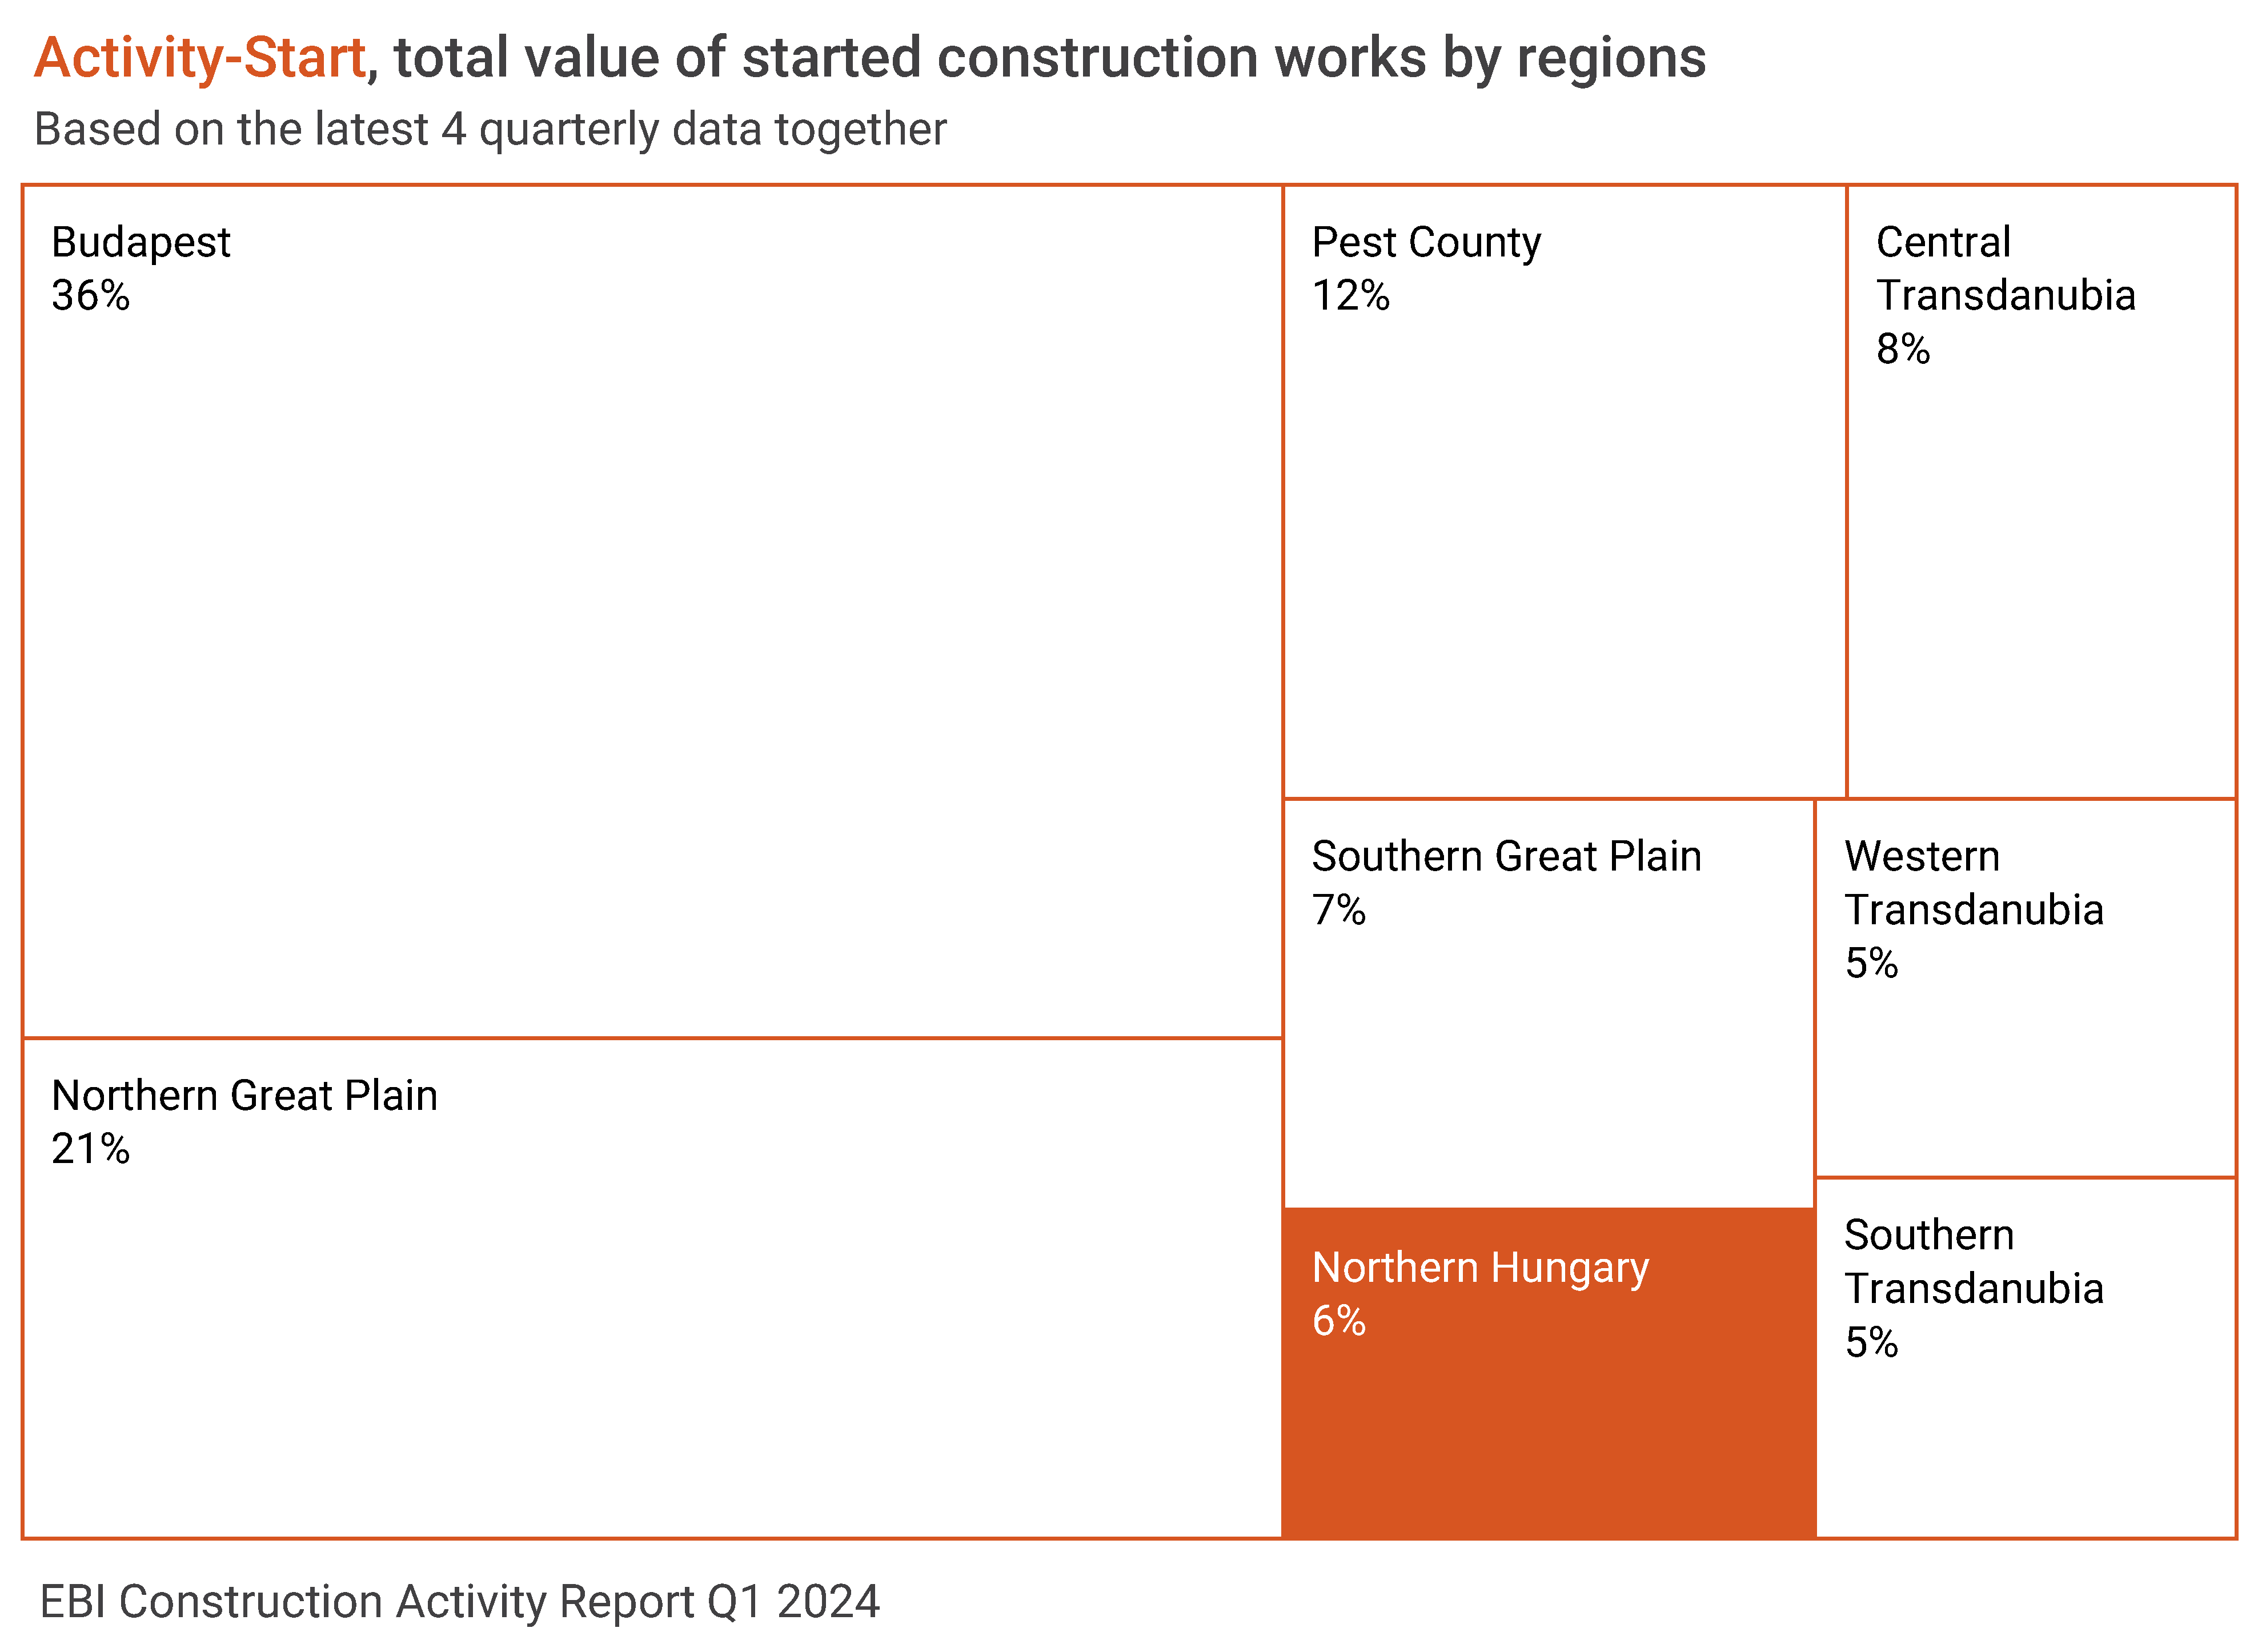
Looking at the construction works started in the last four quarters, the highest value ones were in Budapest whose share in total Activity-Start was 36% (the 20%-30% in the last quarters). Northern Great Plain, the leader in previous periods, slipped back to the second place (21% of works started here). Southern Transdanubia had the lowest Activity-Start (its share barely exceeded 5%), Western Transdanubia had a share of 5%, while Northern Hungary had 6%.

Multi-unit residential building still stumbling

Although this year started better than the last one in multi-unit residential construction, the value of such started projects dropped further and was lower than in the last two quarters of 2023. Starting from Q2 2016, the segment registered the fourth lowest Activity-Start in Q1 2024 at current price. Looking at constant price, the value of works started in early 2024 has been the third lowest since 2016.

Yet the market outlook improved compared to the previous year. Mortgage rates sank greatly by end 2023 and continued to do so in 2024, while the economic outlook also became better. The rosier environment has lured buyers back to the residential market with the revival already noticeable in the first quarter of this year, both in the secondary and primary markets. Good news: the reduced VAT rate for new homes has been extended, so instead of end 2024, building permits can be obtained by end 2026 and homes can be sold at 5% VAT until 2030.

Many multi-unit residential projects were completed in the first three months of this year with their value exceeding HUF 120bln, the highest quarterly Activity-Completion since 2021. Many units are expected to be completed this year, too, however, in the long run, the value of completions is set to decrease due to previously shrinking construction works.

Looking at the past four quarters, Budapest accounted for 63% of multi-unit residential projects entering construction phase, and slightly more than 64% of the value of such projects was concentrated in Central Hungary. Eastern Hungary accounted for 14.8% of the Activity-Start, while Western Transdanubia’s share was 20.9%.

Northern Hungary in focus

Although the year started well in the construction industry nationally, it is not true to Northern Hungary where the total value of started construction works did not reach HUF 22bln. It was the lowest quarterly amount in 2018-2023.

In Northern Hungary, both building construction and civil engineering shrank in the first quarter of this year. Building Construction Activity-Start was one of the lowest in the quarters of recent years with the drop clearly attributed to non-residential buildings. Although the value of the started multi-unit residential constructions grew at the beginning of 2024, the region still has a very low willingness to build such buildings (its share in the national multi-unit residential Activity-Start was less than 3% in the last 4 quarters). Low activity in multi-unit residential works is well illustrated by the fact that, despite the improvement, no project made it into the largest construction projects in the region in Q1 2024.

Among non-residential buildings, the biggest regional projects launched between January and March 2024 include Phase II of Horváth Rudolf logistics centre in Hatvan. In recent years the largest ones comprised the logistics hall of Robert Bosch Power Tool MC301 in Miskolc (starting in 2023), the manufacturing plant of GKN Automotive in Felsőzsolca (starting in 2022), Chervon manufacturing plant and the reconstruction of Diósgyőr Castle in Miskolc (starting in 2021).

In early 2024 Civil engineering Activity-Start in Northern Hungary continued to drop. Looking at the period of 2018-2023, the total value of construction works started in Q1 2024 was the third lowest: Activity-Start did not reach HUF 4bln. In Q1 civil engineering projects were not even among the largest started ones. The value of civil engineering projects started in the region was higher in Q2 2023, in Q2 2022 and in Q3 2021 when such projects entered construction phase as the Szentdomonkos-Borsodnádasd section of main road 25, the Sajószentpéter-Berente bypass 260, and the Gesztely-Szerencs section of main road 37. The peak so far in regional civil engineering Activity-Start was Q2 2019 when the construction of sections A, B and C of M30 expressway began.

Article: Tünde Tancsics (ELTINGA); English version: Eszter Falucskai (Buildecon)

Record value of construction works started in Romania in 2023

Written by Dr. Sebastian Sipos-Gug – Ebuild srl

Activity-Start, that is, the total value of started construction works, greatly increased (+64%) in 2023 across Romania compared to the previous year. It reached the highest level seen in the past decade, both as gross value and growth rate – according to the EBI Construction Activity Report. Even more impressive is the serendipity that as Activity-Start of building construction began to decline, civil engineering sprang up to cover the difference and more.

What is EBI Construction Activity Report? There was no construction start indicator in Romania, so we have created an estimation for it. It helps you understand what could happen on the market in the coming months. The indicators are based on project information from iBuild project database and are published monthly in the EBI data visualization (for all the 18 segments of the construction market). On top of this the EBI Construction Activity Report Romania is published quarterly with data and explanations. This research is a fruit of the cooperation among Eltinga, Buildecon and iBuild. And this is where the name EBI comes from.

Civil engineering in the spotlight

Residential multi-unit buildings seem to have peaked in 2021 in terms of the Activity-Start indicator. With construction costs rising in 2019, followed by high inflation and interest rates, it seems developers were less optimistic about the market’s short-term outlook and consequently, they started fewer projects.

When it comes to non-residential construction, 2023 saw a slight downturn after a very good performance in the previous year. The main factor was Bucharest where the current issues regarding urban planning, compounded with wavering demand, slowed down the development of new buildings across all non-residential segments, but mainly in the office sector.

With the spending deadline for funding from the EU 2013-2020 programs at the end of 2023, a surge in activity in civil engineering was to be expected, and this also explains why Q4 was milder than previous quarters in terms of the Activity-Start. The projects that had a reasonable chance to reach an advanced stage or to be phased into the new programs were prioritized and started in previous quarters.

Of all the projects that started construction in 2023, one stands out: the 37.4km section (Cornetu – Tigveni) of the A1 motorway will be one of the most complex and expensive road segments build so far in Romania since it crosses the Carpathian Mountains and will require 12km of bridges, tunnels and viaducts. It will also have the longest motorway tunnel built so far in the country (1.7km), nearly five times larger than the current record holder.

Several renewable energy projects were also started in Q4 2023: a 102MW wind energy park in Braila County and a 60MW solar plant in Alba County, signaling a renewed interest in green sources of electricity after the recent volatility in the prices of fossil fuels.

The third spot on the list of the largest projects that began in the last quarter of 2023 is taken by the 12,000-seat Sports Arena in Targoviste. The local football team there (FC Chindia – named after a tower built in the city by Vlad the Impaler) had to play its games on other cities’ stadiums in the four years it was in Romania’s First League as its local arena was considered inadequate.

Less glamorous, but equally important, work was also started in Q4 2023 on the water and sewer networks in Dambovita, Iasi and Brasov counties, part of the ongoing efforts at national level to improve the existing infrastructure and provide increased access to public utilities.

When it comes to building construction, all top projects started in the last quarter of 2023 were residential parks, three of which were in Bucharest (Theodor Pallady residential area, Nusco City Phase 2 and Cortina Elysium, totaling more than 1600 flats) and two more in Sibiu County (Magnolia Residence Phase 2 and a residential complex in Selimbar, adding nearly 1000 more flats).

Bucharest loses the first place in Activity-Start

2023 was an unusually even year regarding the regional distribution of the Activity-Start indicator. Previously, Bucharest-Ilfov took the largest piece of the pie and accounted for around one quarter of the value of construction works started in each year. In 2023, however, it lost its lead because other regions saw major increases in Activity-Start, while it and the Center underperformed compared to the previous couple of years and fell behind. The slowdown in Bucharest was visible across the board with drops in new projects, both in civil engineering and buildings. Infrastructure starts had previously peaked in 2022, and the focus switched to completion, while urban planning issues limit new developments for all segments.

The North East region had a boost moving from the third least active right to the top of the podium in terms of Activity-Start. Likewise, West shot up to the top half from the very last position that it held for four consecutive years.

North West region: steady as it goes

While other regions, as mentioned previously, saw major upward and downward changes in their share of the national started construction works, North West maintained the second place that it usually holds. Behind this veneer of stability, however, lies an uneven evolution of different construction types, the EBI Construction Activity Report suggests. Activity-Start indicator (deep orange on the chart) of the building construction submarket began strong, growing fast in Q1 and Q2, and then it plateaued, while civil engineering had a very different path, having a boom in activity in Q3.

Much of the growth can be attributed to the Cluj Napoca – Episcopia railway electrification (166 km), that in itself accounted for almost 1/3 of the value of all started construction works in North West in 2023. The fastest passenger train on this railway averaged 60km/h, with added delays at the Hungarian border and in Cluj caused by switching locomotives from electric to diesel and vice versa. The new electric line will remove this impediment and allow speeds up to 160km/h for passenger trains and the doubling of the lines will facilitate cargo transit as well.

Other major construction works started in 2023 in the North West include several sections of the much-delayed A3 motorway as well as airport terminals in Cluj, Satu Mare, Bihor and Maramures counties.
The region attracted several manufacturing investments with the largest project in the building submarket being the Nokian Tyers factory that started construction in Q2 2023 in Oradea.

Healthcare and education buildings are a rising concern due to the aging stock and limited access to services. Thus, extensions of the emergency clinics in Oradea (5.500sqm) and Bistrita (9.750 sqm) also started in 2023. In the same year, work began on a new private school in Oradea (29 classrooms) and on renovating a university building in Cluj County (10.000 sqm).

Cluj Napoca gained notoriety for its tight residential market. Limited deliveries and high demand have pushed the prices here higher every year, and it’s now the most expensive city in the country for home buyers. Supply is slowly expanding with phases of larger projects like Elite City (279 flats) and The Nest (102 flats) starting construction in 2023. Several multi-unit projects were also completed here in 2023, including Liberty Residential (268 flats) and Seasons by Studium Green (150 flats).

Completions (light orange) in the North West were on an upward trend for the past couple of years with building construction overshadowing civil engineering. This is poised to change starting with 2024 as the expected completion of infrastructure projects started by 2023 could even out the field. However, road and railroad projects in Romania have had a long history of delays, cancelled contracts and legal woes, thus, some caution is in order when looking forward.

During 2023 nearly 30km of motorway on A3 were completed on two sections. However, one of them (Nusfalau – Suplacul de Baracu) is quite isolated, so its usage will be limited until it’s connected to the remainder of the network, in 2025 at earliest.

With good Activity-Start and completions, Output (blue) also had a favorable evolution in 2023 for both buildings and civil engineering. Enforcing the idea of steadiness of the North West, Output showed steady growth in each quarter of the last couple of years, at least at current prices.

The major challenges for the North West region in the upcoming years will be to find new avenues of growth, especially in the building segment, and to secure funding and manage ongoing works for infrastructure construction. To quote Lewis Carroll “[…] here we must run as fast as we can, just to stay in place. And if you wish to go anywhere you must run twice as fast as that.”

2023: a weak year-end in Hungarian Construction Activity-Start

Hungary’s construction sector failed to improve in the last quarter of last year; the total value of started construction works shrank against previous quarters. Overall, 2023 registered low numbers and the Activity-Start indicator of EBI Construction Activity Report did not reach HUF 2,500 billion. This means that the total value of projects entering construction phase dropped by a respective 19% and 34% compared to 2021 and 2022, and Activity-Start in 2023 was roughly the same as in 2019. But if we look at the rate of decrease at constant price, it is even more significant: 43%-44% over 2021-2022. The last time the value of Activity-Start at constant price was lower than last year was in 2015, but even 2013-2014 exceeded last year’s.

Building construction works declined in Q4 2023

Even at current prices, the subsector has not produced such a low quarterly Activity-Start as in October-December 2023. Thus, the lower numbers of the first 9 months did not improve, and for the whole year, building construction works started at less than HUF 1,750 billion: 19% down from 2021 and 23% down from 2022. At constant price, the Activity-Start indicator for 2023 was 44% and 34% lower than in the previous two years. Only 2015 witnessed a lower Activity-Start than 2023.

Within building constructions, Activity-Start decreased in multi-unit residential buildings and in non-residential ones, too. In the latter, Q4 lagged dramatically behind the quarterly numbers of previous years. Last time the value of non-residential buildings entering construction phase in a quarter at current price was lower than that was in 2016. For the whole year, the Activity-Start indicator of non-residential buildings sank by 17% and 22.5%, respectively, over 2021 and 2022. Filtering out the change in prices, the lag is even greater: the level of Activity-Start at constant price in 2023 was 42% and 33% lower than in the previous two years. It was only in 2015 when lower numbers were registered.

The biggest building construction projects launched in Q4 2023 were several logistic facilities and warehouses (HelloParks Páty PT3 logistics hall; Phases 1 and 2 of LG Magna manufacturing plant in Miskolc; ZF Chassis Modules Hungary vehicle assembly plant in Kecskemét; ZF Chassis Modules Hungary manufacturing plant and warehouse in Debrecen). In addition, the project of the Hódmezővásárhely Military Secondary School and Dormitory, the renovation works of the Chemistry building of the Faculty of Science of Debrecen University, as well as Phase 1 of the renovation works of buildings B1, B2 and C of the University of Veterinary Science in Budapest started.

Civil engineering stagnated at a low level

Although there was no further drop in civil engineering, its Activity-Start was very low in Q4 2023 with about the same value of started constructions as in Q3. Thus, Civil Engineering Activity-Start in 2023 massively dropped against 2022 (a year considered an outlier), but the value of the started works did not reach the 2021 level either; and it turned out to be somewhat lower than in 2020. In 2023, there was a 17% drop in the subsector against 2021, and a 50% shrinkage over 2022. The constant-price decrease was even greater: almost 60% over 2022 and more than 40% over 2021. Between 2013 and 2023, at constant price, only the Activity-Start of 2015 was lower than that of 2023.

Hardly any road and railway construction works started in Q4 2023, while much more other civil engineering works entered construction phase. In 2023, road construction works started at a higher value than in 2020-2022, but railway construction works fell greatly last year: here Activity-Start at current price was only lower in 2015. Thus, overall, during the year, the Activity-Start of road and railway constructions was around 19% lower than in 2021, while it was almost 60% less than in 2022 (a year considered outstanding).

The largest civil engineering projects in Q4 2023 were mostly related to water and sewerage in Tolna and Bács-Kiskun counties, in Adony and Ercs regions, in Tamási and vicinity, in Várpalota and vicinity, as well as in Csemő, Cibakháza, Nagykőrös, Tiszafüred, Jászszentandrás, Tápiószőlős and Kengyel.

Most project starts are still in Eastern Hungary

In the past four quarters the biggest share of construction projects started in Eastern Hungary with the region’s share in Activity-Start being 42%. Budapest accounted for 26% of the value of projects entering construction phase. After Budapest, Northern Great Plain had the second highest share, 25%, followed by Central Transdanubia and Pest County with 10% alike. In the last 4 quarters, 21.5% of construction works started in Western Hungary, and 36% in Central Hungary.

Sunk interest in building multi-unit homes

After the promising numbers of Q2 and Q3 last year, there was another decrease in the Activity-Start indicator of multi-unit residential buildings. During the whole 2023, the value of such started constructions did not reach HUF 300 billion (-28% against 2022 and -30% against 2021). If we look at the period of 2017-2022, it only exceeded the level of 2020, however, at constant prices, the value was lower in 2023 than in 2020 (a year when the pandemic hit and VAT on new residential units was set back to 27% from 5%). It was only in 2015 when the value of started multi-unit residential constructions was lower. Compared to 2022, at constant prices, the decrease was 38%, and compared to 2021, it was more than 50%, as per the latest EBI Construction Activity Report.

This year brought major changes in state subsidies for home purchases. From 1 January, in cities only those planning to have additional children can receive CSOK+. Those who do not have additional children are only eligible for the village CSOK in beneficiary settlements. The so-called Baby Loan, although it remains available for married couples having a child, have more stringent rules. The new CSOK+ does not include a direct non-refundable support at the time of purchase, a bigger discounted loan can be applied for, and non-refundable support can only be obtained upon the birth of the 2nd and 3rd children when part of the outstanding debt is released. The new system does not differentiate between the purchase of used and new homes, making the previous advantage of new homes disappear. In addition, in case of CSOK+, one can no longer use VAT refund when buying a new home.

On a positive note, the money to be claimed has been raised, so it can be of great help in case of higher-priced new homes. Also, this year interest rates on market loans have greatly decreased compared to the beginning of last year, and it is expected to continue, so demand may recover in the new market, which may also improve the prospects of developers, encouraging the start of more projects this year than last.

In 2023 the value of Activity-Completion indicator in multi-unit housing exceeded HUF 350 billion, representing an increase of almost 28% compared to 2022, and surpassing the level of 2021 by 23%. This year also expects to see high numbers.

Although the biggest share of such constructions still started in Budapest, the capital city’s share in Activity-Start in 2023 slightly dropped over 2022. In total, around 60% of constructions started in Central Hungary, slightly more than 15% in Eastern Hungary, while the share of Western Hungary was a bit over 24%.

Western Transdanubia

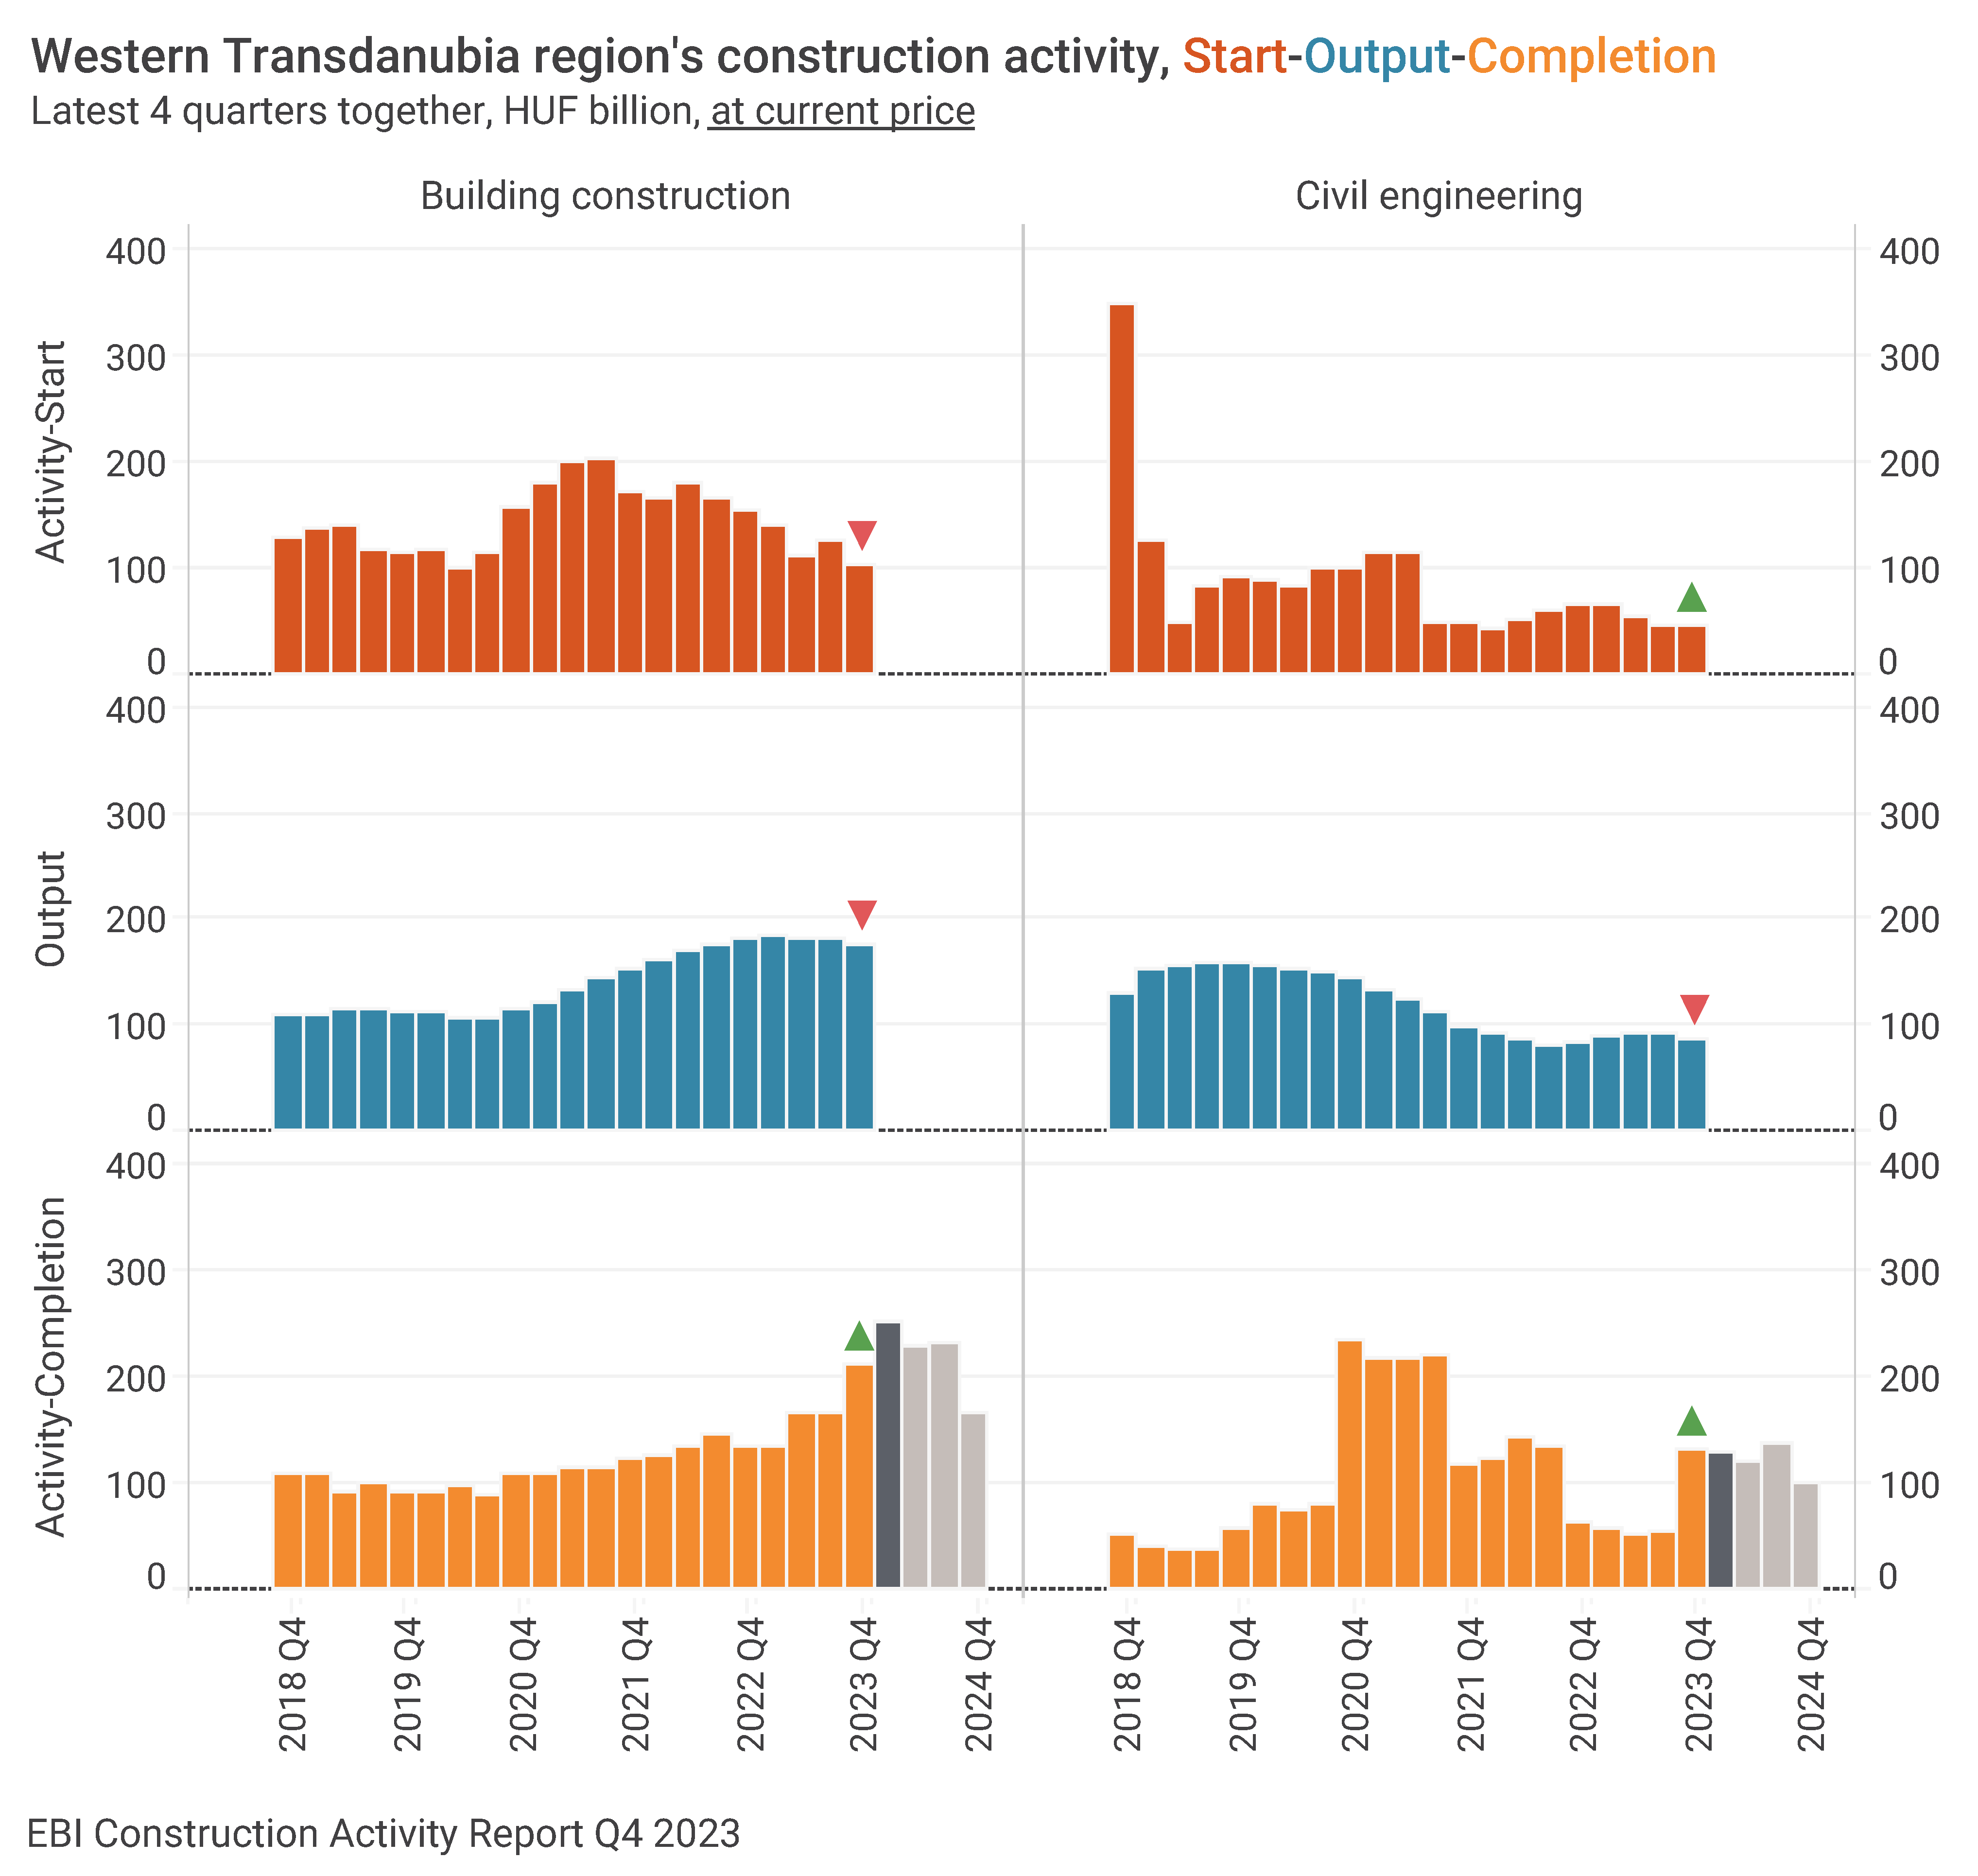
Last year around 6% of started construction works concentrated in the Western Transdanubia region, the same as in 2022. Although due to the declining Activity-Start countrywide this meant a much lower value of started constructions than the year before, the drop was 34%. In 2023 Activity-Start in the region was lower than in previous years (-34% compared to 2021 and almost -44% below the 2020 value). The previous peak in the region was in 2018 when several large-scale projects were launched: M85 highway, M8 highway, and the section of main road 76 between M7 highway and Keszthely, and a stretch of M15 highway between M1 and Rajka.

The value of started building constructions in Western Transdanubia shrank last year; over 2022 there was a 34% drop, while compared to 2021 the decrease was 41%. The projects launched in 2023 included warehouses and factories, for example, the Nestlé Purina pet food production plant and warehouse in Bük or the Velux GP4 production hall in Fertőszentmiklós.

Civil engineering works were also at a low level in 2023 (-32% against 2022, but only an 8% drop compared to 2021). In 2023, only one regional civil engineering project made it to the larger projects; Phase 3 of the Zalaegerszeg vehicle test track. The last time a hike was registered in civil engineering was in 2018 thanks to large road projects.

Recent years have seen a declining Activity-Start in building construction works in Western Transdanubia. At the same time, Activity-Completion has exhibited growth; for instance, 2023 was a record year for the value of completed building construction projects. Projects that reached completion last year comprised several plants of Nestlé Purina, the Water Adventure Park in Győr, Sirius Hotel in Keszthely, and Buildings A1, A2, A3 of VGP Park Győr Béta.

Original article: Tünde Tancsics, ELTINGA – English version: Eszter Falucskai, Buildecon

Most construction works started in Eastern Hungary

Looking at the last 4 quarters, the largest number of projects was related to the Northern Great Plains region whose share in the national Activity-Start was 30% (after a slight decrease). Budapest came second where 26% of construction works started, so its share grew. And Pest County came third with a 12% share. South Transdanubia had the smallest share in the value of started construction works (only 4% of the national value in the last 4 quarters). Overall, the biggest part of the national Activity-Start was still connected to Eastern Hungary (45%), less than 38% to Central Hungary, while the share of Western Hungary did not reach 17.5%.

Countrywide, Q3 2023 saw the value of started construction works in Hungary slightly drop over Q1-Q2 2023. Between July and September, the Activity-Start indicator of EBI Construction Activity Report accounted for a little less than HUF 600bln. This also means that the first 9 months of this year were quite modest. Activity-Start did not reach HUF 2000bln and fell short of the value of the first 9 months of 2021 and 2022. The difference compared to 2021 was 11%, while compared to 2022 there was a 35% decline. The decrease at constant prices was even greater in the first 3 quarters of 2023: compared to the first 9 months of 2021 almost 40% lower, while compared to the first 9 months of 2022 nearly 46% lower value of construction works started between January and September 2023.

Building construction

In Q3, somewhat more construction works started in building construction than in Q2, but overall, all 3 quarters brought a very similar Activity-Start. In the first 9 months of the year, the value of started building construction works totalled HUF 1400bln, less than in the same period of 2021 and 2022 (the drop compared to the former was 11%, compared to the latter it was almost 18%). At constant prices, the decrease was even bigger: the Activity-Start indicator of EBI Construction Activity Report was 40% and 31% lower between January and September 2023 than in the respective periods of 2021 and 2022. The last time we saw a value of started building construction works lower than this was in 2015.

In case of multi-unit housing construction works, the value of construction starts in Q3 was roughly at the level of Q2, but more modest than in previous years. In case of non-residential construction works there was a minimal increase in Q3 compared to Q2, but the first 9 months still saw a lower Activity-Start than in 2022 and 2021. The decrease at current price was 8% compared to the two years prior, and 15.6% compared to the same period last year. But the decline at constant price was much bigger (37% and 29% respectively). After filtering out the change in prices, the last time we saw lower numbers was in 2016.

The largest building construction projects launched in Q3 this year included several offices such as BudaPart Corso, Central and Harbor office buildings, Zugló City Center Offices 5 and 6, the reconstructions of the Ministry of Agriculture and the Palace of Justice, but also phases 1 to 4 of the Buildings A and B of the Technical Faculty of the University of Debrecen, and phase 1 of the renovation of the MTA (Hungarian Academy of Sciences) Headquarters and Library. Several industrial and warehouse projects entered construction: AN1 logistics hall of HelloParks in Alsónémedi, the production and storage hall of Leier, phase 2 of the half-shaft and cardan shaft manufacturing plant of GKN Automotive, phase 1 of Horváth Rudolf Intertransport Logistics Center, and Velux GP4’s industrial hall.

Civil engineering

After the first two successful quarters this year, Q3 brought one of the lowest Activity-Starts in civil engineering in recent years. Overall, in the first 9 months, the value of started works for the period of 2017-2022, except for 2020, fell short of the Activity-Start at current price for the first 9 months of each year. At constant prices, it barely exceeded the value of works launched in January-September 2015, while in the following period it was considered exceptionally low.

The weak third quarter was mainly owing to the drop in road construction, while some growth was recorded in non-road and railway. In the first 9 months of 2023 road and railway constructions started at much lower than the 2022 record. It exceeded the like-for-like Activity-Start of 2020 and 2021 but did not reach the value of projects started between January and September 2017 and 2019. At constant price, every year after 2015, Activity-Start surpassed 2023 in the first 9 months of the year.

Few civil engineering projects made it to the biggest construction projects. The highest-value one was the reconstruction of the Biatorbágy-Szárliget main railway line followed by several projects related to water and sewerage systems.

Pest county

When looking at the past 4 quarters, Pest county’s share of construction starts was the third highest. It was so despite the fact that in the first 9 months of 2023 there was a decline in the Activity-Start of EBI Construction Activity Report here, and based on recent years, construction works started in the county in the lowest value. In the first 9 months of this year the largest non-residential projects included the construction of CECZ E-commerce Industrial and Logistics Park and that of the logistics halls of HelloParks (Páty PT2 and Alsónémedi AN1).

The decline was attributable to the shrinkage in building construction. In the first 9 months of 2023, in Pest County construction starts were almost 40% lower than in the same period of the previous year and 17.5% lower than in the first 9 months of 2021.

Civil engineering works continued to be at a very low level in the county. Among the biggest such projects that started in the first 9 months of 2023 were the renovation of the previously mentioned Biatorbágy-Szárliget main railway line and several water and sewerage system-related ones.

Multi-unit housing

Multi-unit housing construction works continue to be lower than in previous years, and Q3 brought a slight decrease after the promising Q2 figures. Thus, overall, in the first 9 months of this year, the value of multi-unit home construction starts fell short of 2021-2022, and Activity-Start of EBI Construction Activity Report here dropped back to the 2020 level. Between January and September 2023, the value of started construction works was about 29% lower than in 2022 and 26% lower than in 2021. At constant price, the difference is much bigger (against two years ago almost 50%, while against last year a bit more than 40%). After 2015, 2023 has seen the lowest Activity-Start at constant price for the first 9 months of the year.

On 1 January 2024 a major change will be effective. In cities, the existing CSOK (the family housing allowance program) will cease. Conditions for the CSOK loan will also change: it will remain available to couples planning to have another child, but CSOK+ will provide a much higher preferential loan than previously. The higher loan can be a great help to those planning to buy a new home, but due to tight conditions, the new preferential loan will be unavailable to a massive number of customers who have been eligible until now. Another disadvantage is that so far only those claiming CSOK could benefit from the tax discount and the possibility to reclaim VAT as well.

For the multi-unit housing market, a key factor may still be the return of affordable loans, which can start purchases again, including projects. Loan interest rates decreased, but for the time being, they are still considered very high. The other question in terms of market development is the strategy of investors as they represent a serious group of buyers in the market for new homes (current high yields on government bonds are a good alternative for them compared to the housing market). Hence, no wonder that developers are careful with project launches. And even though larger investors did start some new projects, there were examples of scrapped ones.

In Q3 2023 the value of completed multi-unit buildings exceeded the like-for-like figures for 2021 and 2022. A big number of projects is expected to be completed yet this year, so this year’s value may exceed last year’s completion value if these projects are indeed completed as scheduled despite the delays.

Budapest continued to see the biggest share of multi-unit housing works start. When looking at the previous 4 quarters, the share of Central Hungary was almost two-thirds in Activity-Start. The share of Western Hungary rose over the previous quarter to over 20%, while only less than 14% of multi-unit housing construction works were connected to Eastern Hungary.

Original article: Tünde Tancsics, ELTINGA – English version: Eszter Falucskai, Buildecon

Q2 2023 sees better Construction Activity-Start in Hungary than Q1

Press Release on EBI Construction Activity Report Hungary Q2 2023

Q2 brought an improvement over Q1 in the Activity-Start of EBI Construction Activity Report: between April and June construction works started in the value of HUF 754 billion in Hungary, a more than 30% increase over Q1. It was an expansion compared to H2 2022 as well. The rise against the previous quarter was visible even at constant price, although Activity-Start was still behind the quarterly figures of 2021 and H1 2022.

The value of started building constructions keeps registering a drop

In Q2, construction works started in building construction at an even lower value than in Q1, so Activity-Start has been decreasing for the third consecutive quarter. The value of started works was barely more than HUF 400 billion; it fell by 16% in Q2 over Q1. The lag is even bigger compared to the outstanding second quarters of 2021 and 2022. At constant price, the value of building construction works started in one quarter has not been this low since 2015.

The decrease at current price was typical for non-residential constructions. Multi-unit housing recorded a minimal improvement in Activity-Start, although the indicator here stayed very low. In non-residential, the total value of works started was nearly 20% lower in Q2 than in Q1. At constant price, it was in Q3 2016 when Activity-Start was lower than this value.

The biggest projects launched in Q2 this year were the Correctional Facility in Csenger, Inpark metalworking plant in Debrecen, Boysen electric car battery plant in Nyíregyháza, HelloParks Logistics Hall in Páty, the next building of Weerts Logistics Center, and several larger multi-unit residential projects.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Buildecon, Eltinga (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). EBI Construction Activity Report Q2 2023 has been published and can be purchased at ebi@ibuild.info.

Civil Engineering Activity-Start sees a considerable expansion

The Q2 2023 Civil Engineering Activity-Start of EBI Construction Activity Report posted a more than 30% growth against the corresponding period a year earlier. And compared to Q3 and Q4 2022, as well as Q1 2023, the increase was exceptional. The last time Activity-Start in the segment was higher than this was in Q1 2022. In April-June 2023, the value was close to HUF 350 billion and the increase was noticeable even at constant price: in comparison with Q1 2023, the value of started construction works nearly quadrupled. But compared to previous years, this Activity-Start at constant price cannot be called an outlier.

Continue reading Q2 2023 sees better Construction Activity-Start in Hungary than Q1

Poor Q1 2023 construction Activity-Start in Hungary

Press Release on EBI Construction Activity Report Hungary Q1 2023

Q1 2023 saw very low Activity-Start in the Hungarian construction industry with only HUF 374 billion worth of construction works started, according to the latest EBI Construction Activity Report. Such a low value of construction start within three months has not been seen since 2016. Compared to the outlier Q1 2022, Activity-Start fell by almost a quarter, but compared to the first three months of 2021, the drop was more than 40%. The value of started works seems particularly modest and the extent of falloff particularly large if we consider that the sector has recently experienced massive price changes. At constant prices, it was only in 2012 when a lower volume of construction works started during three months, and the drop against Q1 2021 already surpasses 60% at constant prices.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Buildecon, Eltinga (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). EBI Construction Activity Report Q1 2023 has been published and can be purchased at ebi@ibuild.info.

Decline not sparing building construction work starts

The value of started building construction projects did not reach HUF 300 billion in the first three months of 2023. It has been one of the most modest quarters in recent years and last time Q2, Q3, and Q4 2020 registered construction starts of a similar value. The decrease in Activity-Start against the first quarters of 2021 and 2022 was 42%-48%. At constant prices, the drop is even more visible: such low numbers were last seen in the segment in 2013-2014.

Both residential and non-residential buildings recorded a decline in Activity-Start. In the former, the value of started construction works stayed below HUF 40 billion, while in the latter, Activity-Start was around HUF 260 billion. At constant prices, these numbers represented the 2014-2015 volumes.

Biggest building construction projects launched in Q1 2023 included several logistics centres like Robert Bosch Power Tool logistics centre in Miskolc, BMW logistics centre in Debrecen, Waberers centre in Ecser, or Blister-Labor-Telemedicina centre in Bicske. The construction of several factories and warehouses also started such as Schneider Electric’s Duna Smart Power System smart factory in Dunavecse, Phase 2 of the Mercedes-Benz body part production plant and Phase 2 of its assembly plant in Kecskemét; another phase of Nestlé Purina pet food production plant in Bük or Rheinmetail ammunition factory in Várpalota. Two large hotel construction projects also began: Sofitel Budapest Chain Bridge Hotel and Movenpick Palace Hotel Budapest.

Few civil engineering works began

Civil engineering Activity-Start continued to decrease after Q2, Q3 and Q4 2022. The total value of started civil engineering projects did not reach HUF 80 billion (the lowest value since 2016), and at constant prices the volume has never been so low in any quarter since 2012.

In road and railway construction, projects started in the value of only about HUF 20 billion, while non-road and non-railway constructions saw an Activity-Start of about HUF 60 billion, roughly the level of Q3-Q4 2021 and Q1 2022.

In Q1 2023 hardly any civil engineering project was among the largest ones. Major projects included the recultivation of the Oroszlány tailings site, the Budapest Freeport project, and the development of Hungaroring’s utility network.

Northern Great Plain ahead of Budapest

Looking at the last four quarters, the highest value of construction projects started in the Northern Great Plain region with a share of roughly 23%. Budapest saw the second highest value of construction starts, while Pest County came third. With this, around 37% of the national Activity-Start was realized in Central Hungary. About 40% of started construction works belonged to Eastern Hungary, while slightly more than 20% of the Activity-Start was connected to Western Hungary with 5% of Activity-Start in Southern Transdanubia.

Hardly any multi-unit housing project-start

The first three months of this year registered very few multi-unit housing project starts. The last time the value of Activity-Start was lower than the current one was in Q3 2020. Before that only the quarters of 2015 saw a similar amount. The drop is even more significant at constant prices: the Q1 2023 level recalls the 2014 volume. In the last quarter of last year several developers decided to launch a new phase of their projects because of which, despite unfavourable market conditions, Activity-Start increased compared to previous quarters. That is why it was expected that the following three months would not be the time for major construction starts. Yet, the two quarters together reported weak figures.

Continue reading Poor Q1 2023 construction Activity-Start in Hungary

Q4 2022 sees a continued low value of construction starts in Hungary

Press Release on EBI Construction Activity Report Hungary Q4 2022

The latest EBI Construction Activity Report has found that after the weak Q3 2022, Q4 2022 saw a slight nominal expansion in Activity-Start in Hungarian construction. Nonetheless, the value of started construction works was still very low; between October and December 2022 they totalled roughly HUF 650 billion.

This time, though, for better comparability, the analysts of EBI Construction Activity Report also looked at the development of Activity-Start in Q4 2022 at constant prices. This shows that Q4 witnessed a considerably lower construction value, a bit more than Q3 (the negative record in recent years). Yet, whole-year-figures were high thanks to the higher Activity-Start in the first two quarters of 2022 and projects entered construction on more than HUF 3600 billion. Although it was a new record at current prices, it did not approach the highest values of 2017 and 2018 at constant prices and was at the level of 2019 and 2021. Annual change compared to 2021 at current prices was about +21%, while at constant prices it meant a drop of 0.6%.

EBI Construction Activity Report Hungary analyses the construction industry on a quarterly basis, including the volume of newly started construction works and the value of projects completed in each quarter in aggregate and by segment as well. It is prepared by Buildecon, Eltinga (creation of indicators and development of algorithms for aggregation) and iBuild (project research and project database). The EBI Construction Activity Report Q4 2022 can be purchased at ebi@ibuild.info.

Expansion in value of started building construction works

The modest rise in Activity-Start at current prices was mostly coming from the expansion of building construction with the value of started construction works being HUF 500 billion in Q4 2022. Overall, the entire 2022 brought high numbers. Projects worth more than HUF 2000 billion entered implementation – the highest ever registered.

In Q4 the improvement over Q3 was evident in building construction even at constant prices. But the value of started works, except for 2020, was lower than the quarterly values of the past years. At constant prices, the Activity-Start indicator dropped during 2022 (-16.8%) and was roughly at the level of 2019. The better last three months were also typical for multi-unit housing and non-residential buildings, whether we look at current or constant prices.

In 2022, non-residential construction works were launched at a value of more than HUF 1800 billion, the highest amount so far. Thanks to the good first half of the year, even at constant prices, last year was considered a strong year: constant-price Activity Start of EBI Construction Activity Report was the third highest after 2018 and 2021.

Building construction projects launched in Q4 2022 included the CATL battery factory, the BMW plant, and the EcoPro BM electric battery cathode manufacturing plant in Debrecen.  Construction also began on the CTP warehouses in Szigetszentmiklós, the University of Veterinary Medicine and the Siemens Energy M2B gas and steam turbine parts manufacturing plant in Budapest, as well as the logistics hall of HelloParks in Fót.

Continue reading Q4 2022 sees a continued low value of construction starts in Hungary